
0 ITEMS

What Is the Discounted Cash Flow Valuation Method?
Understanding the discounted cash flow (DCF) valuation method is essential for accurate business and asset valuation.
- DCF estimates a company’s value by discounting future free cash flows to their present value, often using a 3-5 year financial forecast.
- It relies on analyzing past financial statements and setting realistic assumptions for revenue, costs, and growth rates.
- The discount rate, typically based on WACC, accounts for risk and the time value of money to adjust future cash flows.
- Terminal value captures long-term worth beyond the forecast period, usually calculated with growth or multiples-based formulas.
- Financial models improve DCF accuracy by organizing key assumptions and providing transparent, actionable insights.
Keep reading to understand how to implement and refine this powerful valuation technique.
Understanding the Discounted Cash Flow Valuation Method
As the name says, the discounted cash flow valuation method (or DCF method) values companies or assets by discounting their future projected free cash flows to their present values. This requires the availability of a 3 to 5-year financial plan from which future expected free cash flows could be derived.
Analyzing Past Data
Discounted cash flow valuation begins with analyzing past data to understand a company’s financial health. This step involves reviewing historical financial statements like income statements, balance sheets, and cash flow reports. These records reveal trends in revenue, expenses, and profit margins. By spotting patterns and understanding past performance, analysts can make informed assumptions about future cash flows. Accurate projections depend on this groundwork, making it a vital first step in the valuation process.
Defining Assumptions
After reviewing past data, the next step in the discounted cash flow valuation model is to define assumptions. These include estimates for future revenue, costs, growth rates, and capital expenditure needs. Clear assumptions help shape realistic cash flow projections. They also reflect how the business might perform under different conditions. This step builds the foundation for reliable forecasts and better decision-making.
Projecting Free Cash Flow
The third step is estimating how much cash the business will generate after covering operating costs and capital expenses. These future cash flows show the company’s earning power. Use the defined assumptions to forecast them year by year. Accurate cash flow projections are key to valuing the business correctly. The basis of any DCF method is the free cash flow projections from a multi-year financial plan or business plan. The best way to develop a financial plan is to start with the financial statements. Here is what the financial forecast might look like:
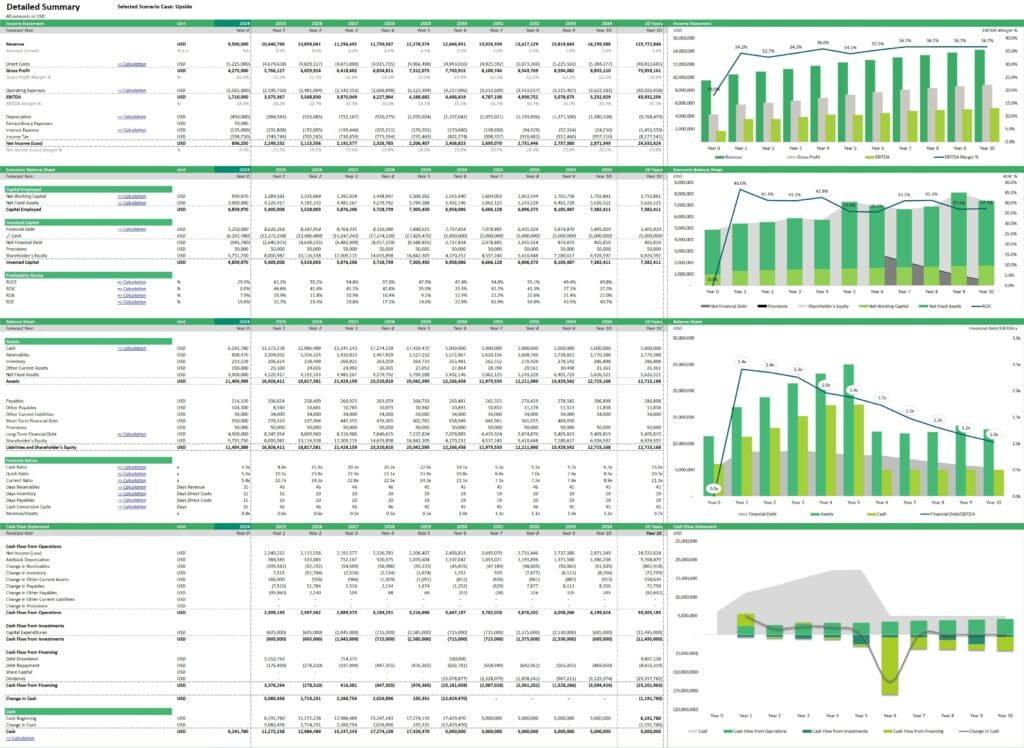
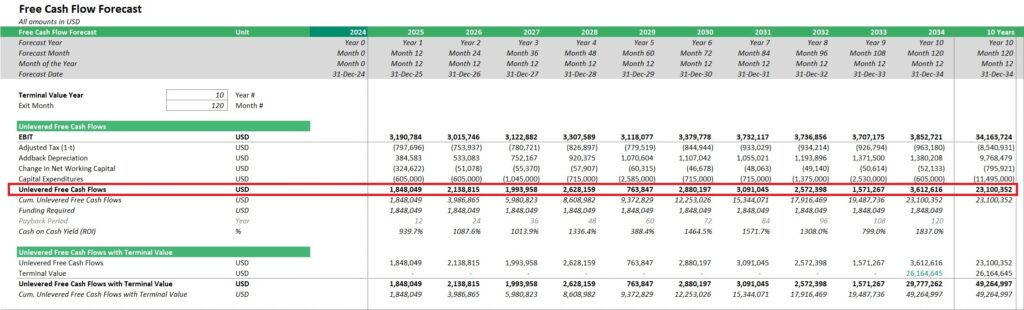
Discounted cash flow valuation requires to develop the Free Cash Flows. Normally, these are the free cash flows available to the firm (FCFF). Please note that the definition of these cash flows is different from the standard Cash Flow Statement as we exclude all cash flows from Financing Activities, and we “simulate” how the cash flows would look without taking into account the effects of the financing structure. Therefore, in our discounted cash flow valuation example, we apply the income tax rate on EBIT (Earnings before Interest and Taxes).
Determining the Discount Rate
The fourth step is determining the discount rate. This rate reflects the investment’s risk and the time value of money. A higher risk means a higher discount rate. It helps adjust future cash flows to their present value. Choosing the right rate is crucial because it directly affects the valuation result. Risk is measured as the opportunity cost of capital. Instead of investing in a company or an asset, the funds could be invested in a project with similar risks in the stock market.
According to finance theory, the discount rate should reflect the opportunity costs of investing in a business with a similar risk profile. Discounted cash flow valuation uses the Weighted Cost of Capital (WACC) as the discount rate in the DCF method. WACC weighs the cost of debt and the cost of equity financing used and calculates the average cost of capital. Please refer to this article, which explains how to calculate the discount rate when using the DCF method. Additionally, check out one of the WACC Calculator Templates here.


Calculating Terminal Value
The fifth step is calculating the terminal value. This value estimates cash flows beyond the forecast period. It captures the business’s long-term worth. Use steady growth assumptions to maintain realism. The terminal value often makes up a significant portion of the total valuation. Getting it right is key to a solid result.
The problem with using discounted cash flows for valuation purposes is that a company (or an asset) will often produce cash flows beyond a 5-year time horizon. Companies with solid business models have been around for many years (e.g., Wells Fargo, dating back to 1852; UBS, Switzerland, which dates back to its origins in 1862; Coca-Cola, founded in 1886; and 3M, established in 1902). This means we need to attribute value for the period from year 6 up to an infinite end.
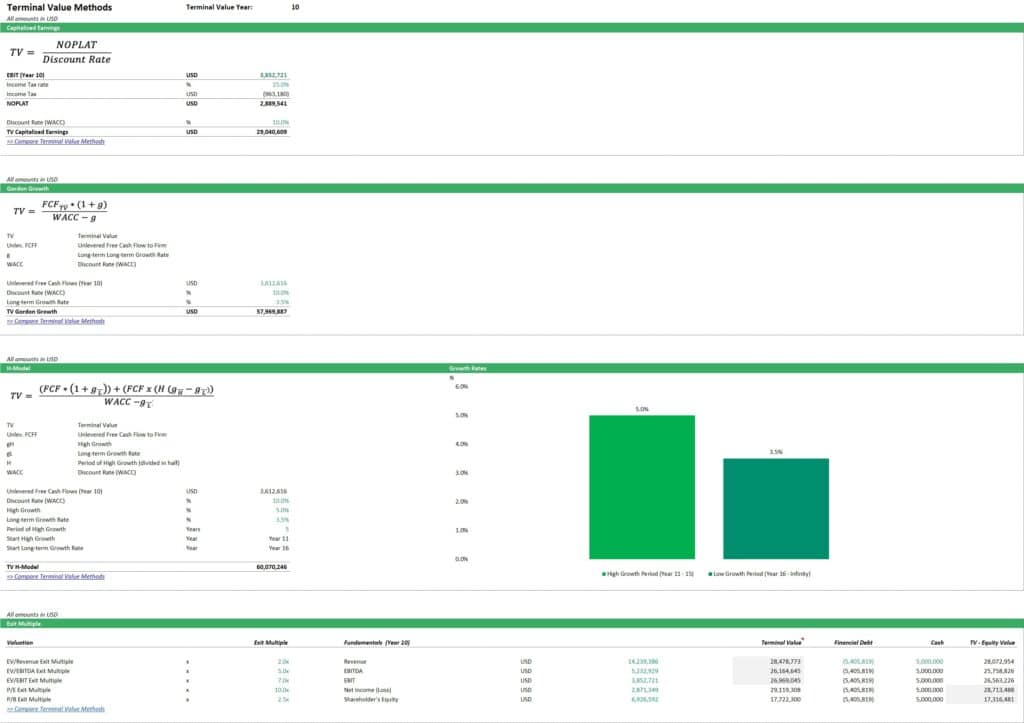
To do this, calculate the terminal value. Simple formulas to calculate the terminal value are:
- Multiple-based valuation, e.g., based on EV/EBITDA multiple
- Gordon growth formula (Last Year Cash Flow *(1+g) / (WACC -g)), whereas g equals a long-term growth rate, and WACC will be the discount rate
There exist more terminal value formulas, but for our purposes, what’s important is that there needs to be value attributed for the period beyond the forecast year 5. Normally, the terminal value is calculated as per the end of year 5, which means it needs to be discounted to year 0, together with the free cash flow of year 5. For our purposes, we calculated the terminal value as per the end of year 10 for our Advanced Discounted Cash Flow (DCF) Valuation Model Template.
Estimating Present Value
The next step is to estimate the net present value (NPV). This means converting future cash flows and terminal value into today’s dollars using the discount rate. It shows what those future earnings are worth right now. Add each year’s discounted cash flow to get the total value.
Why is the cash flows discounted? This is to reflect the logic that cash in the future is less valuable compared to cash at hand. Therefore, expected cash flows in the future are an estimation and subject to inherent business risks. The discounting procedure factors this in and adjusts the free cash flows for those risks. The more the cash flows lie in the future, the higher the risk and the larger the discount (by increasing the discount rate) to be applied.
Calculating Enterprise and Equity Value
The last step is calculating enterprise and equity value. Start with the present value of all future cash flows to get the enterprise value. Then, subtract net debt to find the equity value. This final figure represents the business’s value to its shareholders. It’s the end goal of the entire valuation process.
As the discounted free cash flows are summed up, the net present value (NPV) of all future cash flows to firm are calculated.

By using discounted cash flows for business valuation, the net present value corresponds to the enterprise value of the business, which values the company independently of the debt/equity financing structure used. This means we have to deduct financial debt and add cash (or some valuation experts only add excess cash as some of the cash might be needed to operate the business) together with net debt in order to arrive at the equity value. Now our discounted cash flow valuation model is complete.
Below is an example screenshot showing the calculations for each important component of a discounted cash flow valuation model:
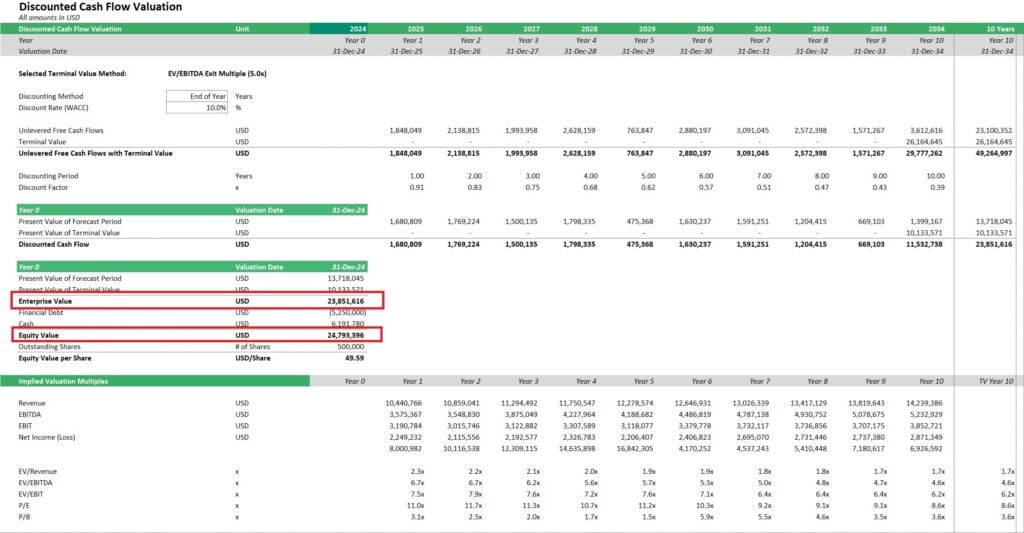
Doing a discounted cash flow valuation can be tricky, especially with all the factors that should be considered when applying it. Below is a simplified version of each step to guide you if you’re still new to the approach. While you’re at it, you can also download the following DCF templates to act as your guide for each step. We even provided a sample template for a restaurant business so you can see how to actually apply it.
- Advanced Discounted Cash Flow (DCF) Valuation Model Template
- DCF Valuation Model Restaurant
- Discounted Cash Flow Excel Model Template

Why Is DCF Considered a Fundamental Valuation Method?
When valuing a business, you normally have the choice between using discounted cash flow for valuation or alternative valuation methods such as market and recent transaction multiples, replacement cost approach, capitalized earnings valuation, etc. So in which cases would you opt to use the discounted cash flow valuation method? The discounted cash flow valuation technique is a comprehensive valuation method that can be used to value both publicly traded companies and privately held businesses. Very often, the method of using discounted cash flow for business valuation purposes is also used in combination with other business valuation methods.
So when is the discounted cash flow valuation technique being used? – Here are some common use cases where normally the DCF method is being used for valuation purposes:
- Valuation of real estate assets such as commercial buildings or other rental properties
- Business valuation (publicly traded stocks as well as privately held companies)
- Valuation of intangible assets such as patents, brands, trademarks, and customer relationships
Preference for the DCF valuation method is given when:
- Quantifying the valuation impact of synergies in the context of business acquisitions
- More precision is needed than other valuation methods can give (e.g., multiples valuation or capitalized earnings valuation)
- Your business/asset is very specific, and there exist no comparable valuation benchmarks to use
- If you are dealing with massive pending investments which will affect the value of the business
- You like to compare different business scenarios and their valuation impact.
The other question is, in which cases would it not be a good idea to use the DCF valuation method:
- If you feel the business plan or its assumptions cannot be relied upon
- If other valuation methods lead to a faster or simpler way to value a business or an asset
- If the target audience of your valuation result does not understand the DCF valuation method or feels the assumptions are subjective and one-sided.
- If market prices paid in your industry vary heavily from the results of a discounted cash flow valuation.
- If the net present value of a discounted cash flow valuation becomes negative. Then, the question arises whether it would not be better to liquidate and shut down the company.
As you can see, the DCF valuation – like any other valuation method – needs to apply to a suitable situation.
What Are the Limitations of a Discounted Cash Flow Valuation Model?
While powerful, the discounted cash flow valuation model has its limits. Because of this, the model requires careful judgment and should be used in conjunction with other valuation methods.
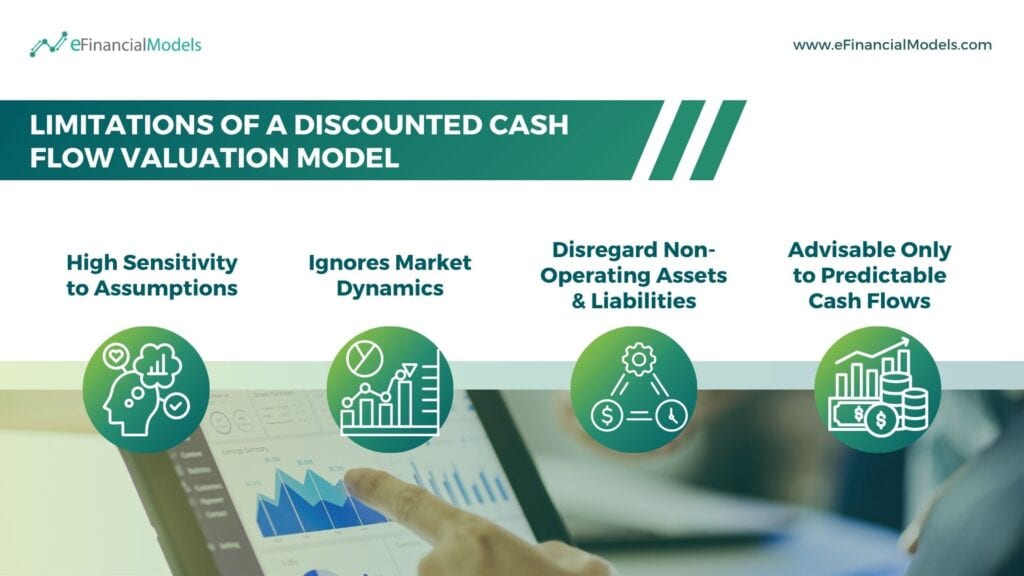
- High Sensitivity to Assumptions: A discounted cash flow valuation model relies heavily on future estimates, which can be uncertain or overly optimistic. Forecasting free cash flows far into the future (5–10 years or more) involves substantial uncertainty, particularly for startups or companies in cyclical industries. Small changes in the discount rate can significantly impact the present value of future cash flows. Often, a large portion of the valuation, the terminal value, is based on a perpetual growth rate that can easily overstate or understate value if misestimated. If your assumptions are even slightly off, the model can produce misleading valuations, making it more of an art than a precise science.
- Ignores Market Dynamics: Market shifts or unexpected costs may also throw off projections. The discounted cash flow valuation model ignores market prices influenced by sentiment, trends, and liquidity. It doesn’t consider how comparable companies are valued in the market. So, a business may appear undervalued or overvalued in a DCF model despite market realities suggesting otherwise.
- Disregard Non-Operating Assets & Liabilities: The discounted cash flow (DCF) valuation model primarily values a business based on its operating cash flows; however, this approach creates a limitation when non-operating assets and other liabilities are involved. Non-operating assets—like excess cash, investments, or real estate—don’t generate operating cash flow, so they’re excluded from the DCF but must be added separately to avoid underestimating value. Similarly, hidden liabilities, such as pensions or legal obligations, aren’t captured in free cash flows but still affect equity value. If not adjusted for, the DCF can give an incomplete or misleading picture of what the business is truly worth.
- Advisable Only to Predictable Cash Flows: The discounted cash flow (DCF) valuation model is most effective for businesses with stable and predictable cash flows. This method relies on future cash flow estimates, so accuracy is critical. If a company’s earnings are erratic or uncertain, DCF results can be misleading. It becomes unreliable when applied to businesses with irregular, negative, or unpredictable cash flows, such as startups, turnaround firms, or companies in cyclical industries. In such cases, other valuation methods (like multiples or real options) may be more appropriate.
From Projections to Precision: How Financial Models Empower DCF
The discounted cash flow valuation method is widely used among financial analysts and valuation professionals, especially for business valuation purposes. It is one of the most reliable valuation techniques, representing an income-based approach to valuation. Discounted cash flow valuation starts with analyzing past data, followed by setting clear assumptions. Next, it projects free cash flow, selects an appropriate discount rate, and calculates the terminal value. These figures are used to estimate the present value and determine both the enterprise value and the equity value.
The beauty of this method is that the valuation logic becomes very transparent. Therefore, it can also trigger a constructive discussion about the most likely business scenario, as it leads to questions about how important value drivers are likely to behave in the future.
Financial models turn rough projections into precise estimates by organizing key data and assumptions. They help track revenue, costs, and cash flow with clarity and consistency. This structure boosts confidence in the numbers behind each forecast. By laying a solid foundation; financial models make the discounted cash flow valuation model more accurate, reliable, and actionable for decision-makers.
Download the generic quick DCF Template here:
Using discounted cash flow for business valuation purposes has many practical uses in a variety of situations, starting from the valuation of properties in real estate, company valuations, valuation of intangible and other assets, as well as evaluating the valuation impact of various business scenarios.
The beauty of this method is that the valuation logic becomes very transparent and, therefore, can also trigger a constructive discussion about the most likely business scenario as it leads to questions of how important value drivers are going to behave in the future.
























You might also like:
- 10 Tips to Develop a First Class Business Valuation Report
- 5 Steps to Create a Drop Down List Using Data Validation in Excel
- 10 Main Elements of a Business Plan
- Understanding the Levelized Cost of Energy Formula
- Calculating Revenue Growth Rate: A Key Metric for Business Success
- Finding a Valuation Model for Your Business
- Financial Modeling for Startups and Small Businesses
- Financial Model Templates Easy to Use
- Top 10 Mistakes in DCF Valuation Models
- Financial Planning for Small Business Owners – Taking an SBA Loan
- Business Valuation Service
- Financial Ratios Analysis and Its Importance
- Understanding What is Yield to Maturity and Why It Matters
- Financial Analysis Using Excel
- Understanding the Debt Service Coverage Ratio: An Essential Metric for Financial Analysis
- Discount Rate
- Financial Planning Retirement Tips
- Entrepreneurs: Financial Model Templates for Essential Scenarios
- Valuation
- How to Use Excel for Financial Analysis?
