
0 ITEMS

How to Get a Mortgage for Land or a Business Loan in 2023: A Financial Guide for Smart Decision-Making
48
0
0
October 13, 2023
Table of Content
In today’s fast-paced economic landscape, acquiring a mortgage for land or securing a business loan can be a pivotal step in your financial journey. Whether you’re an entrepreneur looking to expand your business or an investor eyeing a lucrative piece of land, understanding the financial intricacies of these loans is crucial. Let’s delve into the essentials of getting a mortgage for land or a business loan, all while keeping your financial health in check.
The Importance of Financial Modelling
Before we get into the nitty-gritty, it’s worth mentioning that financial modelling can be an invaluable tool in this process. Platforms like eFinancialModels offer a range of financial model templates that can help you assess the feasibility of your loan, calculate repayments, and even forecast potential ROI. This kind of preparation not only impresses lenders but also prepares you for a sustainable financial future.
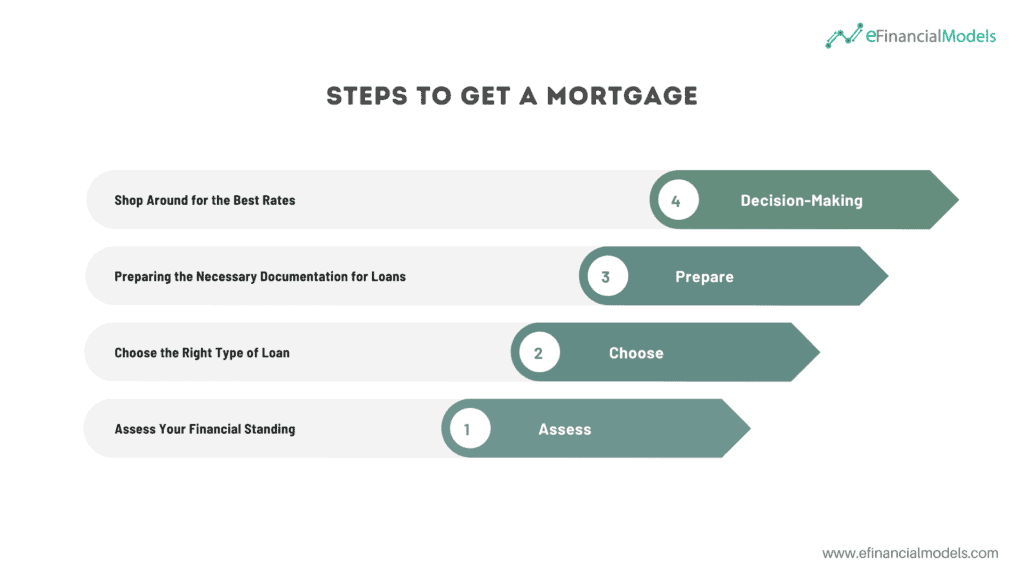
Assess Your Financial Standing
The first step in any loan application process is to evaluate your financial health. Your credit score, debt-to-income ratio, and other financial metrics will be scrutinized by lenders. A credit score of 700 or above is generally considered good, while a debt-to-income ratio below 43% is ideal.
Choose the Right Type of Loan
Mortgage for Land: The Lay of the Land
1. Raw Land vs. Improved Land
When it comes to land, not all plots are created equal. Raw land is essentially a blank canvas, devoid of utilities like water and electricity. While it offers more creative freedom, it’s generally harder to finance. Improved land, on the other hand, comes with basic infrastructure and is easier on the financing front.
Tip: If you’re eyeing raw land, consider using financial models to project the cost of adding infrastructure. This will give you a clearer picture of your total investment.
2. Down Payment: The Entry Ticket
The down payment is your initial investment in your land purchase. Generally, you’ll need to put down between 20-50% of the land’s cost. The exact percentage can vary based on the lender’s policies and the quality of the land.
Tip: A higher down payment can often secure you a lower interest rate, reducing your long-term financial burden.
3. Interest Rates: The Cost of Borrowing
As of 2023, interest rates for land mortgages hover around 4-5%. While this might seem like a small percentage, it can add up over time, affecting your ROI.
Tip: Use financial models to calculate how different interest rates will impact your monthly payments and overall investment returns.
Business Loans: Fuel for Your Enterprise
1. Term Loans vs. Line of Credit
Term loans provide a lump sum upfront, with a fixed repayment term. They’re great for one-time investments like buying equipment. A line of credit offers more flexibility, allowing you to draw funds as needed, but may come with higher interest rates.
Tip: Assess your business’s cash flow to determine which loan type aligns with your financial needs and repayment capabilities.
2. Interest Rates: The Price Tag
Interest rates for business loans can vary widely but generally range from 6-9% as of 2023.
Tip: A lower interest rate can significantly reduce your total repayment amount, so shop around for the best rates.
3. Collateral: The Safety Net
Some business loans may require collateral, which can be in the form of business assets or even personal assets. This reduces the lender’s risk but increases yours.
Tip: Only put up collateral that you’re willing to lose, and understand its value to ensure you’re not over-leveraging yourself.
Preparing the Necessary Documentation for Loans: Your Financial Blueprint for Success
Navigating the world of loans can be like walking through a maze. Whether you’re eyeing a piece of prime real estate or planning to scale your business, the path to securing that crucial loan often boils down to one thing: impeccable documentation. In this guide, we’ll explore the essential documents you’ll need to prepare for a smooth loan application process, all from a financial and investing standpoint.
Why Documentation Matters
Think of your loan documentation as your financial resume. It’s what lenders use to gauge your creditworthiness and the viability of lending to you. Just like you wouldn’t go to a job interview without a well-prepared resume, you shouldn’t approach lenders without a comprehensive set of documents.
1. Proof of Income:
Your income is the cornerstone of your loan application. Lenders want to know you have a reliable source of income to make repayments. Typically, you’ll need to provide:
– Recent pay stubs or salary slips
– Bank statements showing regular income
– If self-employed, profit and loss statements
2. Business Plan (For Business Loans):
If you’re applying for a business loan, a robust business plan is non-negotiable. This document should outline:
– Business objectives and mission
– Market analysis and competition
– Financial projections and cash flow forecasts
3. Land Appraisal or Business Valuation:
Whether you’re buying land or investing in a business, knowing its worth is crucial. An appraisal or valuation provides a realistic market value, which lenders use to assess the loan amount they’re willing to offer.
4. Credit History:
Your credit history is like your financial report card. A good credit score can open doors to lower interest rates and better loan terms. Before applying for a loan, you should obtain a copy of your credit report and correct any errors.
5. Tax Returns:
Tax returns offer a snapshot of your financial health over an extended period. Usually, lenders will ask for tax returns for the past two to three years to assess your financial stability.
Shop Around for the Best Rates
Don’t settle for the first offer you get. Shopping around could save you thousands over the life of the loan. Use financial models to compare different loan terms and conditions to find the best fit for your financial situation.
Securing a mortgage for land or a business loan is not just about getting the funds; it’s about making a financial commitment that will impact your future. By understanding the financial aspects, choosing the right type of loan, and preparing thoroughly, you set the stage for a prosperous financial journey.
Remember, platforms like eFinancialModels can provide you with the financial models you need to make this important decision with confidence. So why wait? Take control of your financial destiny today.
Feel free also to check out our full list of industry-specific financial model templates here:


The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... read more


The Private Equity Fund Cashflows Model helps LPs and GPs analyze fund cash flows, returns, and dist... read more


The Coffee Shop Financial Model helps entrepreneurs, founders, business owners, consultants, and ana... read more

The Hotel Financial Model helps users build a structured financial forecast for a hotel business usi... read more


Lifetime access to all future templates as well! Here is a set of spreadsheets that have some of the... read more

We are introducing our 4-Tier Waterfall Profit Distribution Model. The waterfall profit distribution... read more


Dynamic 10-Year Financial Model, suitable for any type of business, supporting strategic planning, i... read more

This green hydrogen financial model template builds a multi-year financial plan to analyze the finan... read more

The Grocery Store Financial Model helps entrepreneurs, founders, consultants, analysts, and retail b... read more

Key logic designed to forecast cash flow up to 10 years for a fitness center that has recurring mont... read more


The Model Incorporates data provided by different available sources to Model an Electrolysis financi... read more

Includes all the assumptions you need to project the gross revenues and profits of a LaaS platform (... read more

Highly-sophisticated and user-friendly financial model for Startup Companies providing a 5-Year adv... read more

The Bakery Financial Model helps entrepreneurs, bakery owners, consultants, analysts, and business p... read more


Average rating:Submit Rating
Model for in depth understanding of high level profit and loss and revenue analysis. Big-4 like chec... read more

The Cafe Financial Model is a ready-to-use financial model template designed to help entrepreneurs, ... read more

The Clothing Store Financial Model helps turn a retail apparel concept into a structured financial f... read more

The Poultry Farming Financial Model helps users turn a poultry farm concept into a structured, lende... read more

A general real estate model to plan all assumptions for up to 7 'uses' for a given property. Include... read more

The Online Clothing Store Financial Model helps founders, entrepreneurs, business owners, consultant... read more

The Dental Clinic Financial Model helps users turn a dental practice concept, launch plan, or expans... read more

This poultry financial model template in Excel provides a framework to determine the financial feas... read more

Launching a manufacturing startup can be complex, and securing financing requires a solid financial ... read more

The Spa Financial Model helps entrepreneurs, spa owners, consultants, analysts, and business planner... read more

The Boutique Hotel Financial Model Financial Model Template helps entrepreneurs, hotel owners, consu... read more
The Nail Salon Financial Model Financial Model Template helps entrepreneurs, salon owners, consultan... read more


This excel template is great for those wanting a professional-looking forecast 10 years of financial... read more
This coffee farm financial feasibility model template prepares a financial plan for your next coffee... read more

Professional Financial Modeling - Tailor Made Services and assistance for your business needs.
The Fintech Startup Financial Model helps founders, analysts, consultants, and business planners tur... read more
The Medical Practice Financial Model helps users turn a clinic concept, expansion plan, or healthcar... read more
Average rating:Submit Rating
The Solar Panel Manufacturing Financial Model helps users turn a solar factory concept into a struct... read more
The Car Rental Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... read more
" The Restaurant Financial Model helps users turn a restaurant concept into a structured, editable f... read more
The Pizza Restaurant Financial Model Template helps entrepreneurs, restaurant owners, consultants, a... read more

The Personal Budgeting App Financial Model Financial Model Template helps founders, entrepreneurs, c... read more
This is a collection of financial model templates that provides the financial projections and valuat... read more
A 5-year financial model tailored to starting a golf course and projecting financial performance for... read more
The Beauty Salon Financial Model helps entrepreneurs, salon owners, consultants, analysts, and found... read more
The Fish Farming Financial Model template helps entrepreneurs, aquaculture founders, business owners... read more

Project Finance Model for a Solar (PV) Power Plant projecting revenue, operating costs, and cash flo... read more


A professional template to budget payroll expenses

Average rating:
A self-made Modeling Test with a solution for Onshore Wind Turbines plant. The case study is in Chil... read more
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... read more
Distilleries, with their rich history of crafting spirits, have experienced a resurgence in populari... read more
Advanced 10-year financial model for a Software as a Service (SaaS) business providing a solid finan... read more

Average rating:Submit Rating
Online Car Rental Platform Business Plan Model is a perfect tool for a feasibility study on launchin... read more
Allow a potential miner to see visually and numerically (annual basis) what their possible financial... read more

Merger and Acquisition Model template consists of an excel model which assists the user to assess th... read more

Setting up a biodiesel manufacturing plant requires a comprehensive and executed business strategy. ... read more
There are currently 52 unique financial models included in this bundle. Nearly all of that include a... read more

The Cannabis Business Financial Model is a ready-to-use financial model template designed to help en... read more
The Skin Care Clinic Financial Model helps entrepreneurs, clinic owners, consultants, analysts, and ... read more
The Clothing Manufacturing Financial Model helps users turn a garment production concept into a stru... read more
The Flower Shop Financial Model helps entrepreneurs, florists, business owners, consultants, and ana... read more
The Bar Financial Model Financial Model Template helps entrepreneurs, bar owners, consultants, analy... read more
The Healthcare Clinic Financial Model helps founders, clinic owners, consultants, analysts, and busi... read more

The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... read more

The Laundry Service Financial Model helps entrepreneurs, business owners, consultants, analysts, and... read more
Financial Model providing a 10-year financial plan for a startup or operating Subscription Business.
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... read more
The Catering Service Financial Model helps users turn a catering business plan into a structured, ed... read more

The Freight Brokerage Financial Model Financial Model Template helps entrepreneurs, founders, busine... read more

The Law Firm Financial Model Template helps users turn a legal practice concept into a structured fi... read more

The Cattle Farming Financial Model helps users turn a cattle farm concept, expansion plan, or fundin... read more

Average rating:Submit Rating
Build up to a 10 year financial forecast with assumptions directly related to the startup and operat... read more

5-year financial model for a hair and beauty salon providing revenue forecasts, cost analysis, and i... read more

This Hotel / Holiday Resort Development Model will take you through a 20-year period of Three Statem... read more
The Casino Hotel Financial Model helps users build a structured five-year forecast for an integrated... read more
The Vegetable Farming Financial Model helps users turn a farming concept, expansion plan, or funding... read more
The Juice Bar Financial Model helps entrepreneurs, founders, consultants, analysts, and business own... read more
Average rating:Submit Rating
Electric Vehicle (EV) charging Station FM helps user asses financial viability of setting up and ope... read more


This financial model can be used to value any Initial Public Offering (IPO) using Option Value, DCF ... read more

Average rating:Submit Rating
3 statement 5 year rolling financial projection Excel model for a startup /existing manufacturing bu... read more
Purchase Dairy Farming Financial Projection. Sources & Uses, Profit & Loss, Cash Flow ... read more
The Private Equity Oil and Gas Financial Model evaluates the financial feasibility and investor retu... read more

The Food Manufacturing Financial Model helps entrepreneurs, founders, consultants, analysts, and bus... read more

This financial model attempts to give the user a full scope of starting a 250 bed (adjustable) hospi... read more
Average rating:Submit Rating
The SaaS Business Financial Model helps founders, entrepreneurs, consultants, analysts, and business... read more
Financial model presenting a Crop Farm business scenario.
The Candy Store Financial Model helps entrepreneurs and planners turn a retail confectionery concept... read more
Take this opportunity and get a discount by getting the Renewable Energy Bundle where you get Solar,... read more
The Bed and Breakfast Financial Model is a ready-to-use financial model template built to help entre... read more

Our Mini-Storage Financial Model Template is your all-in-one solution for building a profitable and ... read more

Financial Model presenting a business scenario of a corporation engaged in granting loans from its o... read more

The purpose of this Bundle of Business Forecasting and Financial Models is to assist Business Owners... read more


In order to assess the financial viability of a Solar Park project, the Solar Energy Financial Model... read more
This Car Rental Business Financial Model Template in Excel offers an ideal basis for developing a bu... read more

Average rating:Submit Rating
User-friendly template including two different methods of modeling an initial public offering (IPO) ... read more
This comprehensive 40-year tool aid investors in evaluating potential risks and returns and assess t... read more

The Architectural Firm Financial Model Template helps founders, architecture practice owners, consul... read more

The objective of the Geothermal Energy financial feasibility model template is to analyze a new Geot... read more
Average rating:Submit Rating
Financial model that performs a DCF & Relative valuation on Mining Company.

A collection of user-friendly Project Finance Models in the Renewable Energy Sector offered at a dis... read more
Average rating:Submit Rating
Here are all the spreadsheets I've built that involve cash flow distributions between GP/LP. Include... read more
The Call Center Financial Model helps users build a structured financial forecast for launching, man... read more

Average rating:Submit Rating
The toolkit is an essential resource for any organization, providing a comprehensive collection of t... read more

Average rating:Submit Rating
A collection of templates suitable for investment decisions in various types of businesses/industrie... read more

The Liquor Store Financial Model helps entrepreneurs, store owners, consultants, analysts, and busin... read more
The goal of this model is to assist you with starting or buying a coffee farm. The financial spreads... read more
