
0 ITEMS

Canadian BRRRR Financial Model for Canada Real Estate: Buy, Renovate, Rent, Refinance, Repeat, Up to 5 Properties, Max Offer Price, Private Bridge, HELOC, After-Tax IRR
Monthly Excel model of the BRRRR strategy in Canada: buy below value, renovate, rent, refinance and repeat with the cash released. Maximum offer price per deal, OSFI’s 80% refinance cap, seasoning, mortgage penalties, private bridge, holdback and HELOC financing, CCA by property, soft costs, the flipping rule and after-tax investor IRR. Feasibility and Due Diligence editions, no macros, fully unlocked.
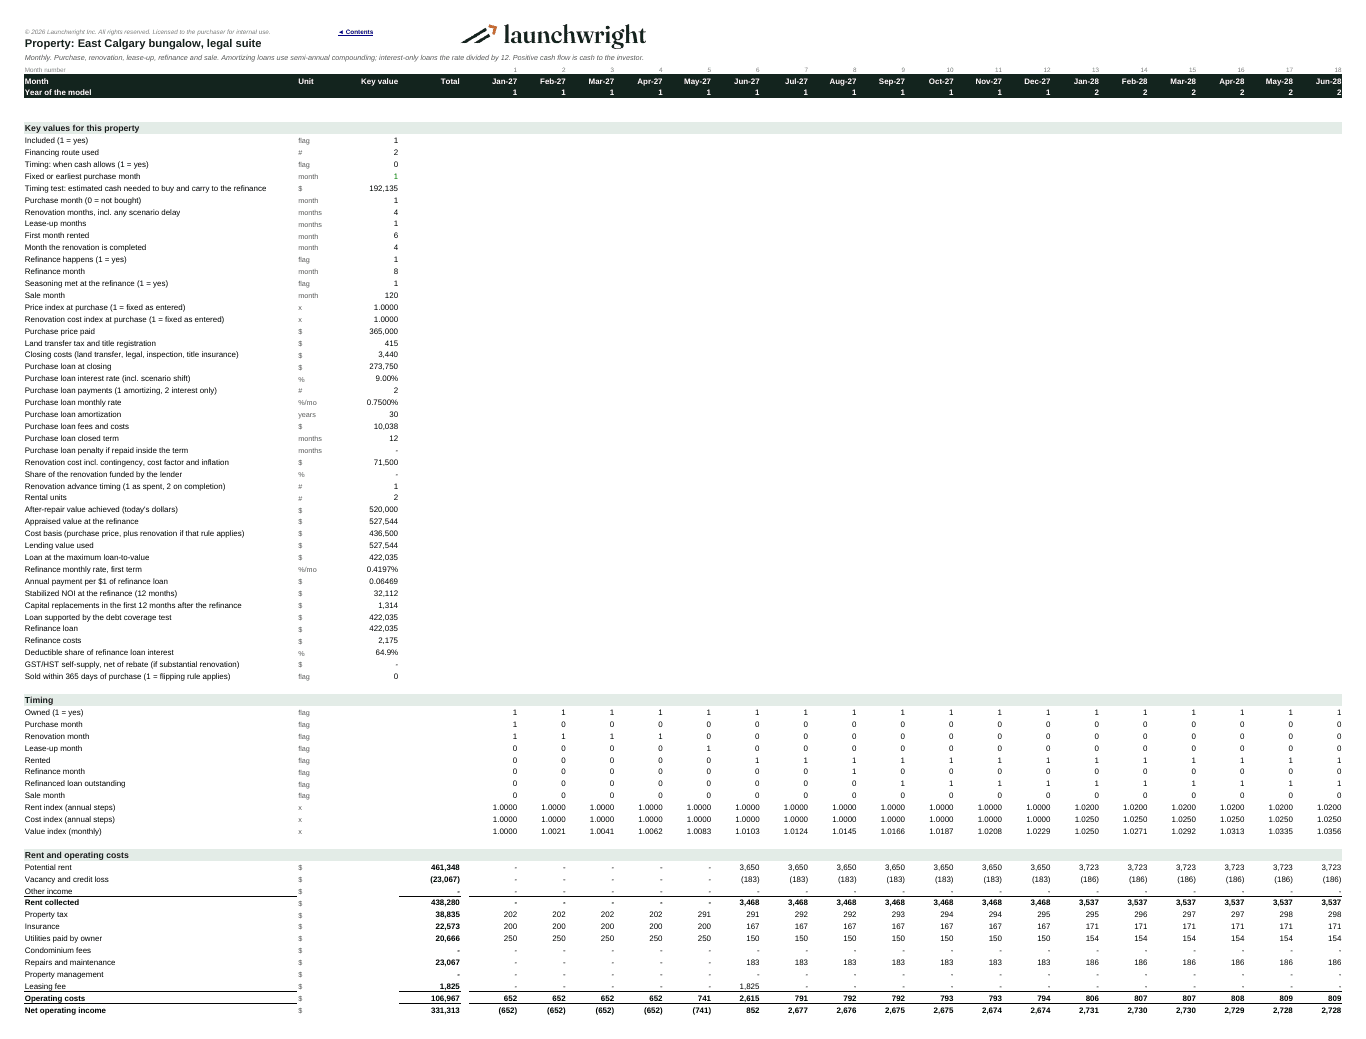
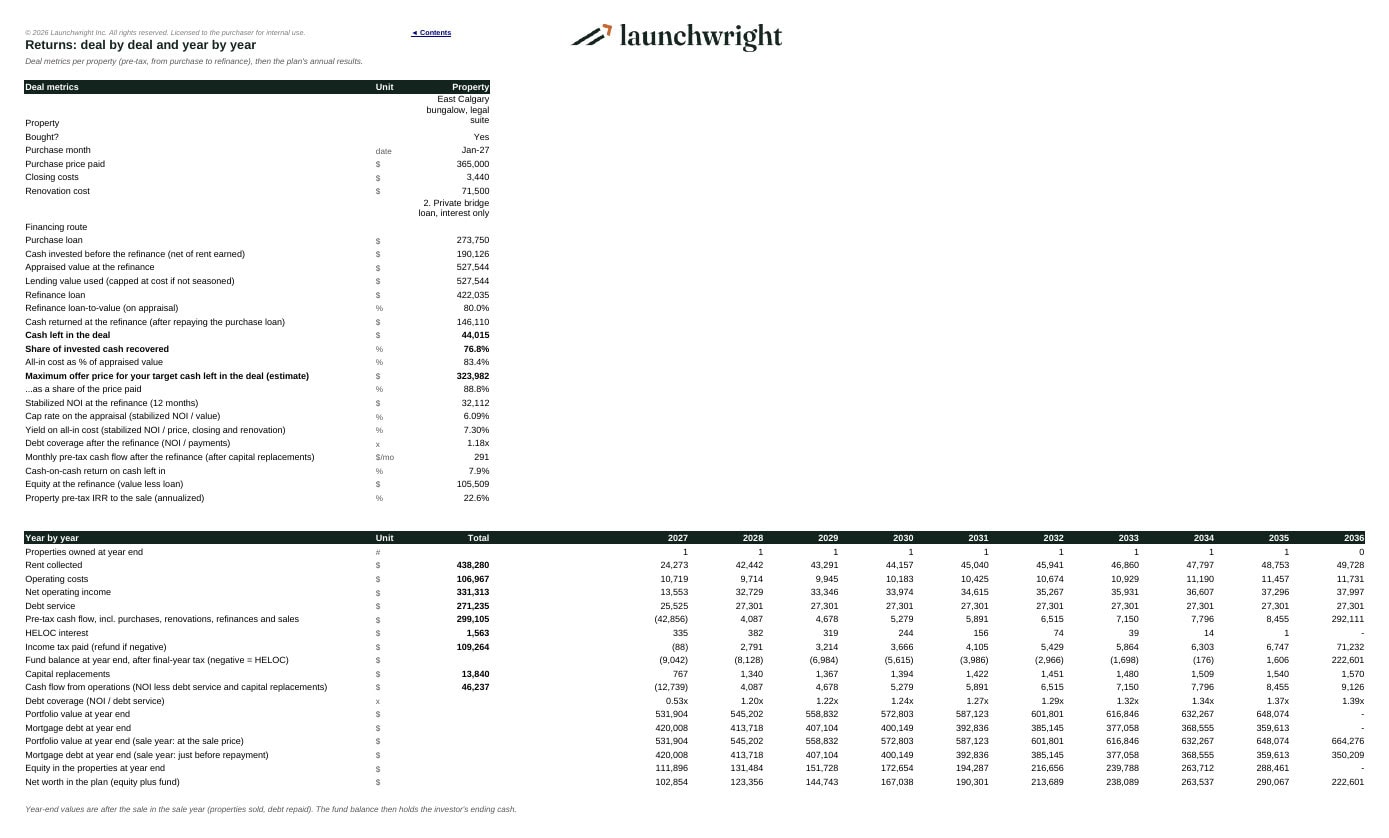
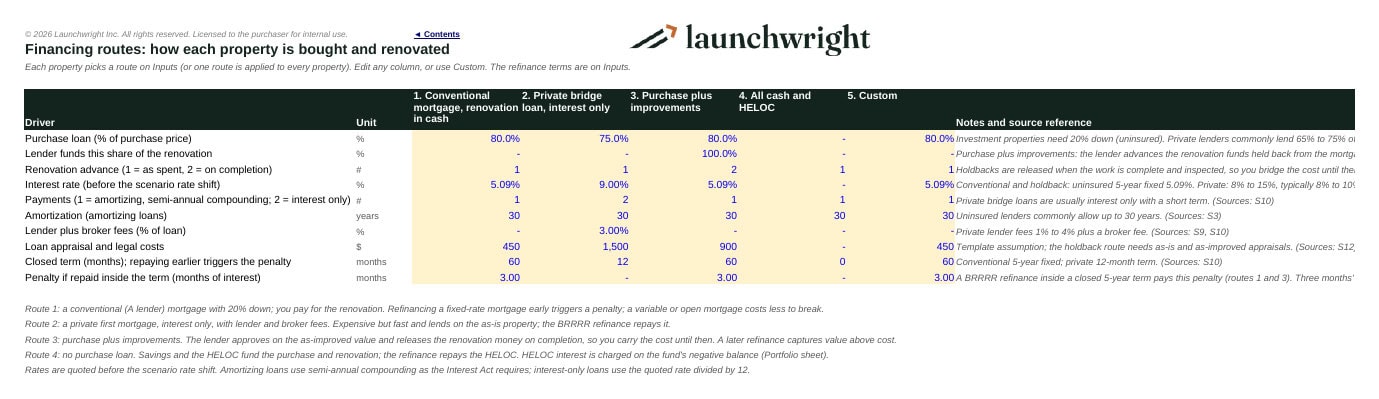
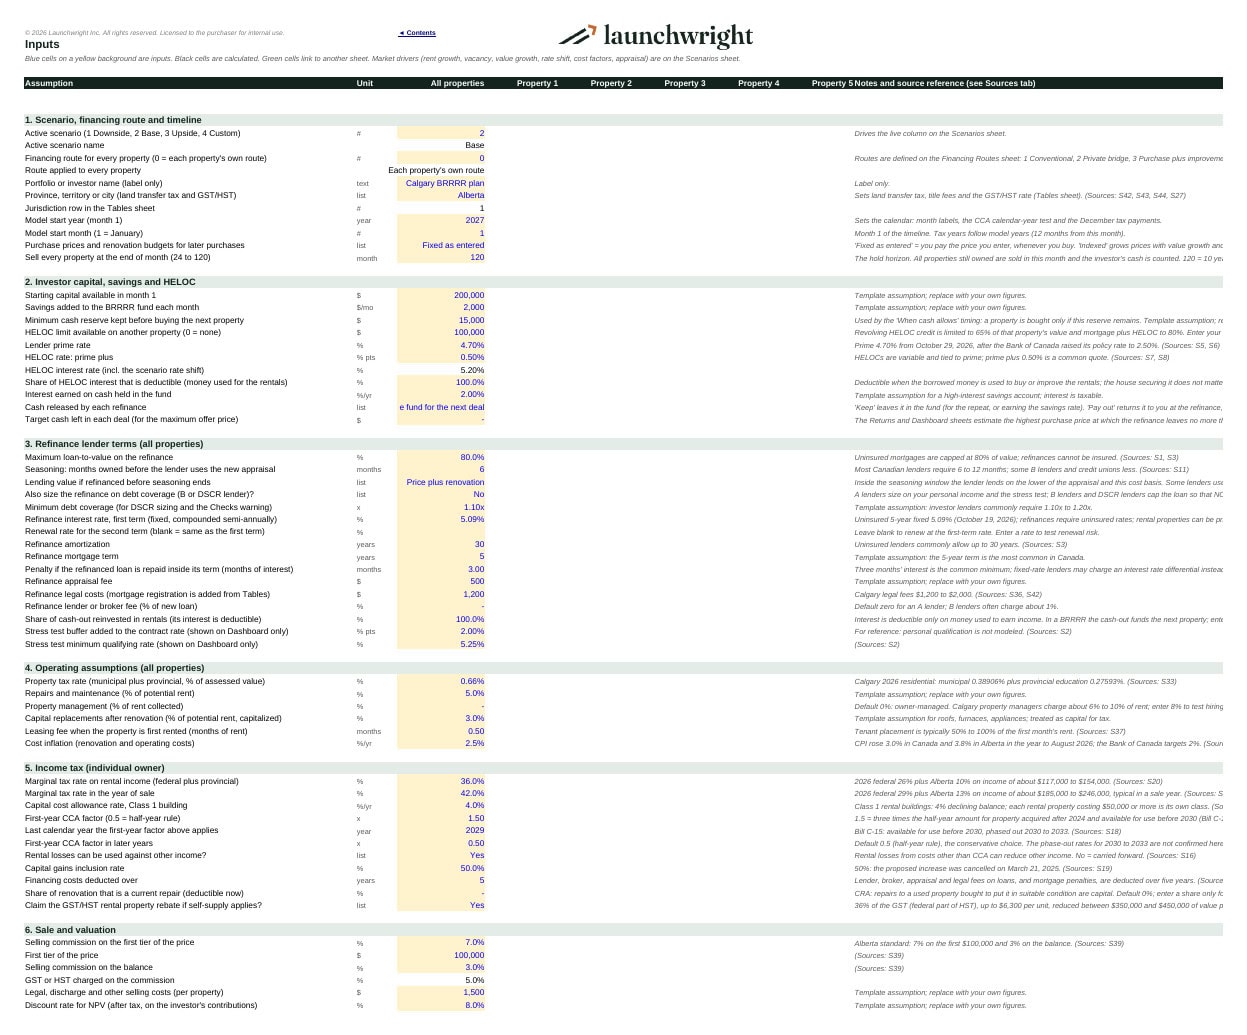
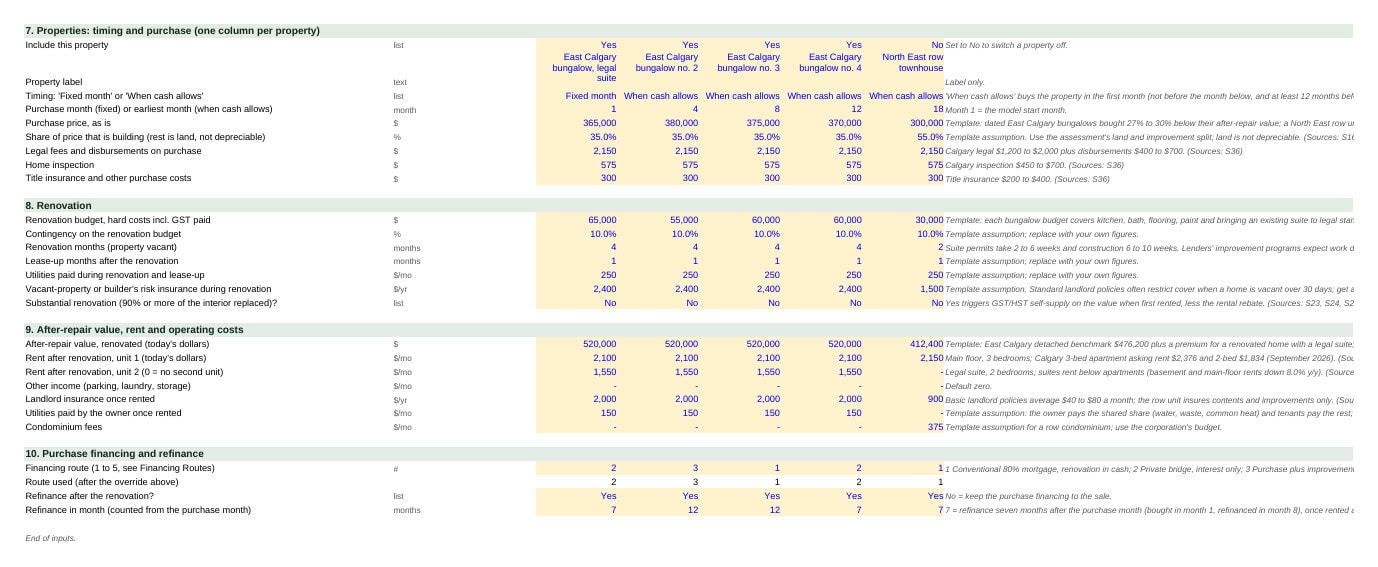
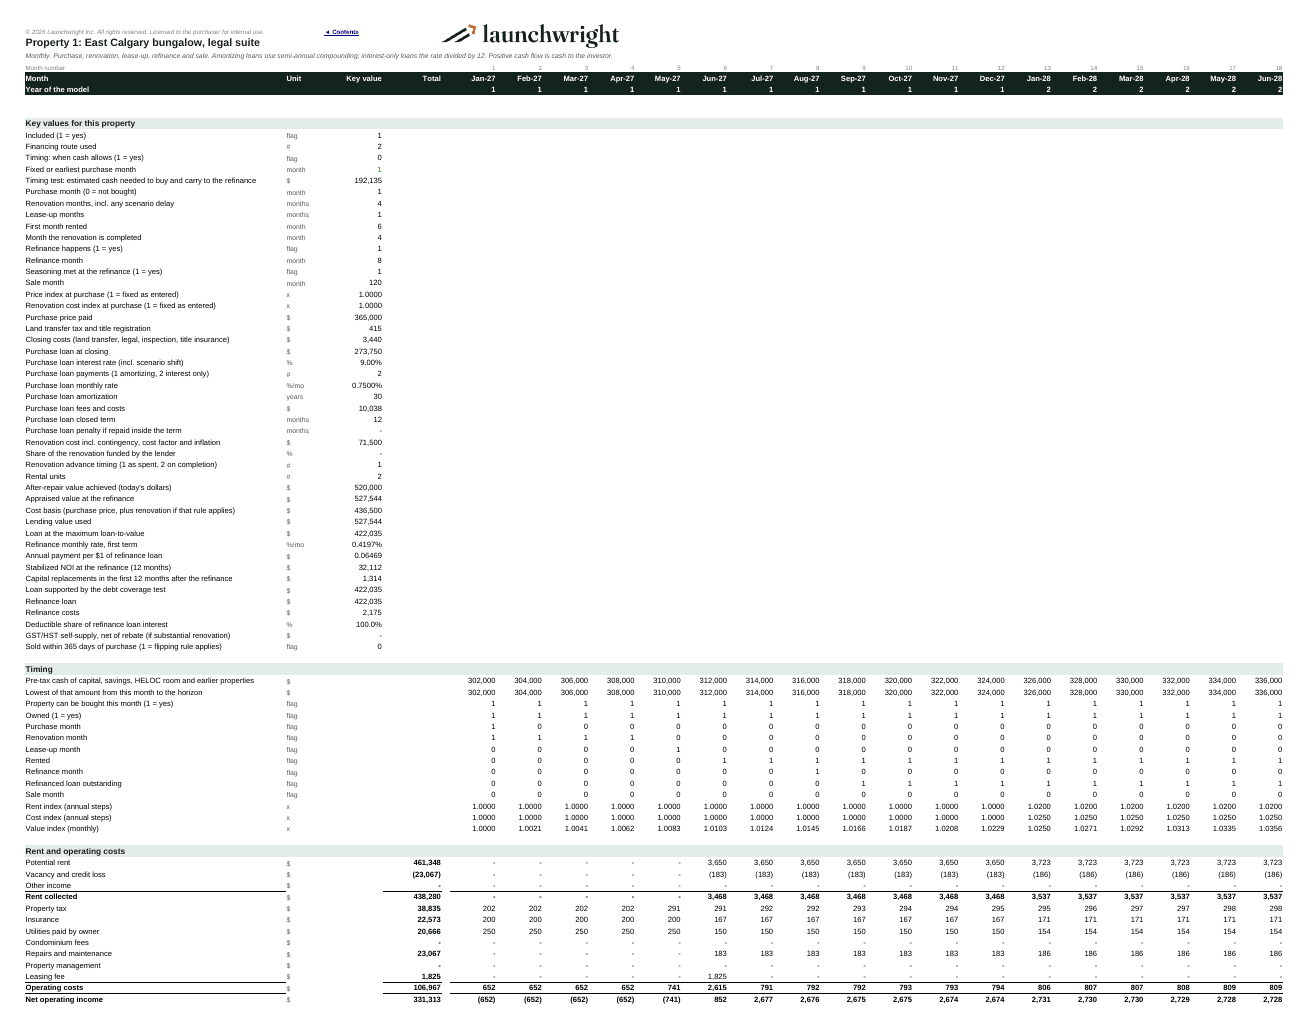
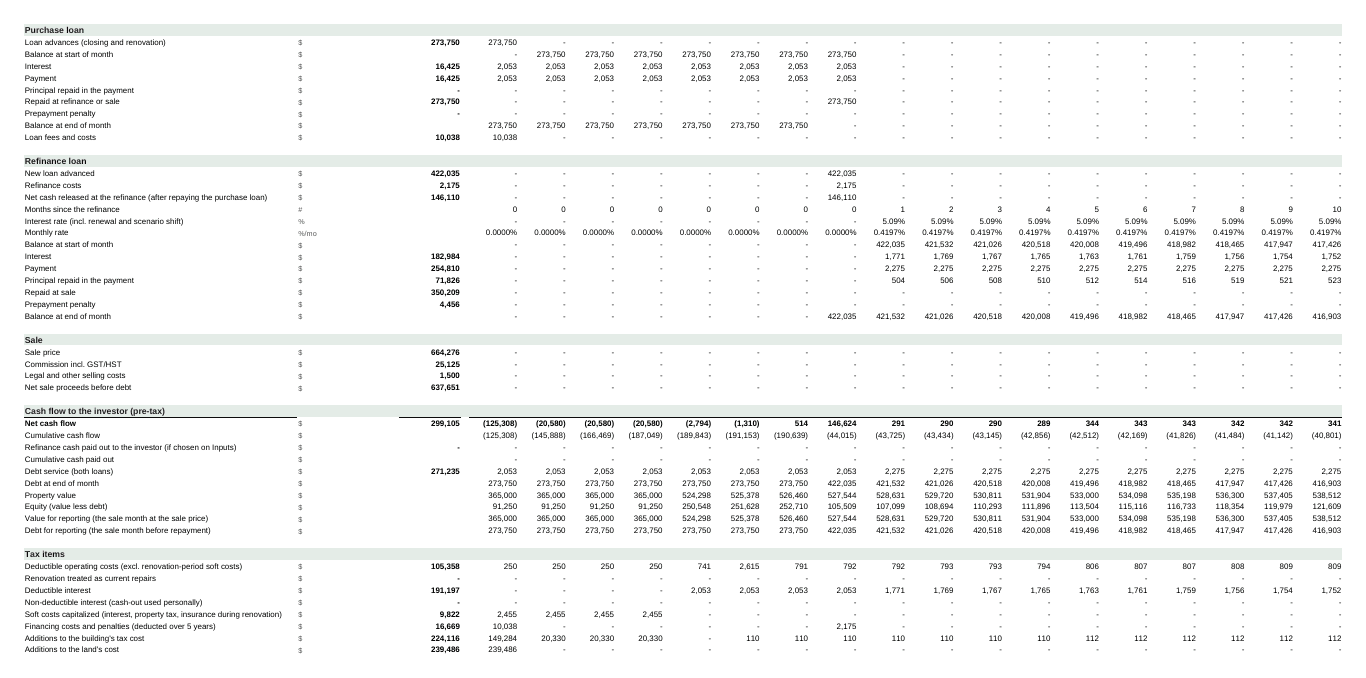
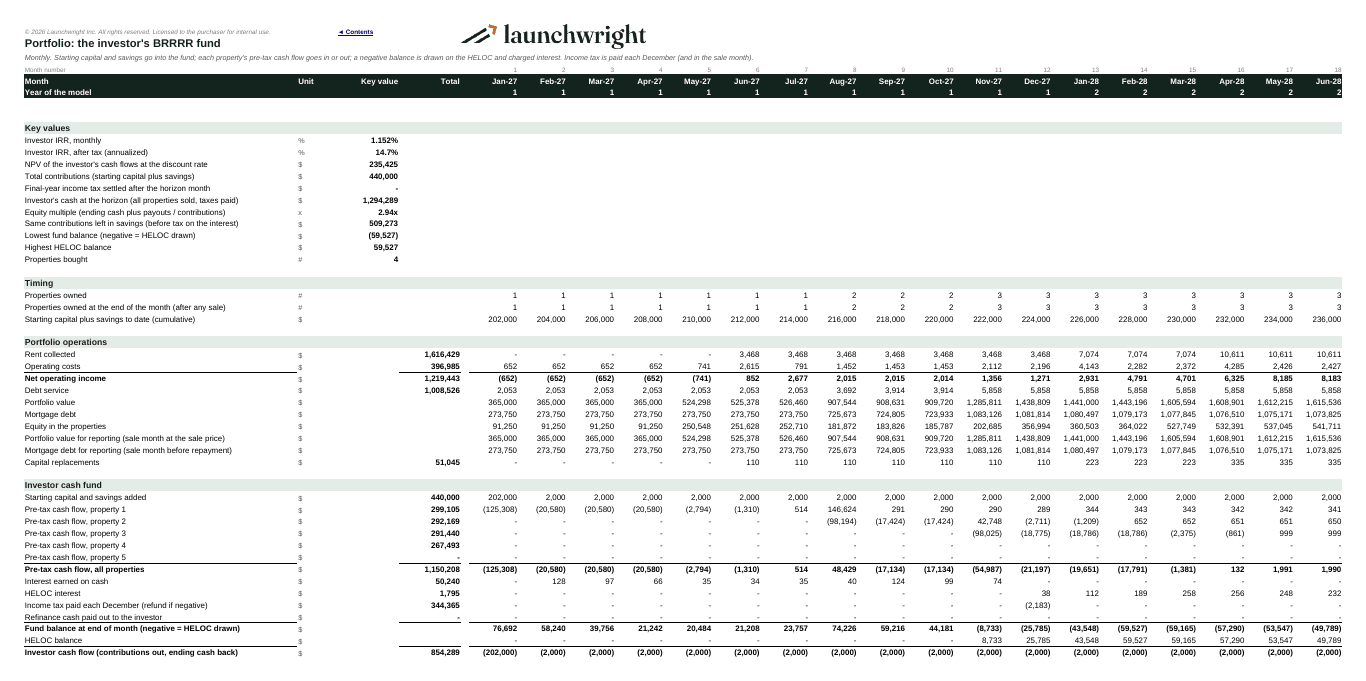
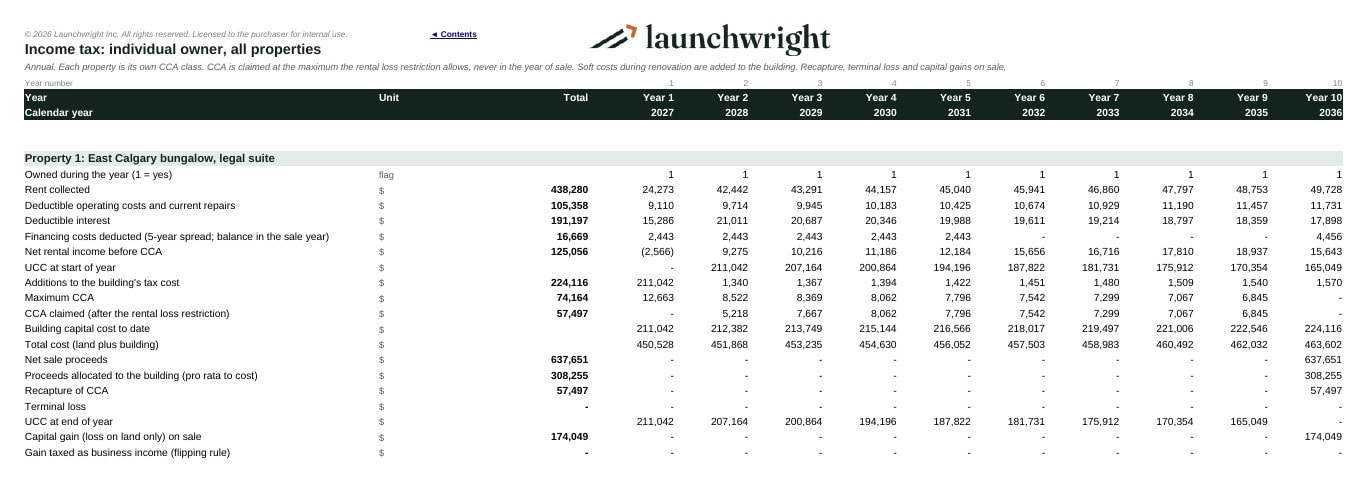
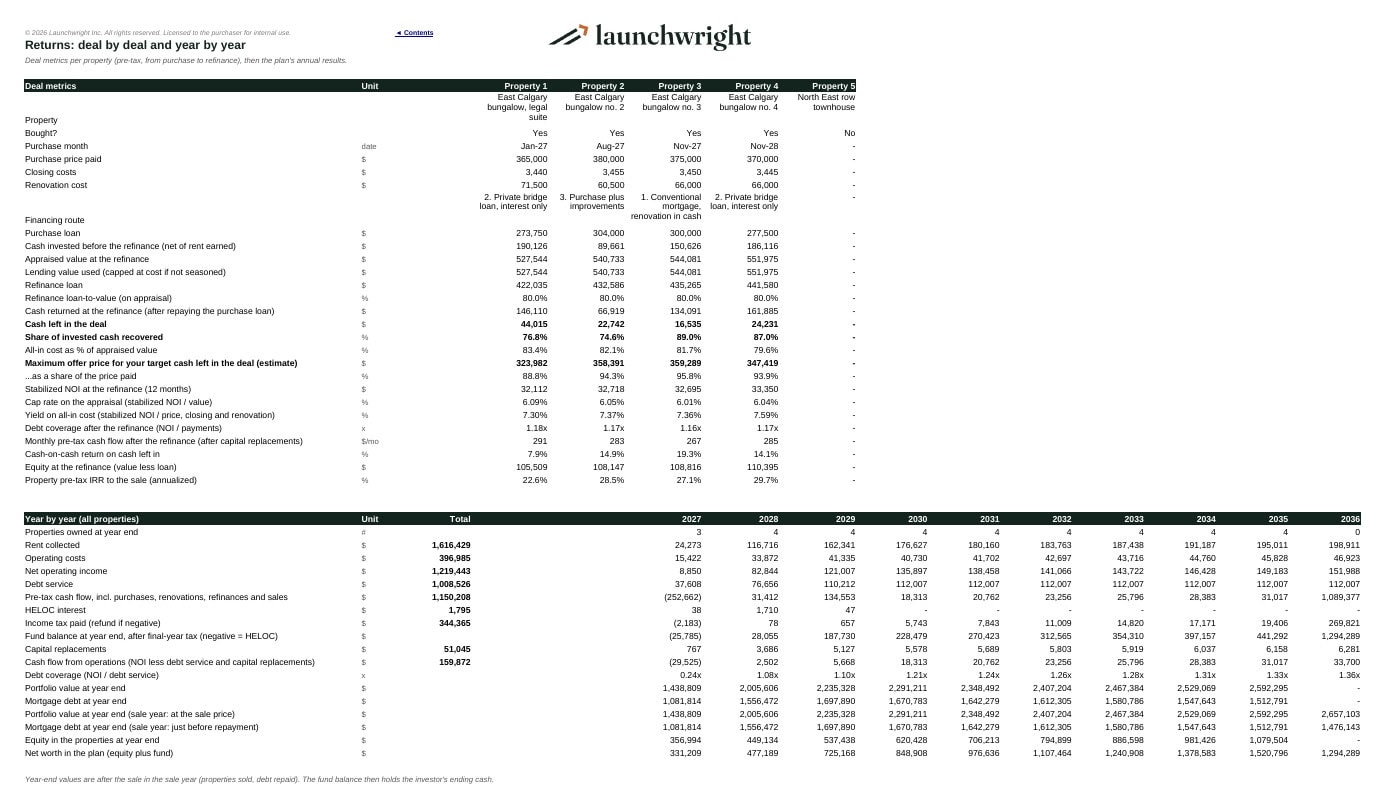
BRRRR works on paper in every American calculator: buy below value, renovate, rent, refinance, pull all your cash out, repeat. In Canada the refinance step runs into rules those calculators ignore. Uninsured loans and every refinance are capped at 80% of value. Most lenders want six to twelve months of seasoning before they lend on the new appraisal. Breaking a fixed mortgage early costs a penalty. HELOCs are capped at 65% of value. The CRA treats renovating a run-down purchase as capital, adds renovation-period interest and property tax to the building, and taxes a sale within 365 days as business income. This Excel model applies those rules month by month and shows how much of your cash actually comes back, and how fast you can repeat.
Why this model
It follows each property through purchase, renovation, lease-up, refinance and hold, and then runs the repeat: in the Due Diligence Edition, up to five properties bought on a fixed month or automatically as soon as your capital, savings, HELOC room and the cash released by earlier refinances can afford the next one. Every default is a published Calgary benchmark or a Canadian rule, cited on a Sources tab, so you can see where each starting value comes from before you replace it.
The number BRRRR investors need: your maximum offer
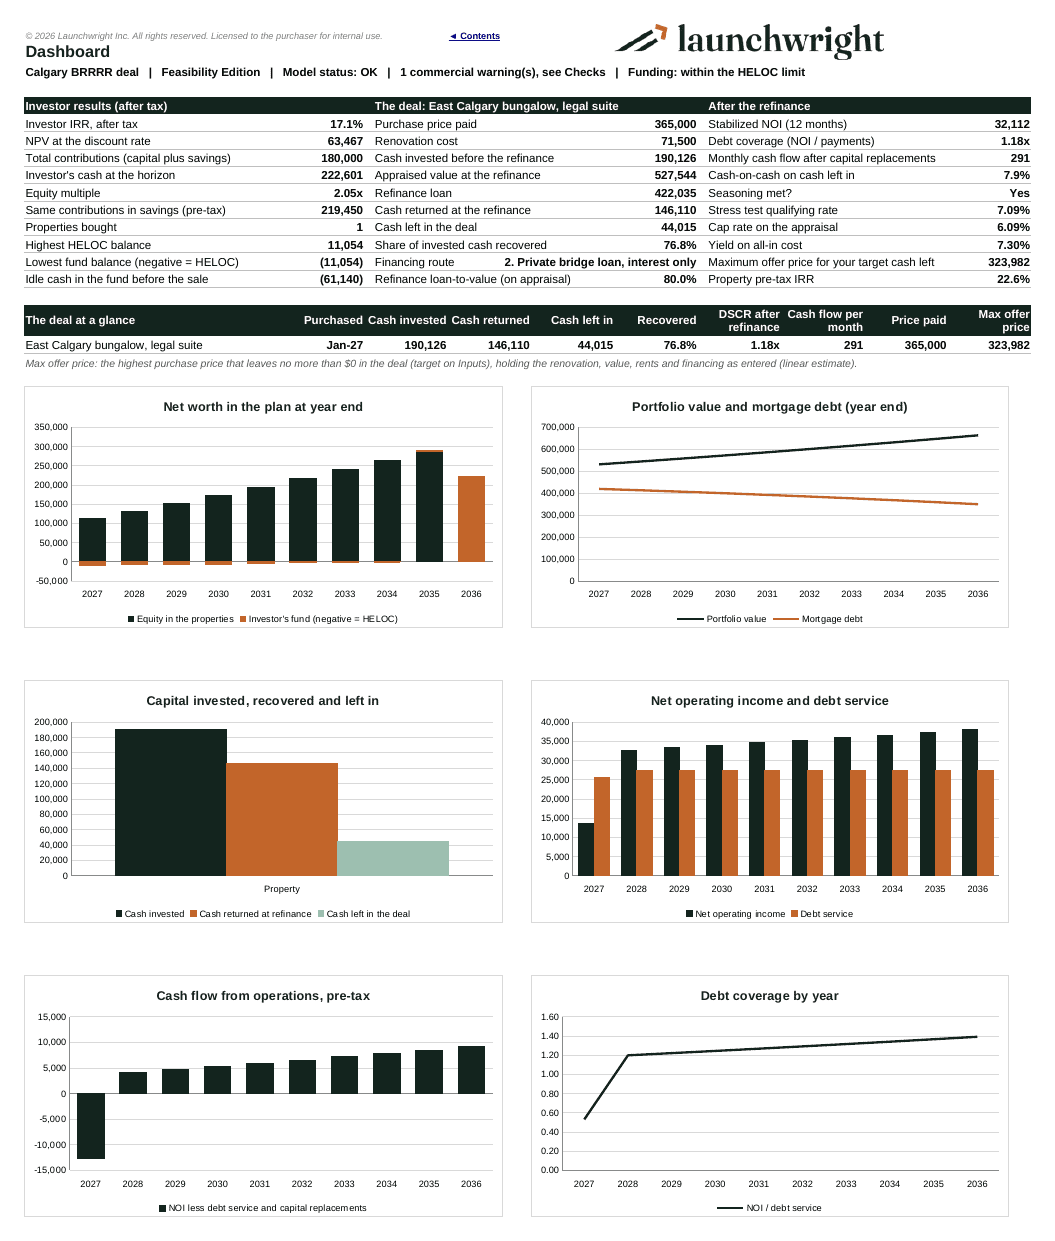
Before you make an offer, the model tells you the highest purchase price at which the refinance leaves no more than your target cash in the deal (all of it back, or a figure you choose), for every property, alongside the cash invested, cash returned, cash left in, share recovered, debt coverage, cap rate and yield on all-in cost.
Canadian rules built in
- Refinance sized at the lower of 80% of the lending value (OSFI’s legal maximum for uninsured loans) and, if you choose, a debt coverage test used by B and DSCR lenders
- Seasoning: refinance before it ends and the lender caps the loan at the lower of the appraisal and your cost, as Canadian lenders do
- Four purchase financing routes, editable: a conventional 20%-down mortgage with the renovation in cash, a private interest-only bridge loan with lender and broker fees, purchase plus improvements with the renovation holdback released on completion, and all cash with a HELOC
- Fixed-rate math with semi-annual compounding as the Interest Act requires, mortgage penalties for breaking a loan inside its term, term renewals and the stress test rate
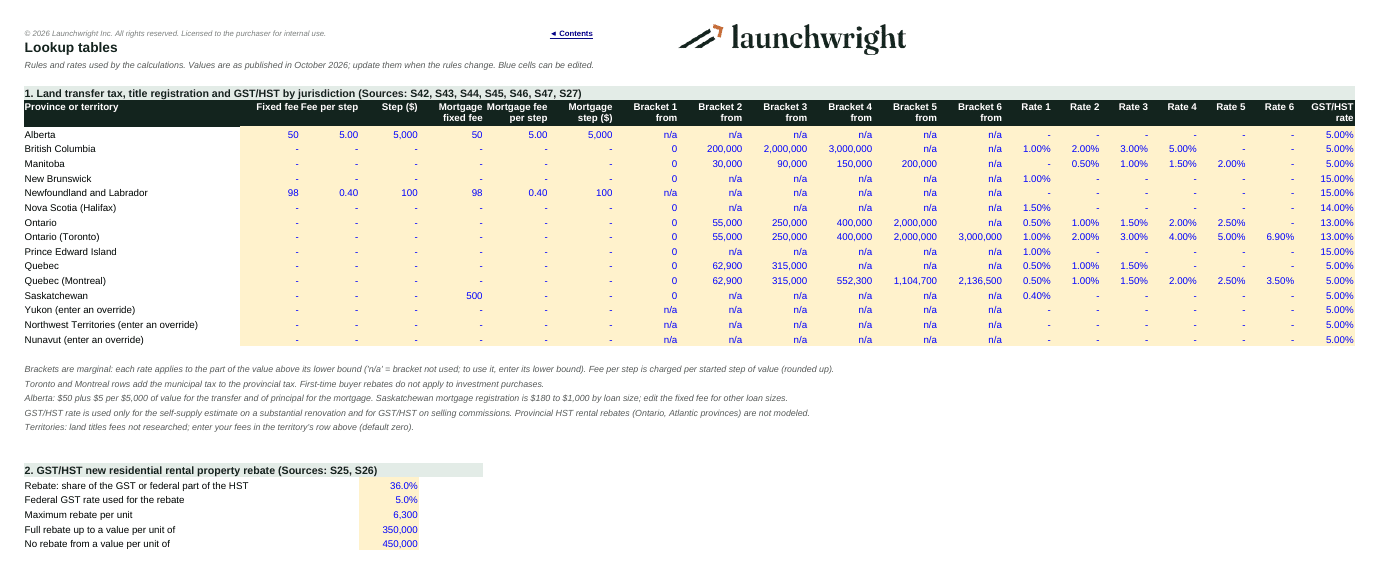
- Land transfer tax and title fees for every province, plus Toronto and Montreal
- After tax for an individual owner: each property in its own CCA class with the first-year enhancement, renovation capitalized, soft costs during renovation added to the building, financing fees over five years, interest on cash-out deductible only for the share reinvested in rentals, the rental loss restriction across the portfolio, recapture, terminal loss, capital gains at 50% and the residential property flipping rule
- GST/HST self-supply estimate if a renovation is substantial (90% test), net of the 36% new residential rental property rebate
Two editions
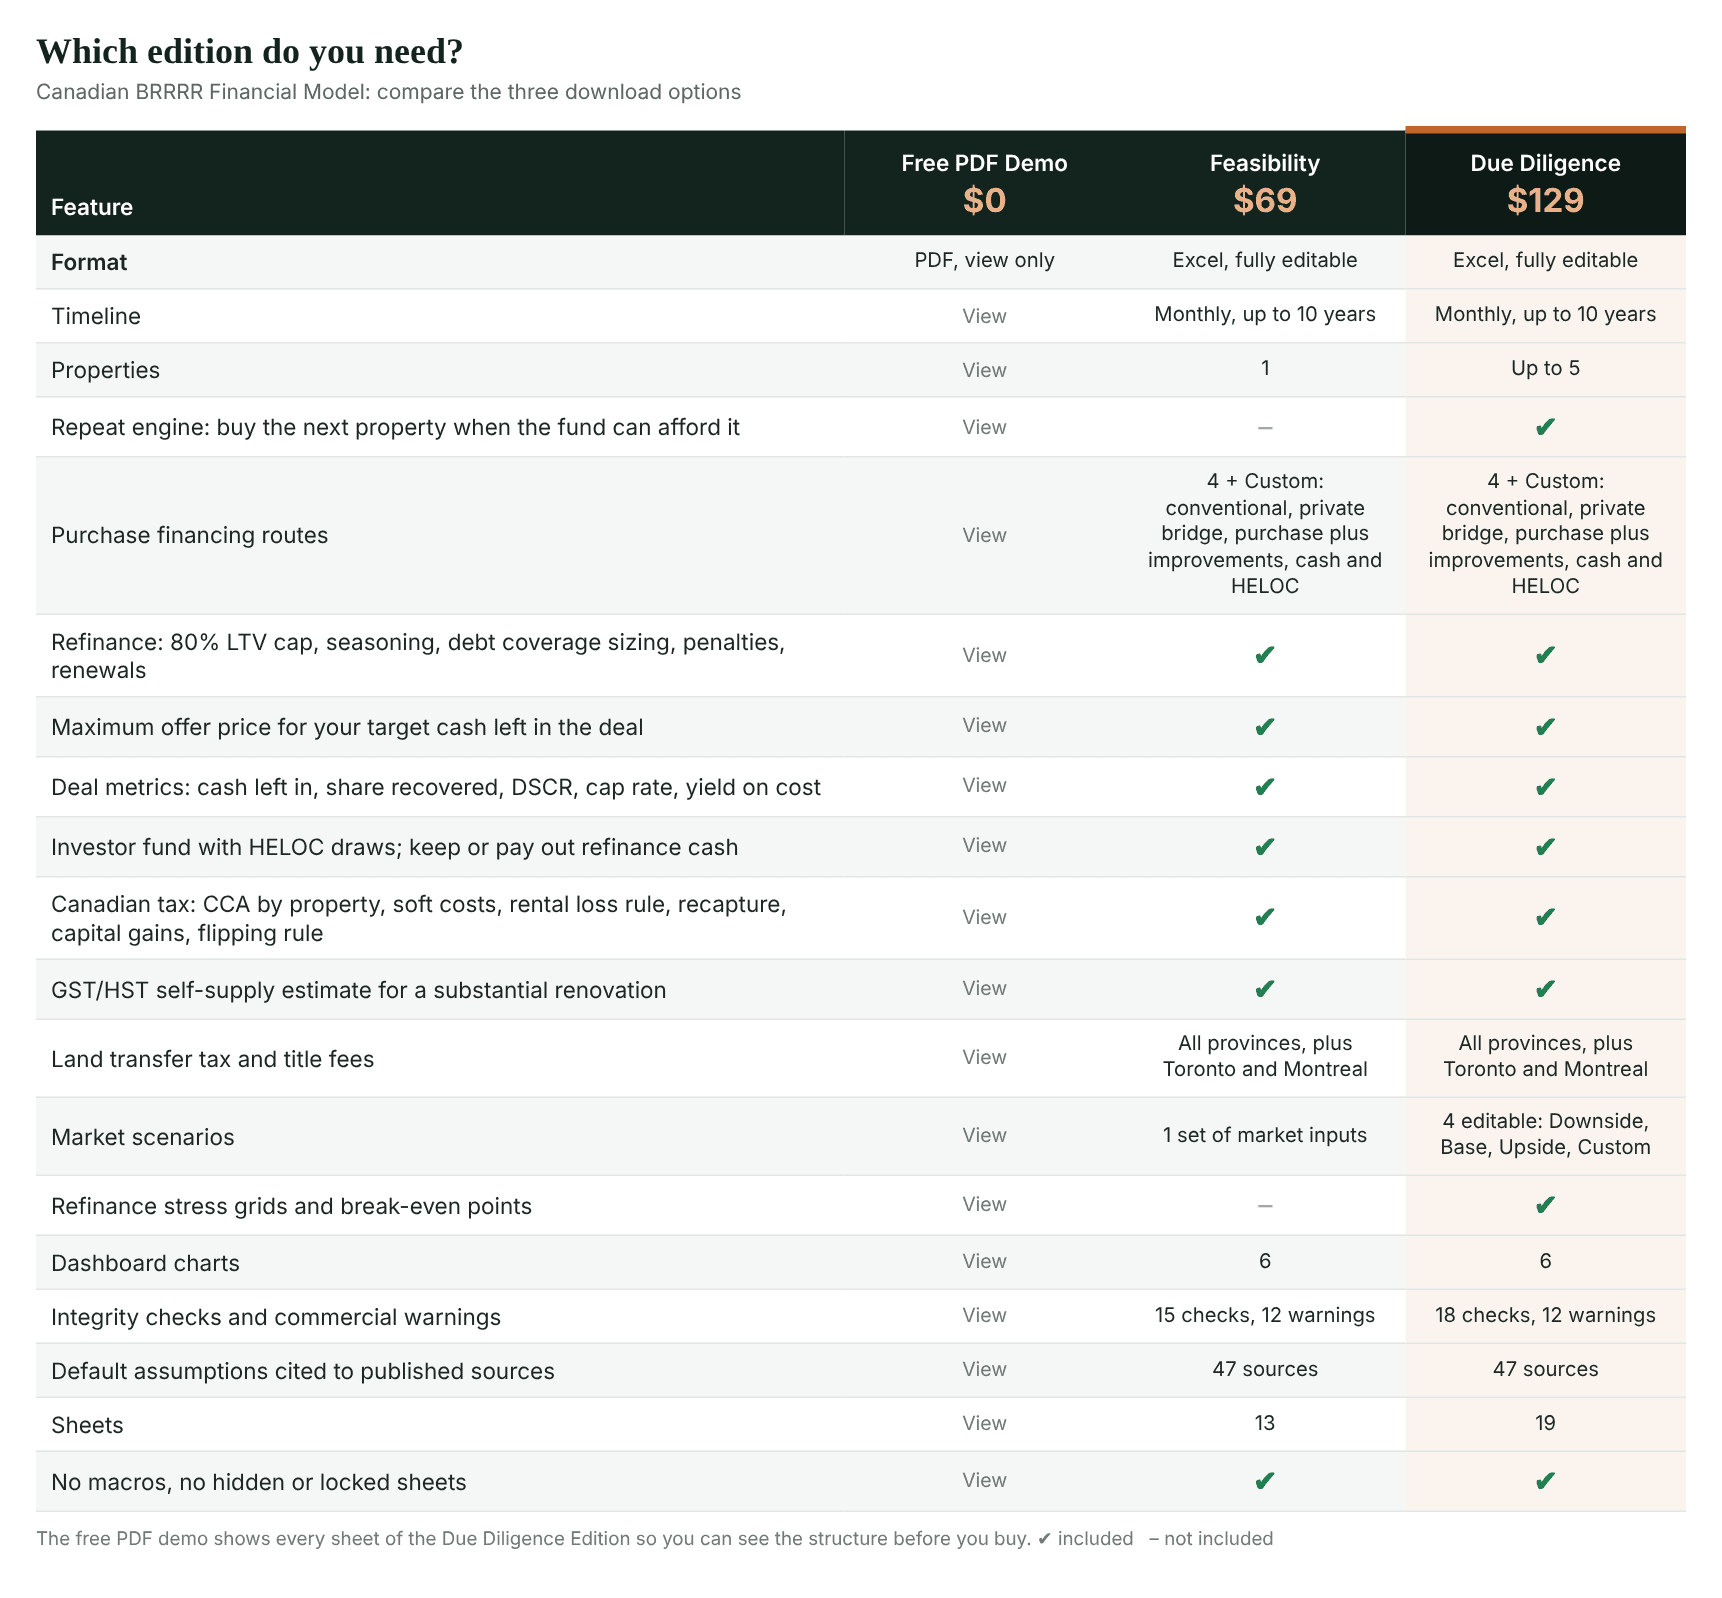
- Feasibility Edition: one property, monthly for up to 10 years, the four financing routes, the refinance with seasoning and penalties, the full Canadian tax logic, the investor’s cash and HELOC, the maximum offer price and deal metrics (cash left in the deal, share recovered, debt coverage, cash-on-cash, cap rate, yield on cost), after-tax IRR, a dashboard and integrity checks.
- Due Diligence Edition: everything in the Feasibility Edition, plus:
- the repeat engine for up to five properties, each with its own route, timing and refinance
- ‘When cash allows’ timing that buys the next property in the first month the fund can carry it through its refinance
- a portfolio fund with HELOC draws, interest and tax paid from it, the choice to keep each refinance’s cash for the next deal or pay it out, and year-by-year portfolio value, debt, equity and net worth
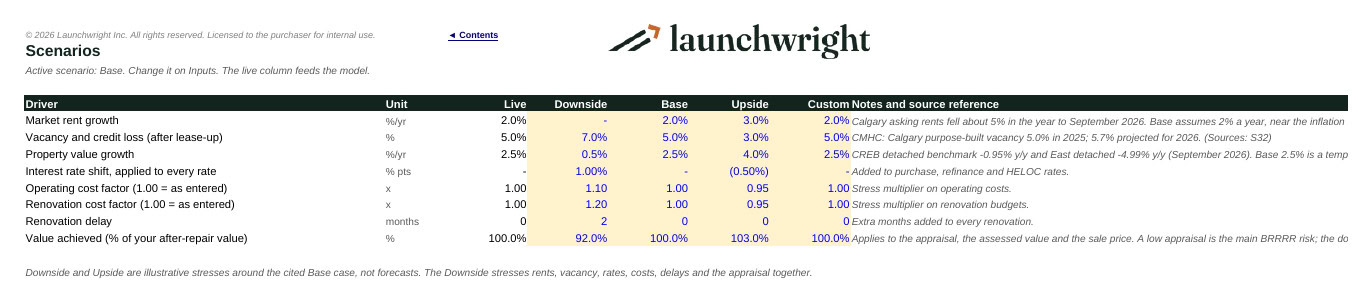
- four editable market scenarios: rent growth, vacancy, value growth, rate shift, cost factors, renovation delay and a low appraisal
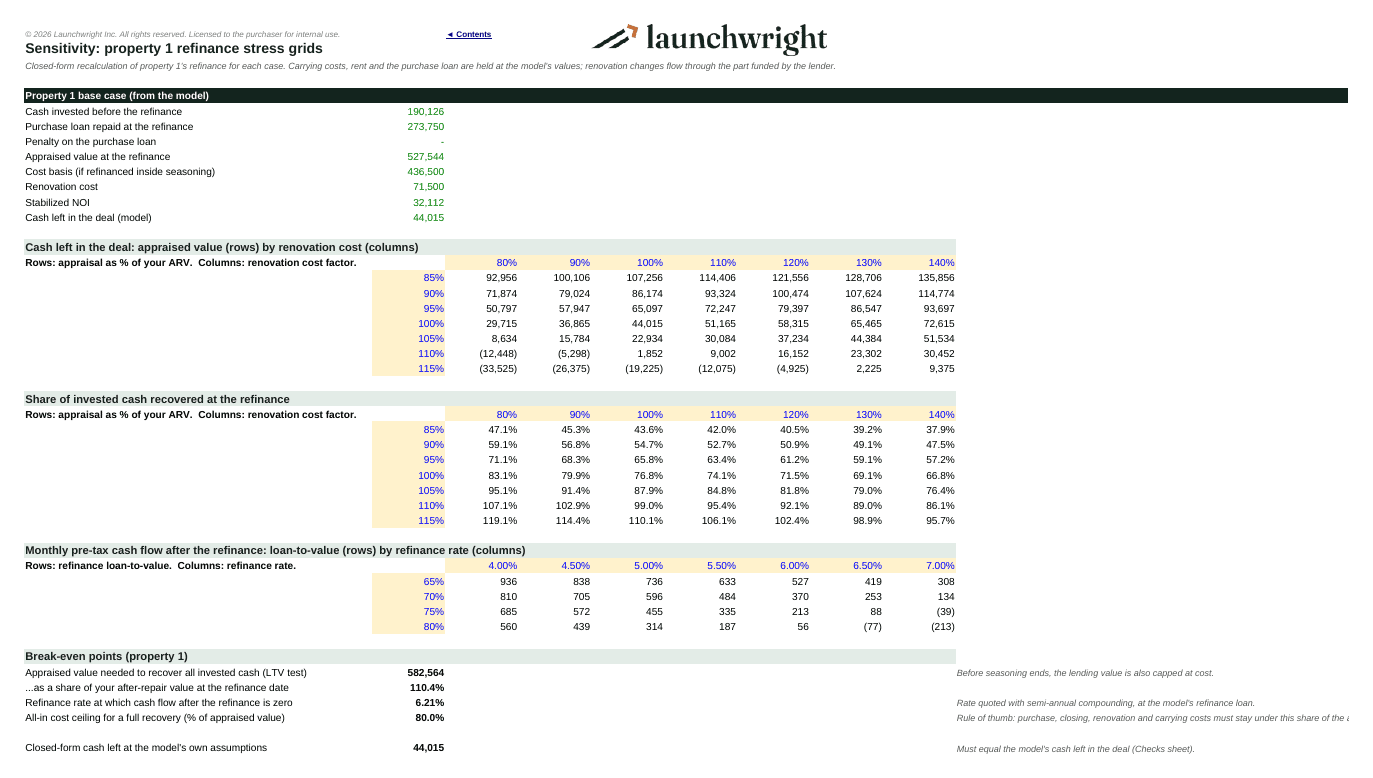
- refinance stress grids: cash left in the deal and share recovered by appraisal and renovation overrun, and cash flow by refinance rate and loan-to-value
- break-even appraisal, break-even refinance rate and the all-in cost ceiling for a full recovery
Key outputs
- Per property: maximum offer price, cash invested before the refinance, cash returned, cash left in the deal, share recovered, all-in cost as a share of value, stabilized NOI, cap rate, yield on all-in cost, debt coverage, monthly cash flow after the refinance and pre-tax IRR
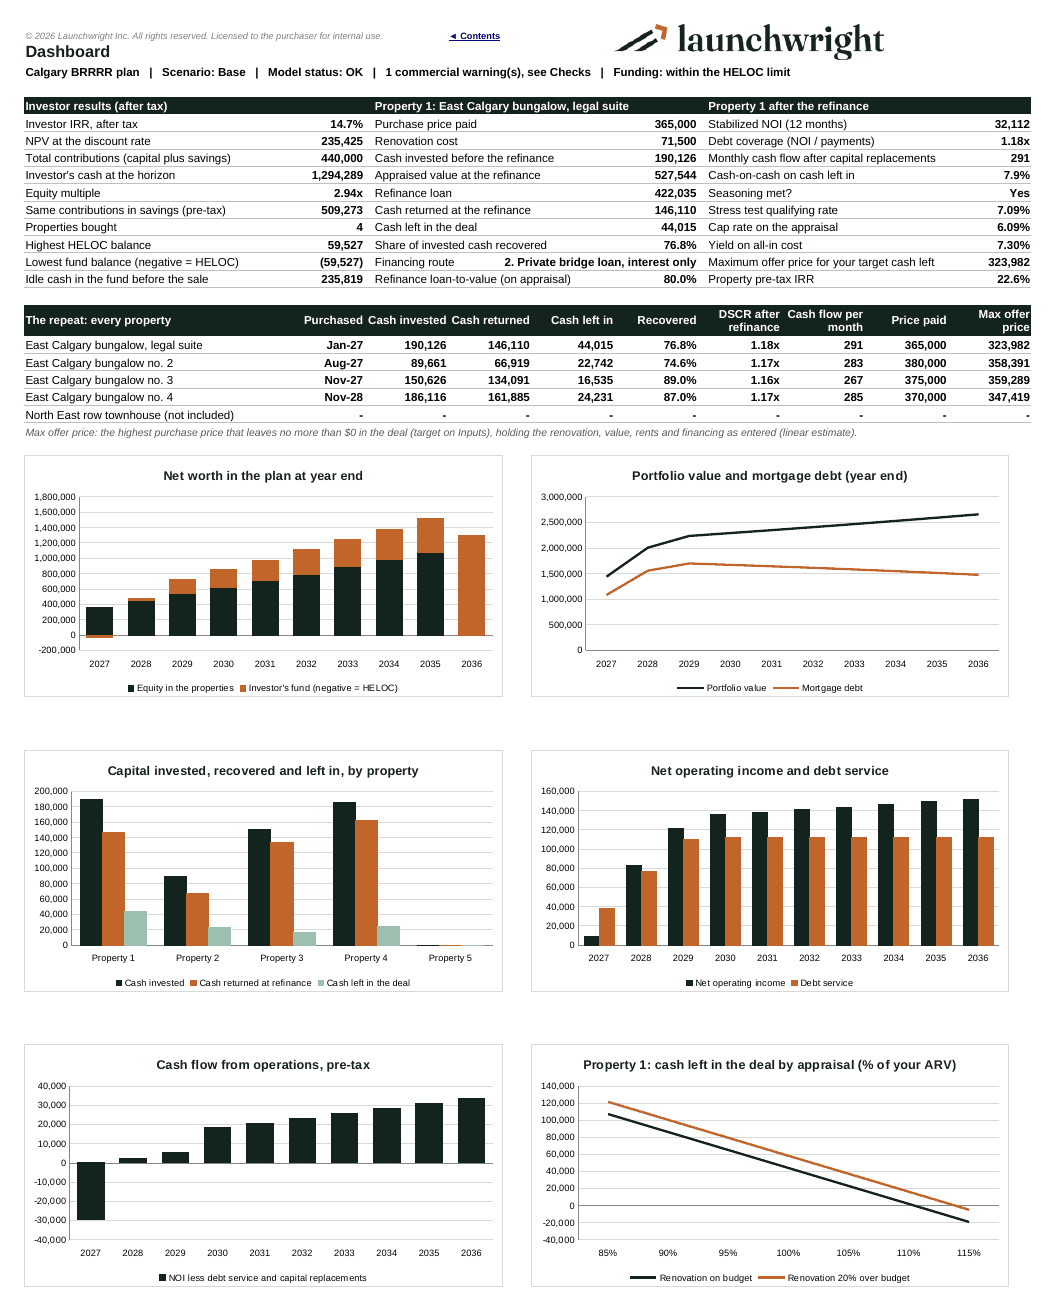
- For the investor: after-tax IRR, NPV, equity multiple, ending cash against leaving the same money in savings, the lowest fund balance and the highest HELOC draw
- Dashboard charts (year end): net worth split between property equity and the fund, portfolio value against mortgage debt, capital invested, recovered and left in by property, NOI against debt service, cash flow from operations, and (Due Diligence) cash left in the deal against the appraisal
Built to modeling best practice
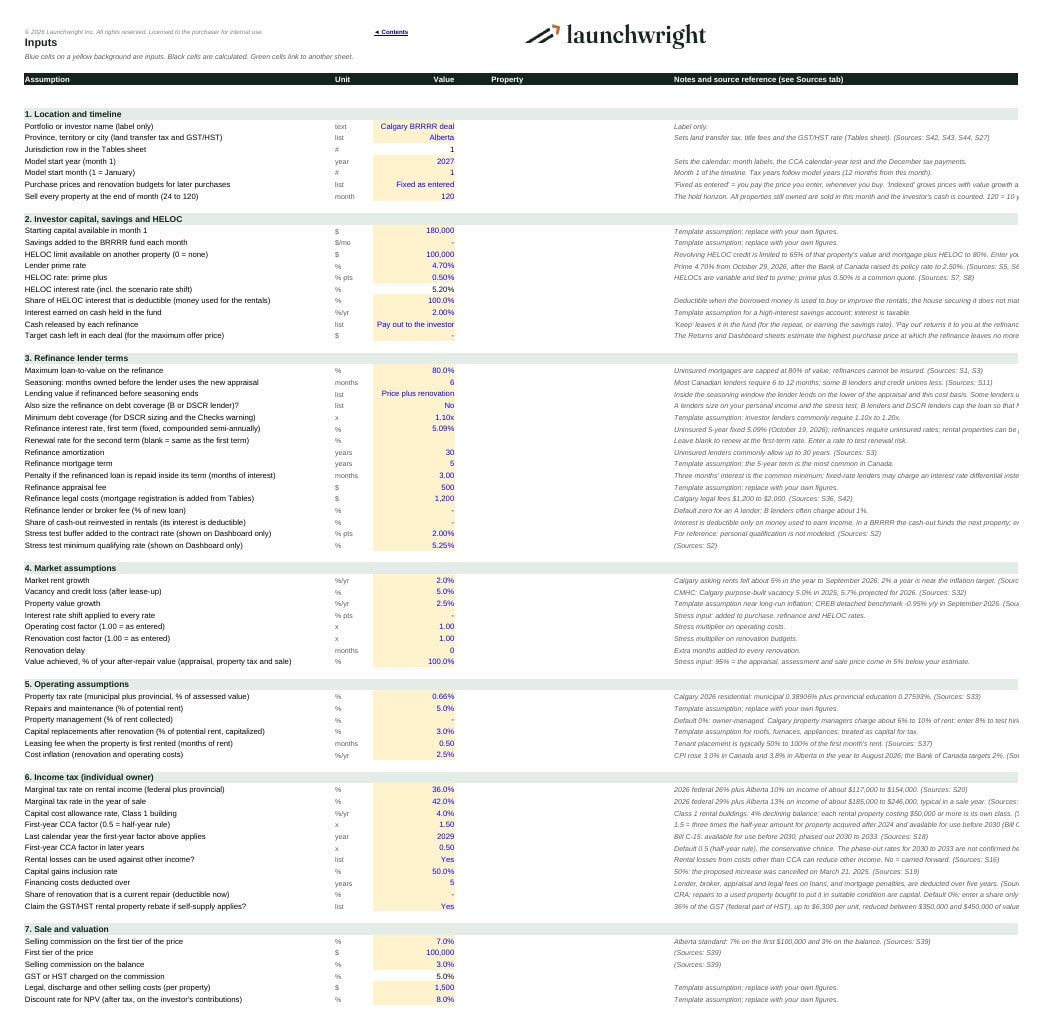
- Inputs, calculations and outputs on separate sheets; color-coded inputs (blue on yellow), formulas (black) and cross-sheet links (green)
- One formula per row across all 120 months; no macros, no circular references, no hidden or protected sheets, no external links
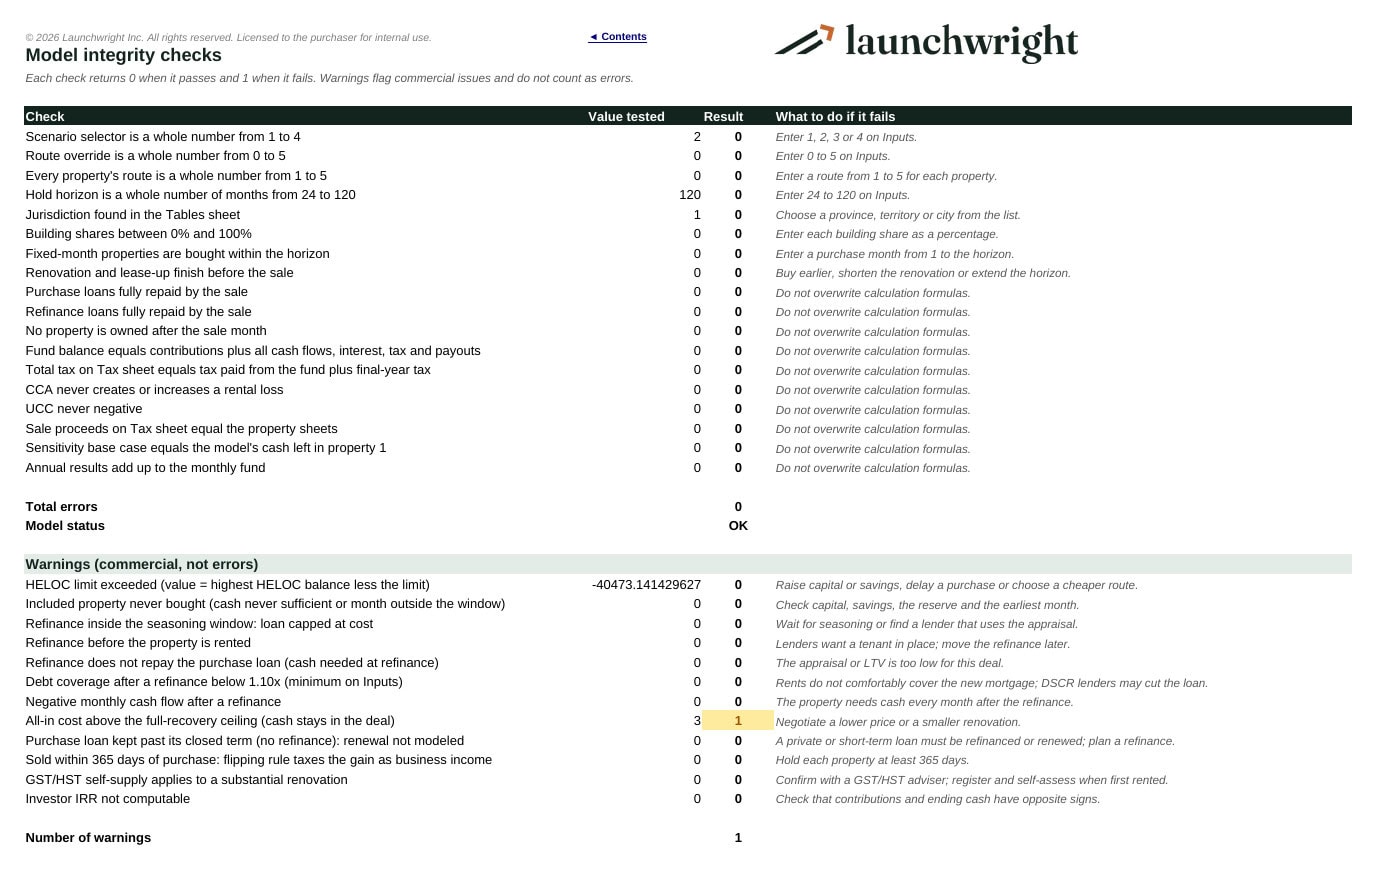
- Checks sheet confirms the loans are repaid, the fund reconciles to every cash flow, tax paid matches the tax calculated, CCA never creates a rental loss and the sensitivity agrees with the model, and warns on HELOC overdraw, refinancing inside seasoning or before rent starts, a refinance that does not repay the purchase loan, weak debt coverage, cash left in deals and the flipping rule; the Dashboard shows the status, the number of warnings and whether the plan is fundable
- Contents sheet with links, step-by-step instructions, a glossary and a full source list
Default assumptions
Defaults describe dated East Calgary bungalows with a legal suite, bought for $365,000 to $380,000 and worth $520,000 renovated (the East district detached benchmark was $476,200 in September 2026), with $55,000 to $65,000 renovations, rents from the September 2026 Rentals.ca report, Calgary’s 2026 property tax rate, owner management, the uninsured 5-year fixed rate of 5.09% and prime at 4.70% after the Bank of Canada’s October 28 increase. Starting with $200,000 and saving $2,000 a month, the Due Diligence plan buys four properties by November 2028, using a private bridge loan, purchase plus improvements and a conventional mortgage. Each refinance at 80% of value recovers 75% to 89% of the cash invested, leaving $16,535 to $44,015 in each deal, and each property then earns about $267 to $291 a month after capital replacements (debt coverage 1.16x to 1.18x). The plan earns an after-tax IRR of 14.7% over ten years, including the sale of all properties in year 10. The single-property Feasibility Edition pays the refinance cash out to the investor and earns 17.1% after tax. The Downside scenario (lower appraisal, cost overruns, delays, higher rates) shows how quickly the repeat stalls. Replace the defaults with your own purchase, quotes, appraisal and lender terms.
Compare the editions
The free PDF demo, the Feasibility Edition ($69) and the Due Diligence Edition ($129) side by side:
What you get
- One Excel workbook (.xlsx) for the edition purchased, built only with functions available since Excel 2010 (no dynamic arrays, no macros)
- A free PDF demo showing the main sheets of the Due Diligence Edition
Support and customization
Questions about how the template works are answered by email. Launchwright can also adapt the model to your deal, lender or portfolio, quoted at a fixed price in writing before work begins. Contact details are inside the model.
Important
This template is for planning and illustration. Lenders decide appraisals, seasoning and loan amounts on each application, and tax rules change; the rules in this version are as published in October 2026. It is not investment, tax, legal or mortgage advice. Confirm them with your lender, accountant and a GST/HST adviser.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.