
0 ITEMS

How Contribution Margin Analysis Can Drive Your Business to Financial Success
Understanding contribution margin is essential for analyzing business profitability and making strategic decisions.
- Contribution margin shows the amount remaining from sales after variable costs are deducted, helping to cover fixed costs and generate profit.
- It can be calculated per unit or as a ratio, aiding in pricing and resource allocation strategies.
- Analyzing contribution margin helps identify which products or services are most profitable.
- Using contribution margin data supports effective cost management, forecasting, and pricing strategies.
Continue reading to see how these insights can directly impact your business growth.
What is the Contribution Margin?
Contribution margin is a crucial financial metric used in cost accounting and financial analysis to evaluate the profitability of a product, product line, or service. It represents the dollar amount or percentage a product contributes to covering fixed costs and generating profit. Essentially, it indicates how much revenue from each product sale is available to cover variable costs and contribute to covering fixed costs and profit.
A positive contribution margin indicates that the product or service generates enough revenue to cover its variable costs and contribute towards the business’s fixed costs and overall profitability. On the other hand, a negative contribution margin suggests that the product or service may not be generating enough revenue to cover its variable costs, posing a potential risk to your business’s financial success.
Contribution Margin as a Key Component of Break-Even Point
Contribution margin is a critical component of the break-even point analysis in business. It represents the amount of money a company has left over from sales revenue after covering its variable costs. In other words, the portion of each sale contributes toward covering fixed costs and generating profit.
To calculate the break-even point, you need to know the contribution margin per unit. Once you have the contribution margin per unit, you can determine the break-even point by dividing the total fixed costs by the contribution margin per unit.
This calculation helps a business understand how many units of a product or service it needs to sell to cover its fixed costs (such as rent, salaries, and utilities) and begin generating profit. Once the company sells enough units to cover these fixed costs, any additional sales contribute directly to gain, making the break-even point a crucial metric for financial planning and decision-making.





























Differences Between Contribution Margin and Gross Margin
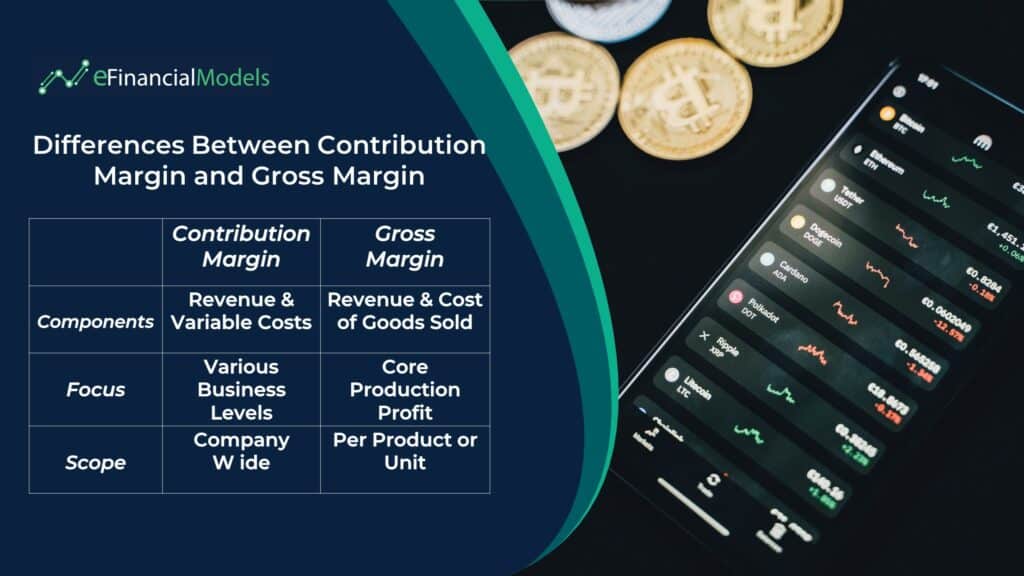
Contribution margin and gross margin are both financial metrics businesses use to analyze and manage their profitability. However, they serve slightly different purposes and focus on different aspects of a company’s financial performance.
- Gross margin is primarily concerned with the profitability of core production operations. It calculates the difference between a company’s revenue and cost of goods sold (COGS). On the other hand, contribution margin considers variable costs associated with production and selling, offering a more comprehensive view of profitability at various levels within a business.
- Gross margin considers only the direct costs associated with producing or purchasing the goods that a company sells. These costs only include materials, labor, and manufacturing costs. Contribution margin considers the variable costs related to production and variable selling and marketing expenses. It provides a clearer picture of the contribution of each unit of product or service toward covering both variable and fixed costs.
- Analyzing gross margin on a per-unit basis could be more challenging. That is why businesses typically examine gross margin company-wide. In contrast, contribution margin is frequently easier to obtain and apply on a per-unit or per-product basis. Knowing how much earnings from each unit may be utilized to pay fixed costs will be of greater interest to a corporation because it will directly affect which product lines are maintained.
In summary, while both contribution margin and gross margin are valuable metrics for assessing profitability, they have different focuses and provide distinct insights.
How to Calculate Contribution Margin?
The contribution margin represents the portion of revenue that covers variable costs and contributes to covering fixed costs and generating a profit. The basic formula for how to calculate the contribution margin is as follows:
Contribution Margin = Sales Revenue – Variable Costs
Where:
Sales Revenue = The total revenue generated from selling a product or service.
Variable Costs = Costs that vary directly with the level of production or sales. Variable costs typically include the following expenses:
- Raw Materials
- Production Supplies
- Per Unit Labor
- Billable Wages
- Commissions
- Shipping or Transportation Expenses
- Variable Utilities like Electricity, Rent, and Water
Contribution Margin Ratio Calculation
Most businesses calculate the contribution margin in percentages. It is called the contribution margin ratio calculation. The formula for contribution margin ratio calculation is as follows:
Contribution Margin Ratio (CMR) = [(Sales Revenue – Variable Costs) / Sales Revenue] * 100
The contribution margin ratio calculation expresses the proportion of a company’s sales revenue available to cover its fixed costs and contribute to profits. It is helpful for businesses because it helps them assess how much each unit sold contributes toward covering fixed costs (like rent, salaries, utilities) and generating profits.
A higher contribution margin ratio indicates that a more significant portion of each sale is available to cover fixed costs and contribute to profit, which is generally favorable for a company’s financial health.
Conversely, a lower contribution margin ratio suggests that a smaller portion of each sale is available to cover fixed costs, making it more challenging for a company to break even or achieve profitability.
Sample Calculation
Suppose you have a company that sells a product and wants to calculate the CMR for a specific period. Here are the relevant numbers:
- Sales Revenue = $50,000
- Variable Costs = $20,000
Now, let us plug these values into the formula for how to calculate the contribution margin and contribution margin ratio.

The spreadsheet above shows that your company’s contribution margin is $30,000. It represents the portion of revenue that remains after covering variable costs, and it provides insights into how much each unit sold contributes to covering fixed costs and generating profit. Furthermore, this example shows the contribution margin ratio (CMR) is 60%. It means that for every dollar of sales revenue generated, $0.60 contributes to covering fixed costs and generating profit after variable costs are deducted.

















Utilizing Contribution Margin Analysis for Financial Success
When unlocking financial success in your business, one powerful tool you should consider is contribution margin analysis (CMA). Here are some ways CMA can drive your business to financial success:
- Determine Profitable Products or Services: By calculating the contribution margin for each product line, you can identify which ones generate the highest profit. CMA allows you to evaluate the profitability of individual products or services. This information lets you focus on promoting and investing in the most profitable areas.
- Enhance Resource Allocation: CMA aids in allocating resources more efficiently by highlighting the highest contributing products or services. By understanding where you reap the most significant rewards, you can allocate resources to areas where they will have the most significant impact on margins and overall profitability.
- Facilitate Decision-Making: CMA provides critical data to help guide business decisions such as expansion, product development, and marketing strategies. By comparing contribution margins, you can make informed choices regarding entering new markets, discontinuing underperforming products, or investing in research and development.
- Improve Cost Management: Knowing the variable costs related to producing each product or service allows you to identify inefficiencies and improve the cost structure. You can negotiate better deals with suppliers, find alternative materials or processes, and streamline operations to reduce waste and enhance efficiency.
- Informed Forecasting: CMA data enables you to create more accurate financial forecasts by offering insights into the relationships between costs, revenues, and profits. These forecasts can guide your decisions about growth opportunities, reinvestments, and risk management.
- Monitor Financial Health: Regularly monitoring contribution margins allows you to gauge the financial health of your business and identify any changes in market conditions or internal issues that may be affecting profitability. Adjusting your strategies based on this insight will help maintain or improve financial success.
- Optimize Pricing Strategy: CMA helps you ascertain the optimal selling price for your products or services by determining the break-even point at which total revenue equals the total costs. A proper pricing strategy can significantly improve your business’s overall profitability and competitiveness.
Using contribution margin analysis, business owners can maximize profits, make informed decisions, and allocate resources more effectively. Adopting this analysis technique is critical to driving your business to financial success.
Elevate Data-Driven Decision-Making with Contribution Margin Analysis Tools
In an increasingly volatile business environment, having the right tools to assess your financial viability is no longer just an advantage — it’s a necessity! Don’t leave your profitability to chance.
At eFinancialModels, we understand that the road to profitability is laden with strategic decisions that require more than just gut feeling or anecdotal evidence. A comprehensive understanding of your revenue streams and variable costs is necessary to gauge your contribution margin analysis.
Our industry-specific financial model templates are crafted with precision and expertise to provide actionable insights. Whether you’re an entrepreneur, investor, or finance professional, you’ll find our tools invaluable for dissecting the subtleties of your revenue and variable costs, thus allowing you to focus on what truly drives your business profitability.










You might also like:
- 10 Step Financial Planning Checklist for Smart Executives
- 10 Ideas to Increase Average Revenue Per User
- Business Valuation
- 5 Practical Tips to Help Raise Funds For Startups
- Key Financial Ratios
- Financial Planning for Small Business Owners – Taking an SBA Loan
- Understanding the Debt Service Coverage Ratio: An Essential Metric for Financial Analysis
- Financial Statements – Definition, Uses, Contents and Templates
- How Contribution Margin Analysis Can Drive Your Business to Financial Success
- Cash Flow Analysis in Excel
- Business Valuation Service
- Understanding the Levelized Cost of Energy Formula
- Financial Model for Simple Retail Chain Rollout
- How to Start a Distillery Business: What You Need to Know?
- How to Build a Capitalization Table
- Personal Budgets
- Financial Modeling for Startups and Small Businesses
- Monthly Recurring Revenue (MRR)
- Startup Financial Models
- Cash Flow Projections
Tags: financial metrics