0 ITEMS
Small Hydropower Bankable Financial Model
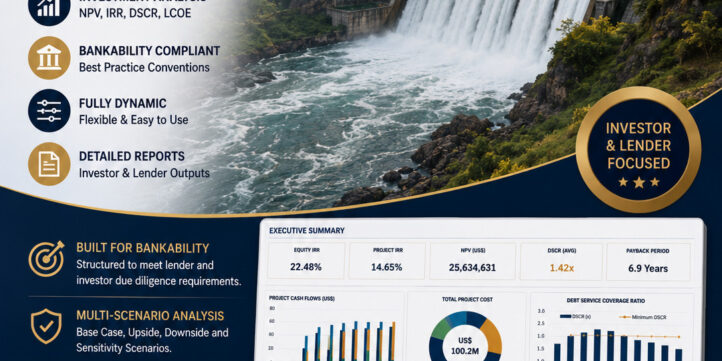
Small Hydropower Bankable Financial Model — Summary This is a fully-linked, institutional-grade Excel financial model for a run-of-river small hydropower project, built to the standard expected by lenders, equity investors, and independent engineers during project finance due diligence. It spans a 27-year timeline (2-year construction + 25-year operations) across 16 interconnected sheets, with every output traceable back to a stated, clearly-flagged assumption. Technical foundation: The model starts with real hydrology — a flow duration curve (Q10–Q100), mean annual flow, an IFC-aligned environmental (compensation) flow, and a design flow selection — then converts this into monthly turbine flow, installed capacity (via the power equation), and P50/P90 annual energy estimates. Financial structure: CAPEX is built up by cost category with contingency, IDC, and financing fees; a senior debt schedule handles drawdown, straight-line amortization, interest, and a DSRA; revenue applies an escalating PPA tariff; opex covers fixed/variable O&M, insurance, land lease, admin, and periodic major maintenance. These feed a full P&L, CFADS/DSCR cash flow waterfall, equity cash sweep, and a balance sheet that ties out to the dollar in every year. Outputs: Project IRR, Equity IRR, NPVs, payback, minimum/average DSCR, LLCR, and PLCR — the standard metrics a credit committee expects. The illustrative base case shows an 18.3 MW plant, ~$47M project cost, 14.3% Project IRR, 20.0% Equity IRR, and 1.35x minimum DSCR against a 1.20x covenant. Risk testing: Five live sensitivity toggles (energy, capex, tariff, opex, interest rate) flow through the entire model instantly, plus a pre-computed table of seven standard scenarios (P90 hydrology, capex overrun, tariff downside, opex overrun, combined downside, and upside cases), each derived from a genuine full-model re-run. Visualization: A dedicated Charts sheet presents 10 clearly labeled, professionally styled charts — clustered column charts (revenue/EBITDA/net income, energy production, equity cash flow, monthly generation profile, scenario comparison), line charts (DSCR vs. covenant, debt vs. cash balance), and pie charts (CAPEX breakdown, financing sources, opex breakdown) — all live-linked and automatically updating. Quality assurance: An automated Model Checks sheet runs eight integrity tests every time the model recalculates (sources = uses, balance sheet balance, non-negative cash, full debt repayment, DSCR covenant compliance, non-negative CFADS, full depreciation, capacity factor sanity) — all currently passing with zero formula errors across the workbook. Design conventions: Standard bankable-model formatting throughout — blue inputs, black formulas, green cross-sheet links, no circular references, and full auditability from Cover sheet to Returns. Caveat: All quantitative inputs (hydrology, costs, tariff, financing terms) are illustrative placeholders with source notes


Small Hydropower Bankable Financial Model
A Fully-Integrated, Lender-Ready Excel Model for Run-of-River Hydropower Projects
Overview
This workbook is a complete, professionally structured financial model built to the standard expected by international lenders, development finance institutions, and equity investors evaluating a small run-of-river hydropower project. It is designed to function as the analytical backbone of a project finance transaction — the single source of truth that technical advisors, lenders’ engineers, tax advisors, and sponsors can all interrogate, stress-test, and rely upon during due diligence.
Unlike simplified feasibility spreadsheets that jump straight from a capacity assumption to a revenue line, this model builds every output from first principles. Hydrology drives energy production; energy production drives revenue; revenue, cost, and financing structure together drive the cash flow waterfall; and the cash flow waterfall drives the returns that ultimately determine whether the project is bankable. Every number on every sheet can be traced backward to a stated assumption, and every assumption is visible, editable, and clearly flagged as an input rather than a calculation.
The model spans a 27-year timeline — a 2-year construction period followed by 25 years of commercial operation — modelled entirely in annual periods with monthly granularity reserved for the hydrological and energy computations where it matters most.
Why This Model Exists
Small hydropower projects occupy an awkward middle ground in project finance. They are too small to justify the multi-million-dollar modelling budgets of large infrastructure deals, yet they carry the same fundamental risks — hydrological uncertainty, construction cost overrun, interest rate exposure, and debt service coverage — that any lender will scrutinize closely before committing capital. This model closes that gap. It gives a small hydro sponsor, developer, or advisory team an institutional-grade tool without the six-figure modelling engagement, while remaining fully transparent and auditable — no black boxes, no hidden macros, no proprietary add-ins.
It is equally useful in several contexts:
- Project sponsors preparing a bankable feasibility study or information memorandum for lenders and equity partners
- Financial advisors and consultants who need a robust starting template they can recalibrate quickly to a new site’s hydrology and cost profile
- Lenders and their independent engineers who want a transparent model they can pressure-test line by line during due diligence
- Academic and training contexts, where the model serves as a teaching tool for project finance, renewable energy economics, or infrastructure modelling courses
Structural Philosophy
The model follows the conventions that lenders and rating agencies expect to see in any bankable infrastructure model:
- Color-coded cell logic — blue for hardcoded inputs, black for formulas, green for cross-sheet links — so that any reviewer can immediately distinguish an assumption from a calculation without opening each cell
- A single, consistent timeline running across every operating sheet, so that column E on the Debt sheet, the Revenue sheet, and the Cashflow sheet all refer to the same operating year
- No circular references — interest expense is calculated on opening debt balances rather than average balances, a deliberate simplification that keeps the model stable and fast to recalculate without iterative calculation settings
- Full traceability — every output on the Returns sheet can be followed back through the P&L, Cashflow, Debt, Revenue, and Energy sheets to the original technical or commercial assumption that produced it
- An embedded audit trail — a dedicated Model Checks sheet runs eight automated integrity tests every time the model recalculates, so errors introduced by future edits are caught immediately rather than discovered during a lender’s review
What the Model Covers, Sheet by Sheet
Cover — A project summary and full table of contents, establishing the currency, modelling basis, and financing structure at a glance.
Assumptions — The single control panel for the entire model: macroeconomic parameters (inflation, tax, discount rates), technical and hydrological parameters (gross head, head losses, turbine and generator efficiency, environmental flow policy, design flow percentile), CAPEX and financing parameters (cost build-up, gearing, tenor, interest rate, DSRA requirement, minimum DSCR covenant), and revenue and operating cost assumptions. A dedicated block of five sensitivity toggle cells allows a user to stress-test energy output, CAPEX, tariff, opex, and interest rate assumptions live, with the effect flowing through every downstream sheet instantly.
Hydrology — The technical foundation of the model. A flow duration curve (Q10 through Q100) establishes the statistical character of the river, from which the mean annual flow, the environmental (compensation) flow — set per IFC Performance Standard 6 / Building Block Methodology conventions — and the design flow are derived. Twelve months of long-term average flow data feed a monthly calculation of available flow, turbine flow (capped at design flow), and spill, giving a realistic month-by-month picture of how the plant will actually operate across a typical hydrological year.
Energy — Converts hydrology into megawatts and megawatt-hours. Installed capacity is derived directly from the physical power equation (density × gravity × design flow × net head × overall efficiency), and monthly energy output is computed from the Hydrology sheet’s turbine flow profile. The sheet produces both a P50 (long-term average) and P90 (dry-year) annual energy estimate, then carries the P50 case forward across all 25 operating years, adjusted for a commissioning ramp-up in Year 1, steady-state availability thereafter, and auxiliary/station consumption.
CAPEX — Builds total project cost from its component parts (civil works, electro-mechanical equipment, grid connection, land, environmental and social costs, owner’s costs, and contingency), schedules the spend across the two construction years, computes interest during construction on a mid-year drawdown convention, capitalizes the debt arrangement fee, and reconciles total sources of funds against total uses to the dollar.
Debt — A full senior debt schedule: drawdown (including capitalized construction-period interest and fees), straight-line amortization over a lender-specified tenor, opening-balance interest calculation, and a Debt Service Reserve Account sized at a specified number of months of forward debt service, funded at financial close and released at final maturity.
Revenue — Applies an escalating PPA tariff, indexed to a configurable share of general inflation, to the net energy sold each year, incorporating the tariff sensitivity toggle.
Opex — Builds operating costs from fixed O&M (scaled to installed capacity), variable O&M (a percentage of revenue), insurance, land lease/water royalty, administration, and a periodic major maintenance reserve for turbine overhauls — all escalated with inflation.
Depreciation — A straight-line depreciation schedule over the full asset life, feeding both the P&L and the balance sheet’s net book value.
PnL — A conventional income statement from revenue down to net income, correctly excluding construction-period interest (which is capitalized into CAPEX rather than expensed).
Cashflow — The heart of any project finance model: working capital, CFADS, annual DSCR, debt service, DSRA movements, and a full equity cash flow waterfall with a cash sweep mechanism that distributes 100% of available cash as dividends once debt service and reserve requirements are met.
BalanceSheet — A complete balance sheet (cash, receivables, net fixed assets, DSRA on the asset side; payables and senior debt on the liability side; share capital and retained earnings on the equity side) that balances to the dollar in every single year, verified automatically by the Model Checks sheet.
Returns — Project IRR and NPV (pre-financing), Equity IRR and NPV (post-financing), payback period, minimum and average DSCR, DSCR covenant compliance, and both Loan Life Cover Ratio (LLCR) and Project Life Cover Ratio (PLCR) — the metrics a lender’s credit committee will look for first.
Sensitivity — Five live stress-test toggles plus a pre-computed table of seven standard scenarios (P90 hydrology, CAPEX overrun, tariff downside, opex overrun, a combined downside case, and an upside case), each independently re-run through the full model so the reported IRR and DSCR impacts are genuine model outputs rather than approximations.
Charts — Visual summaries of revenue and profitability, energy production, the DSCR profile against covenant, debt and cash balances over time, and the equity cash flow profile.
ModelChecks — Eight automated pass/fail integrity tests (sources = uses, balance sheet balances, non-negative cash, full debt repayment, DSCR covenant compliance, non-negative CFADS, full depreciation, and capacity factor sanity), color-coded green or red, alongside a one-glance key output summary.
Illustrative Base Case
With the default assumptions supplied, the model describes an 18.3 MW plant producing approximately 105,550 MWh per year, a total project cost of roughly $47 million, a Project IRR of 14.3%, an Equity IRR of 20.0%, and a minimum DSCR of 1.35x against a 1.20x covenant — return and coverage metrics consistent with what a small hydro project of this scale could realistically expect to present to lenders and equity investors.
Important Caveat
Every quantitative input in this workbook — hydrological data, capital costs, tariff, financing terms — is illustrative and clearly source-noted as such. The model’s value lies in its structure, its linkages, and its analytical completeness, not in the specific numbers supplied. Before this model is used to support an actual financing decision, every assumption must be replaced with project-specific data drawn from a hydrological study, EPC quotations, a signed or term-sheeted PPA, and indicative lender terms.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.