0 ITEMS
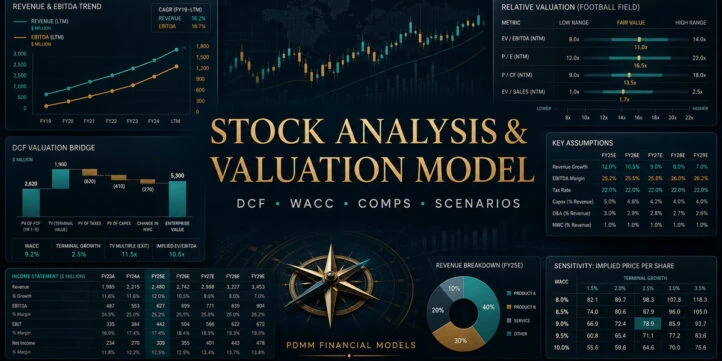
Stock Analysis & Valuation Model – Three-Statement Forecast, DCF, WACC, Comps, Precedents, DDM, Scenarios & Football Field
Turn a public company’s operating assumptions into a decision-ready equity valuation with this premium, fully integrated stock analysis model. The workbook combines ten years of financial statements—five historical years and five forecast years—with segment-level revenue drivers, a complete three-statement forecast, ratio and DuPont analysis, a peer-based WACC, DCF valuation, genuine Base/Bull/Bear scenario engines, sensitivity analysis, comparable companies, precedent transactions, a multi-stage dividend discount model, a football field, and an executive dashboard. The model is delivered with a fictional industrial technology company so every formula, valuation bridge, chart, and control can be inspected end to end. Replace the clearly identified inputs with researched company and market data, select the active case and valuation convention, and the linked schedules update automatically. Twenty-eight live audit checks help test statement articulation, cash-flow integrity, scenario consistency, valuation bridges, and key outputs. Ideal for equity research, investment analysis, corporate finance, transaction advisory, valuation training, and internal decision support. Native Microsoft Excel format; fully editable; no macros, external links, or data connections. Illustrative data only—not investment advice.
📈 Move from raw assumptions to a complete, defensible stock valuation—inside one integrated Excel workbook.
The Stock Analysis & Valuation Model is a premium equity-research and corporate-finance template built for analysts who need more than a basic DCF calculator. It connects company assumptions, segment operating drivers, historical financials, a five-year three-statement forecast, capital structure, valuation methods, scenario analysis, sensitivities, charts, and live controls in one transparent model.
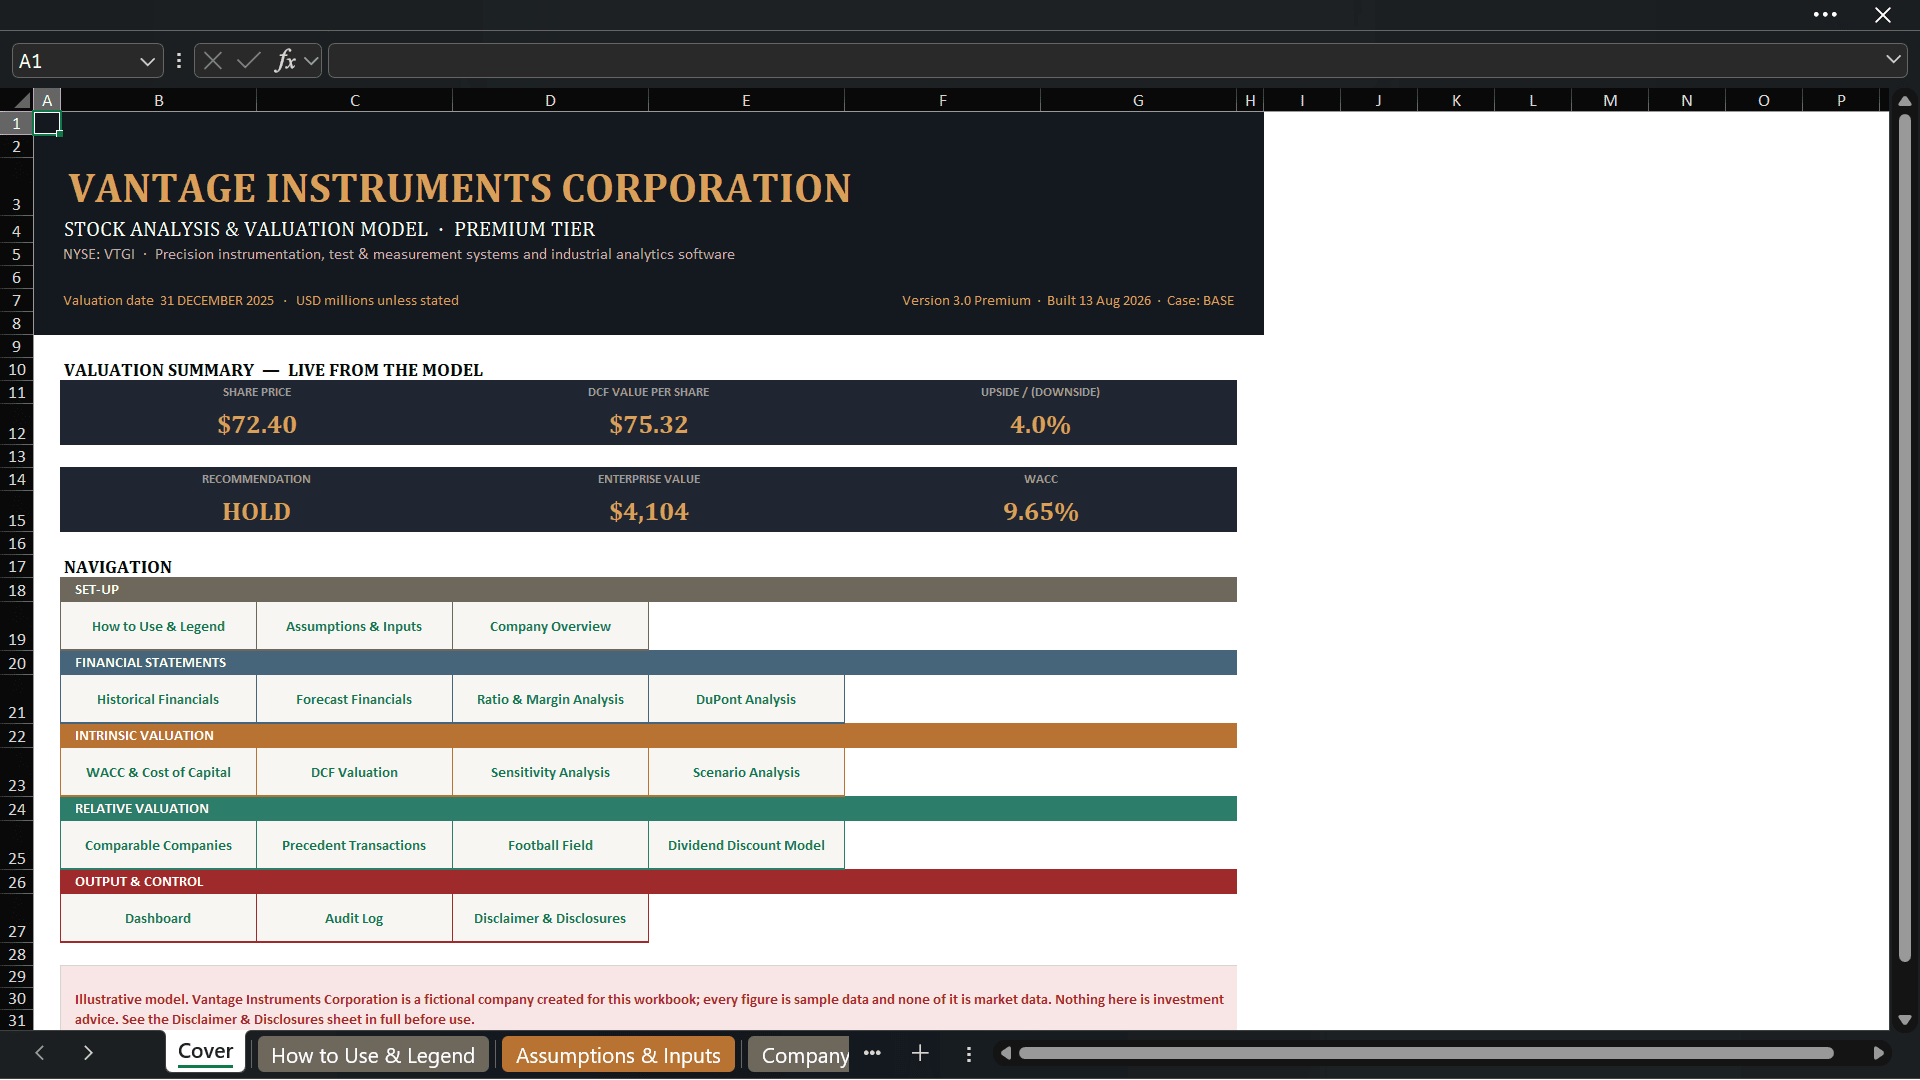
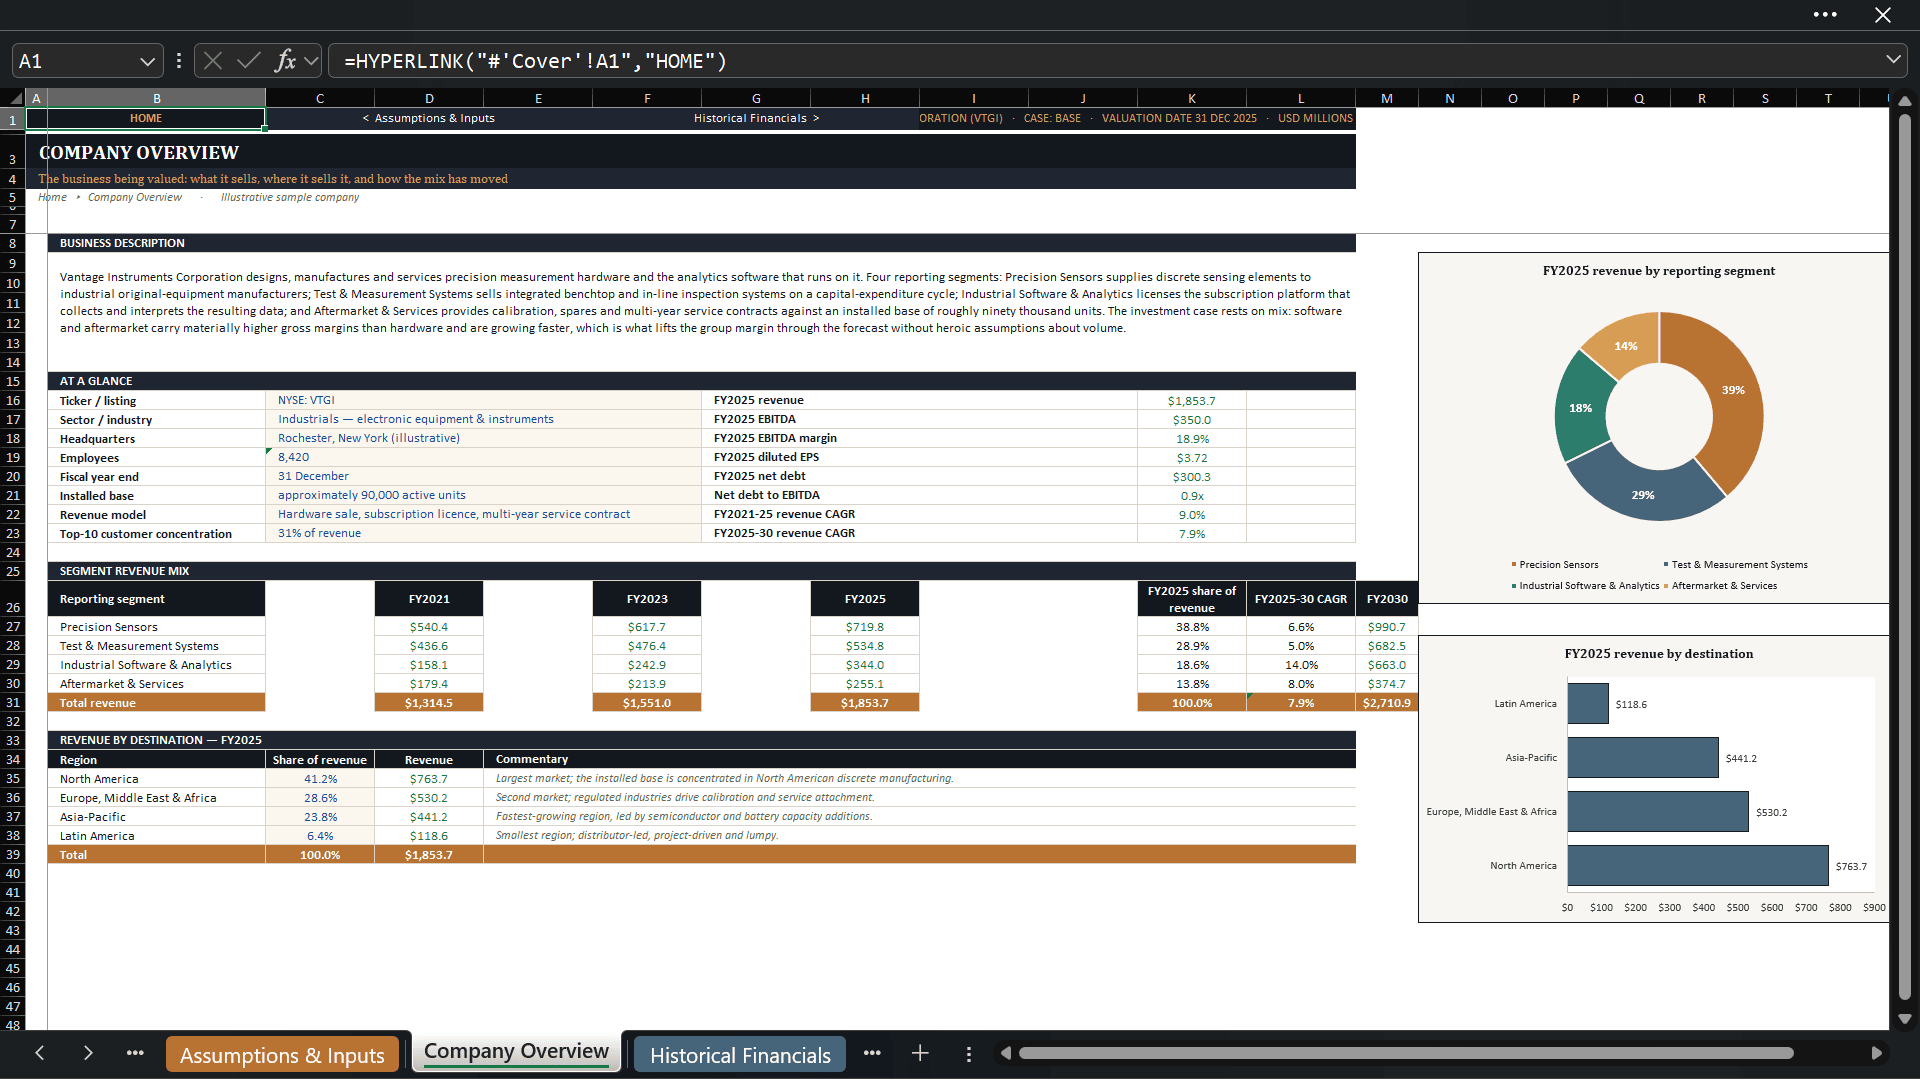
The workbook is populated with Vantage Instruments Corporation (NYSE: VTGI), a fictional industrial technology company with four operating segments. The sample company and all peer and transaction data are synthetic. This deliberate design lets you inspect the full modeling logic without implying that the workbook contains current market research or a recommendation on a real security.
🔍 What Is Inside the Workbook?
The model contains 19 professionally structured worksheets covering the full equity-analysis workflow:
- Cover, navigation, instructions, and modeling legend
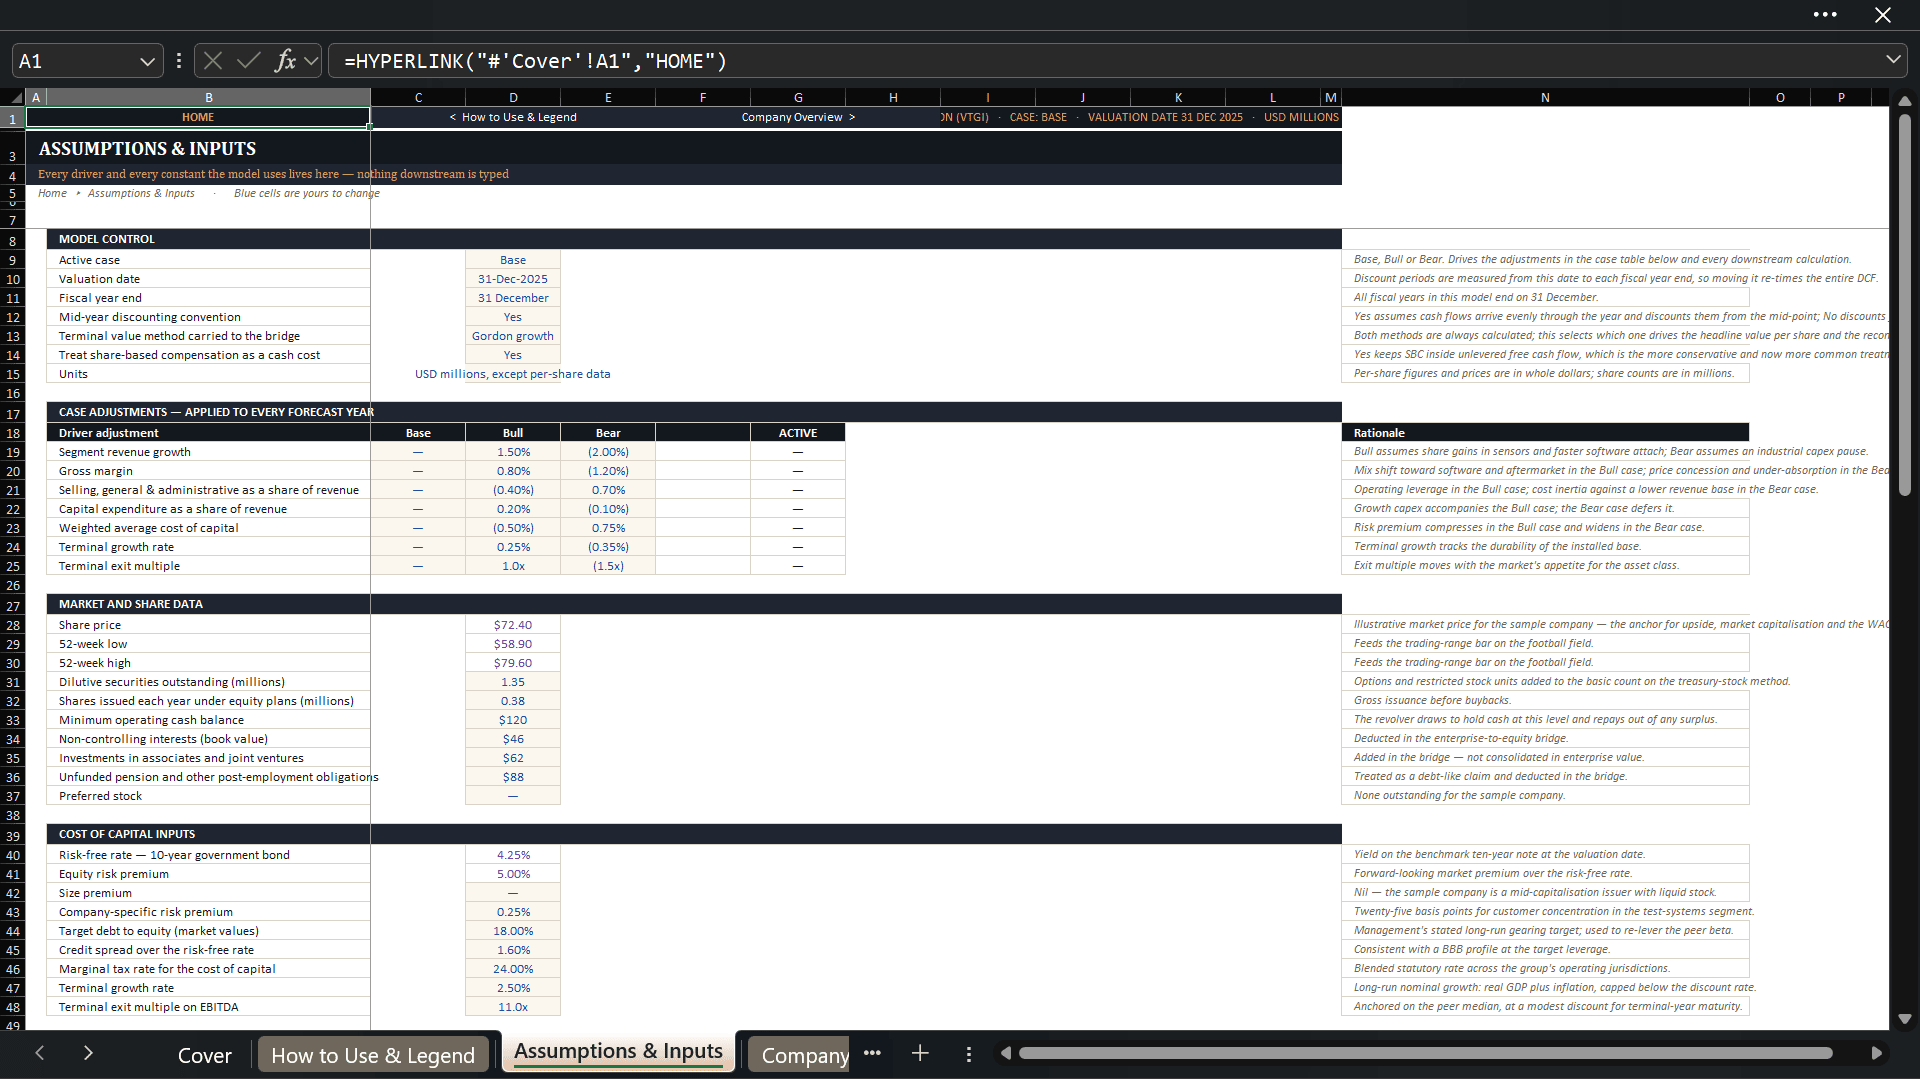
- Assumptions and user inputs
- Company overview and investment profile
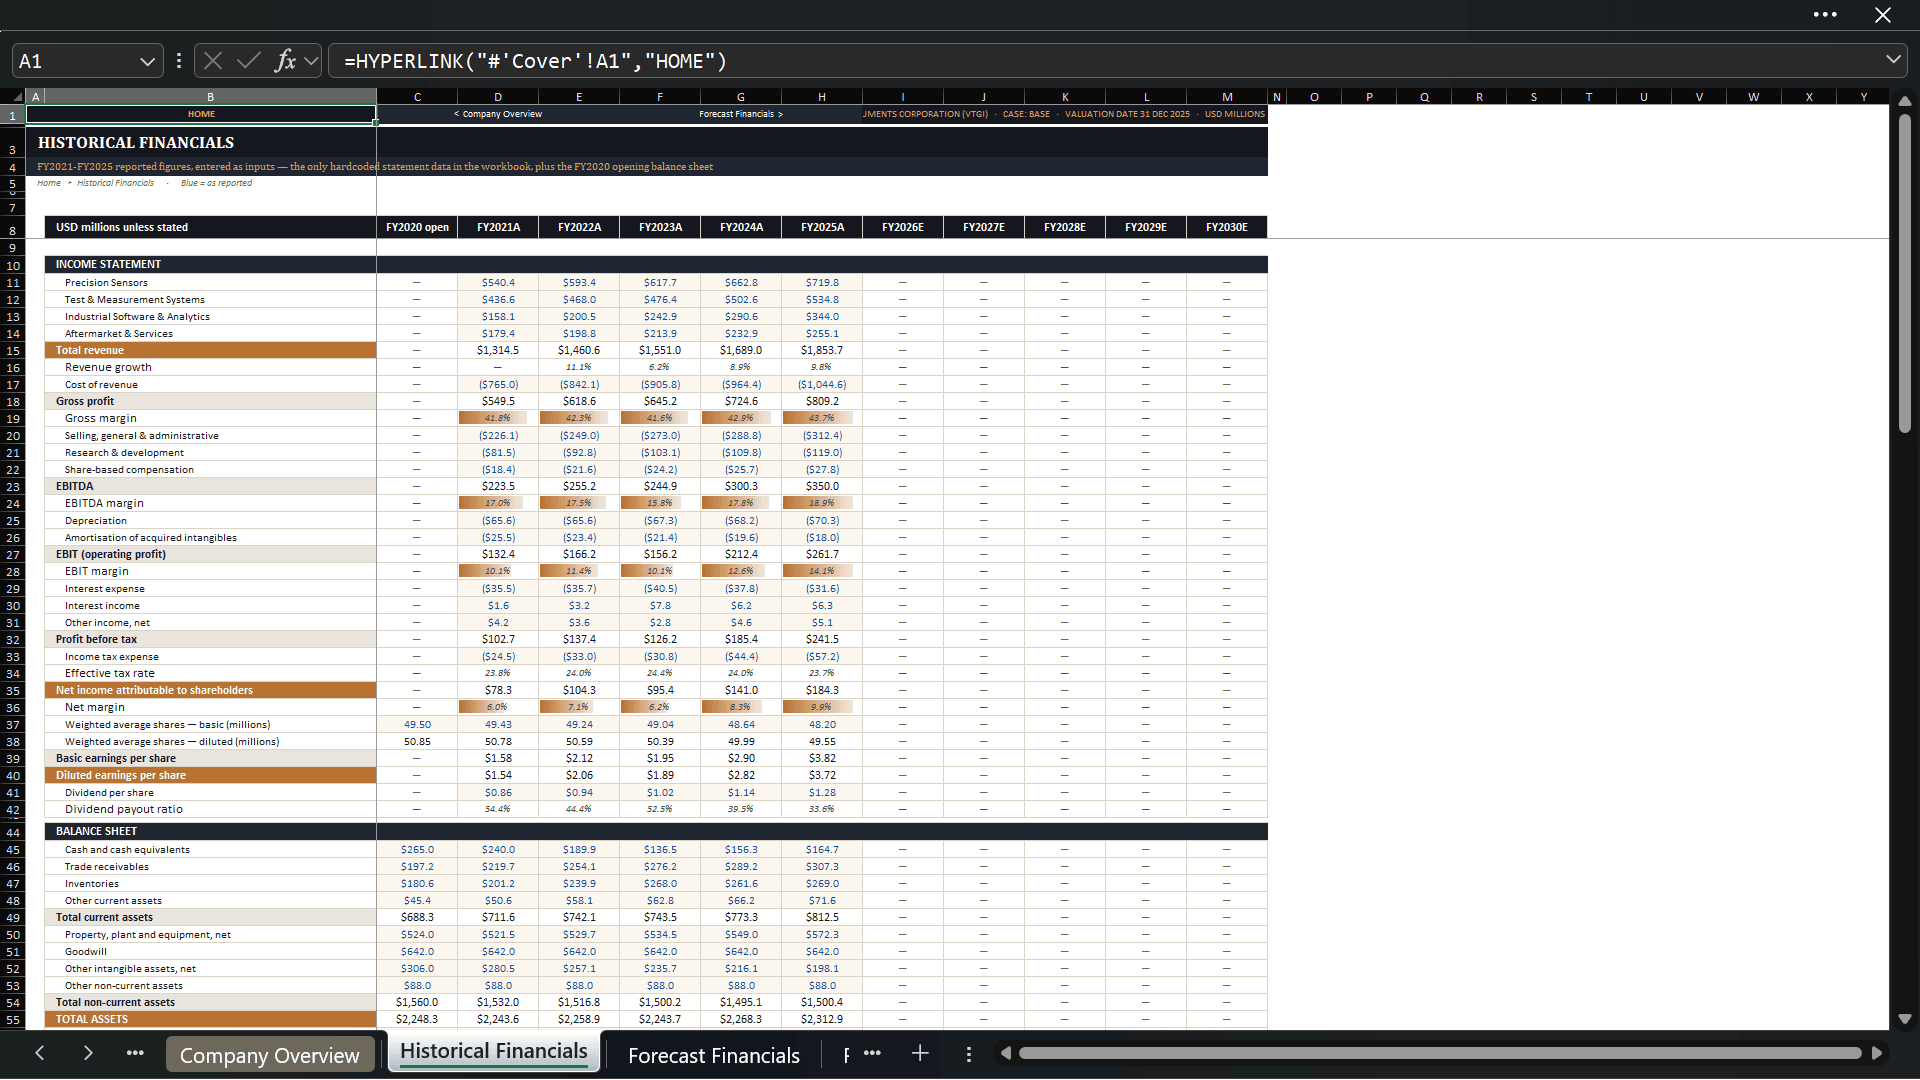
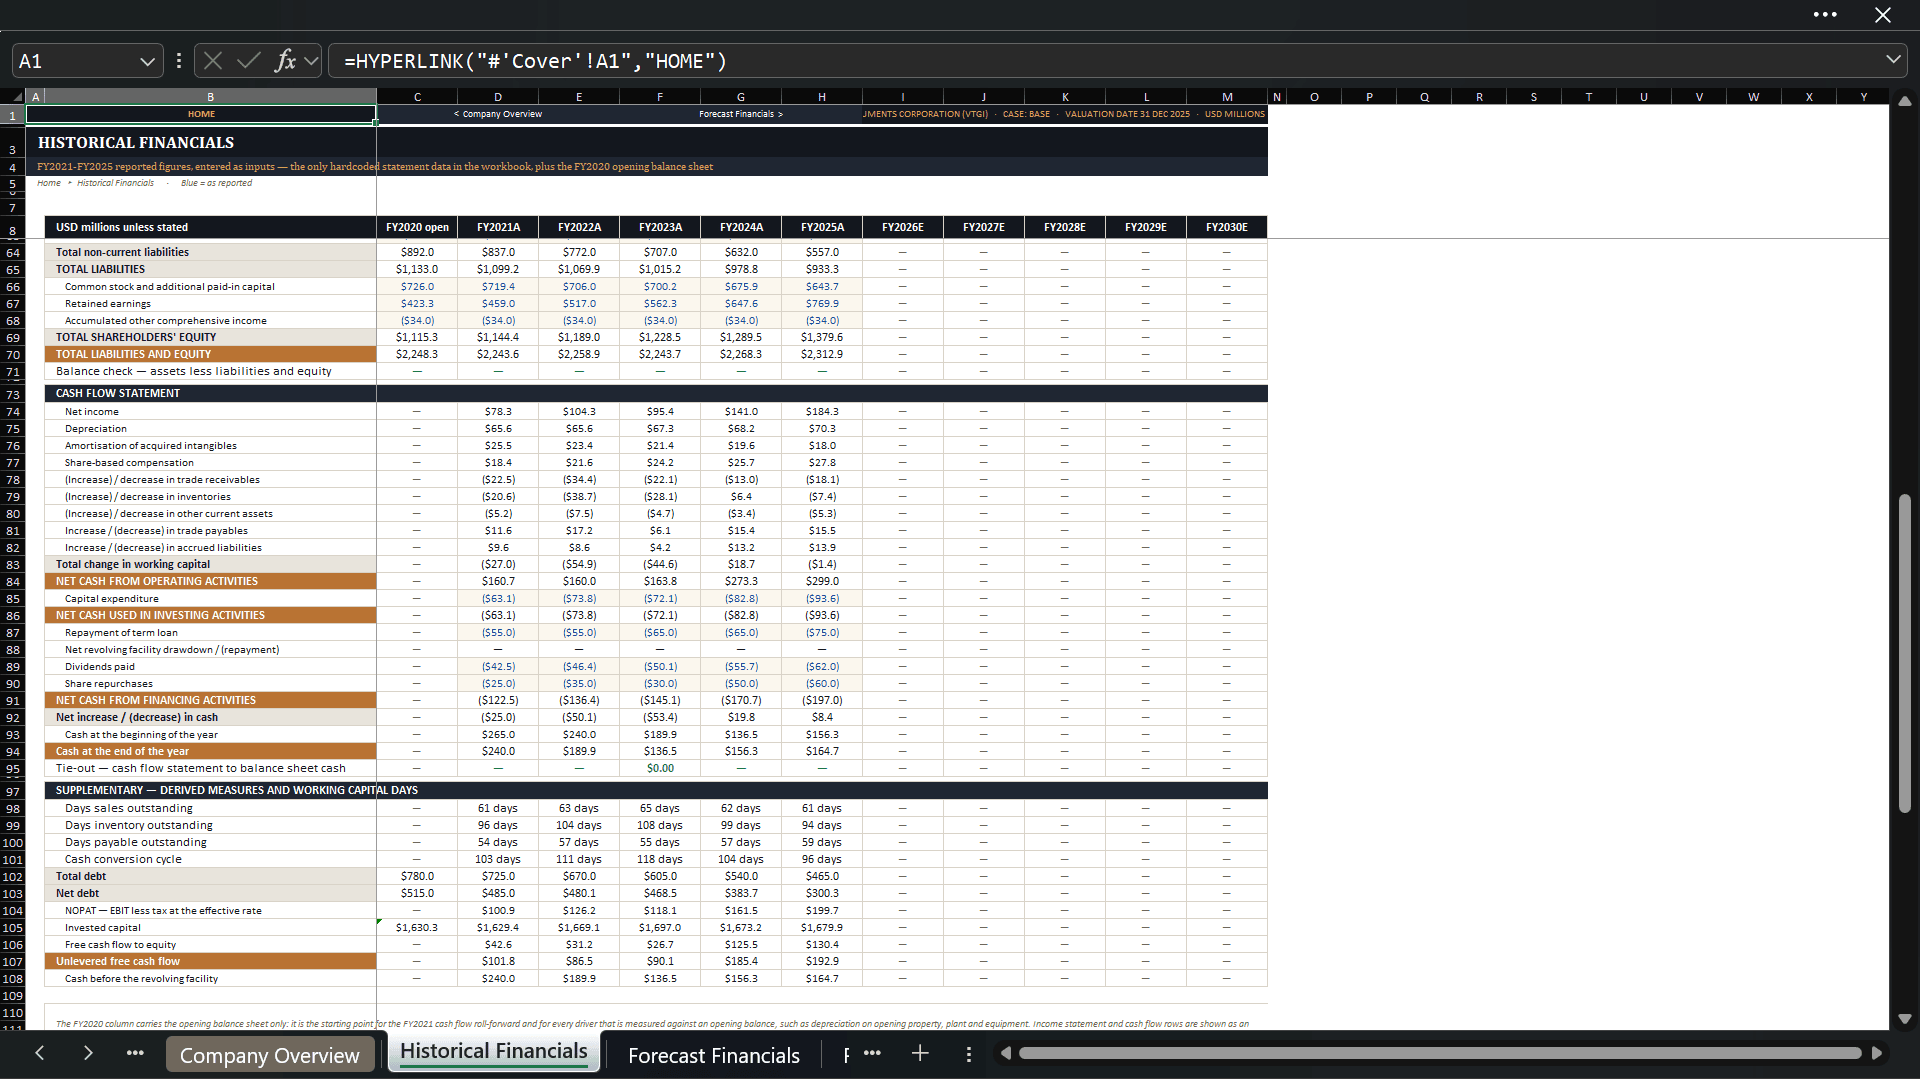
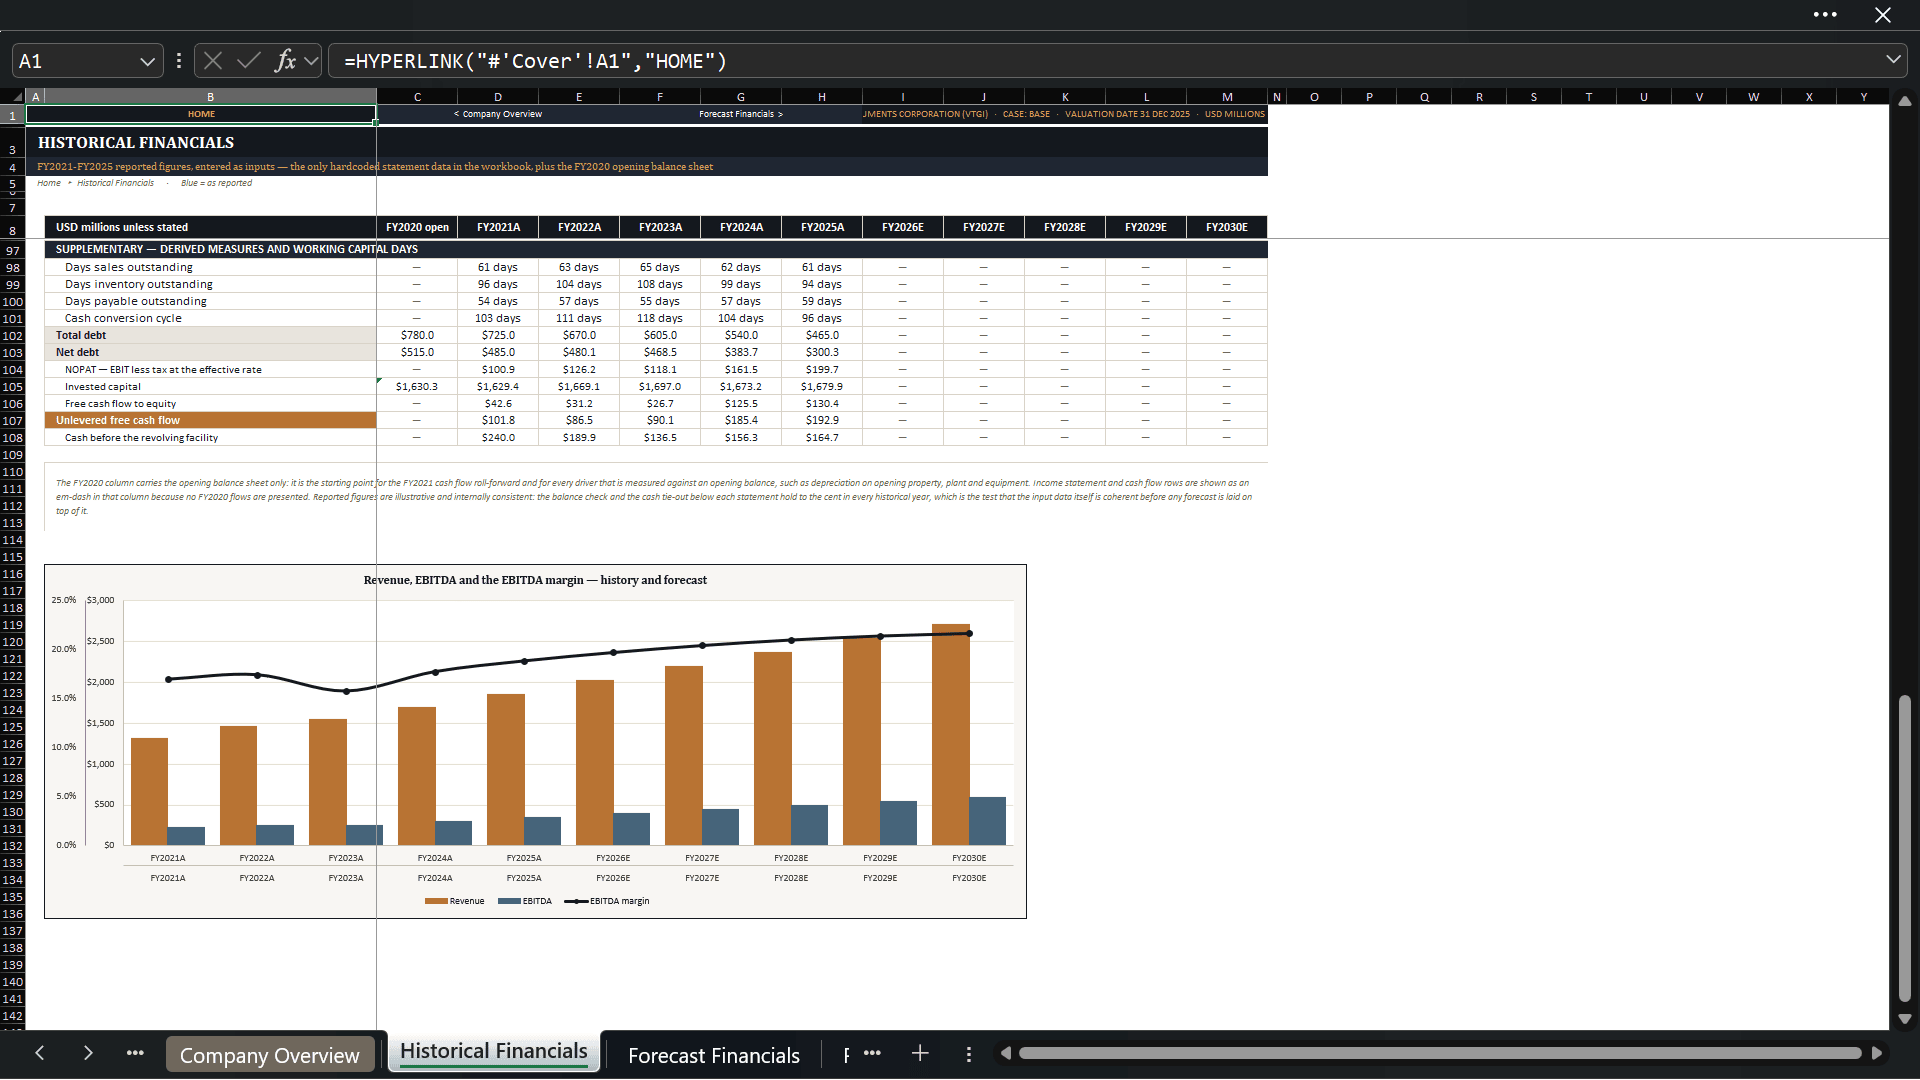
- Five years of historical financial statements
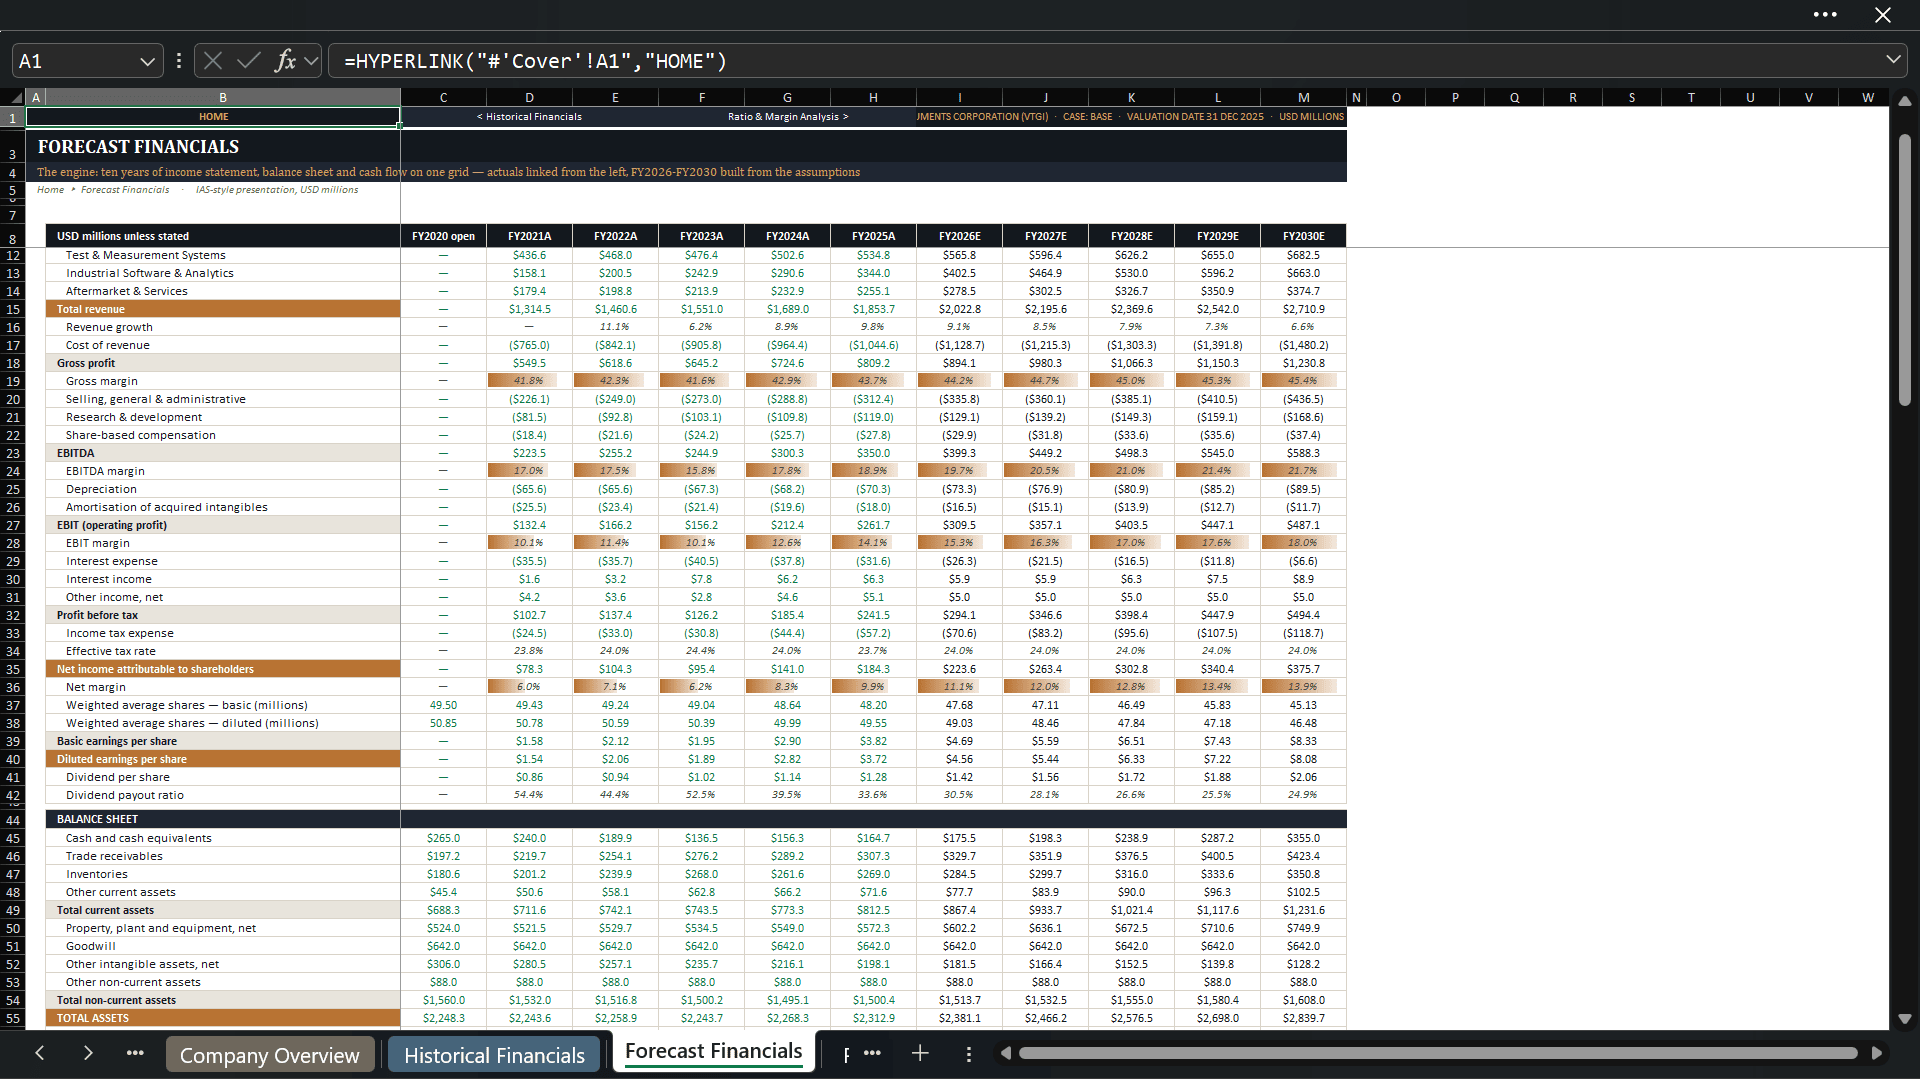
- Five years of forecast financial statements
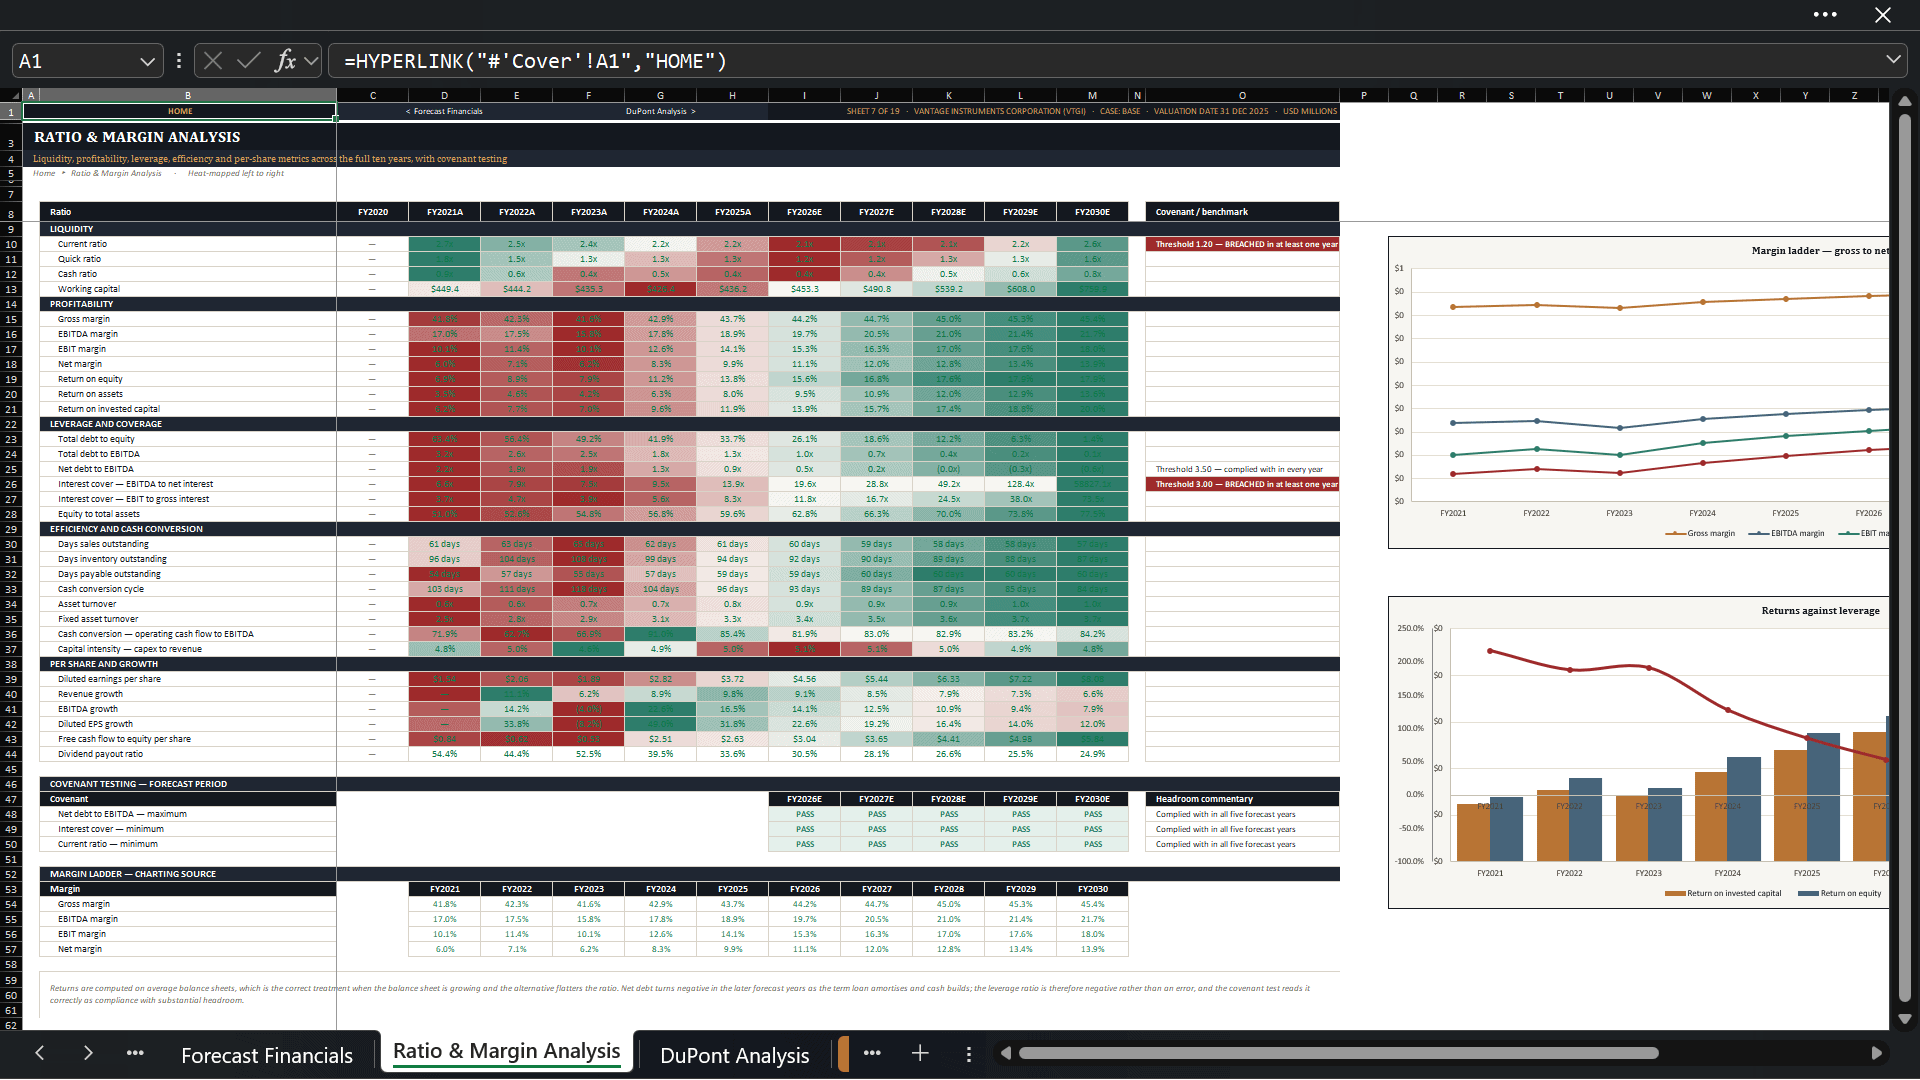
- Ratio and margin analysis
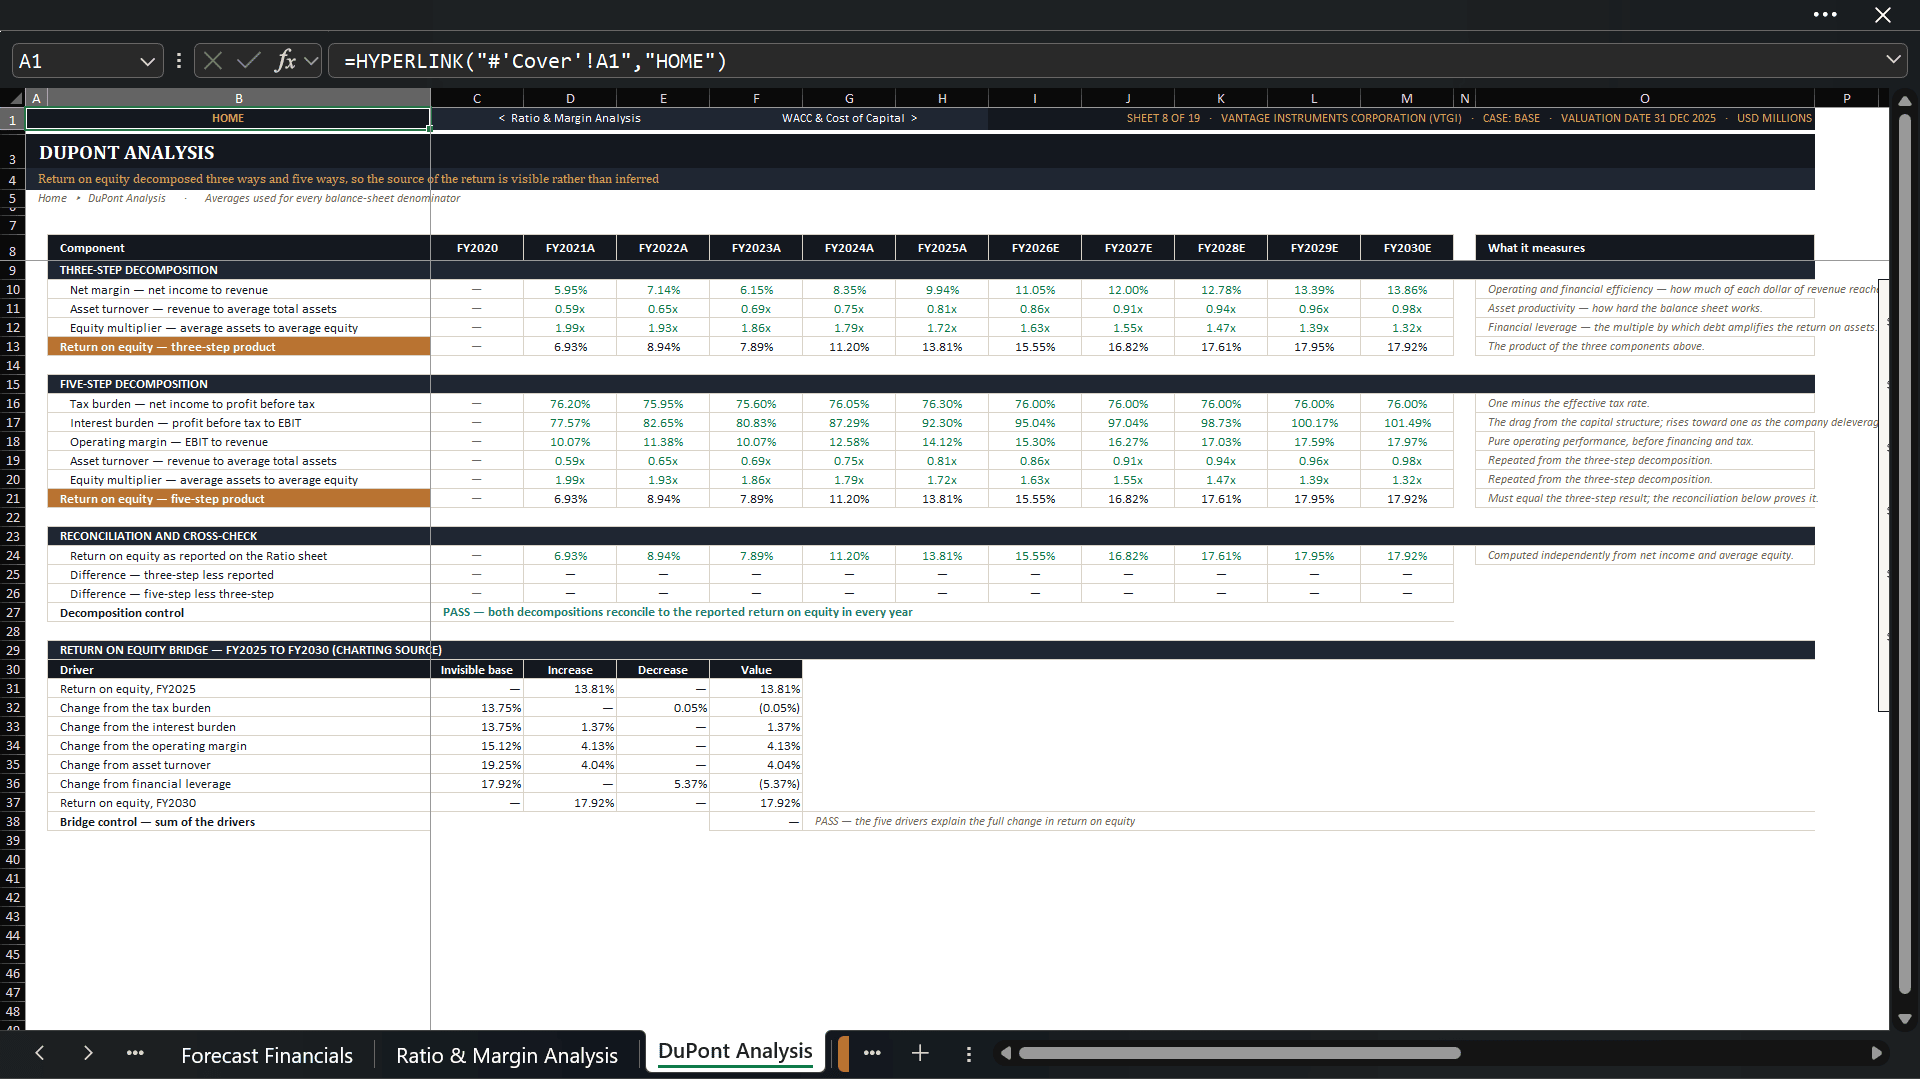
- Three-step and five-step DuPont analysis
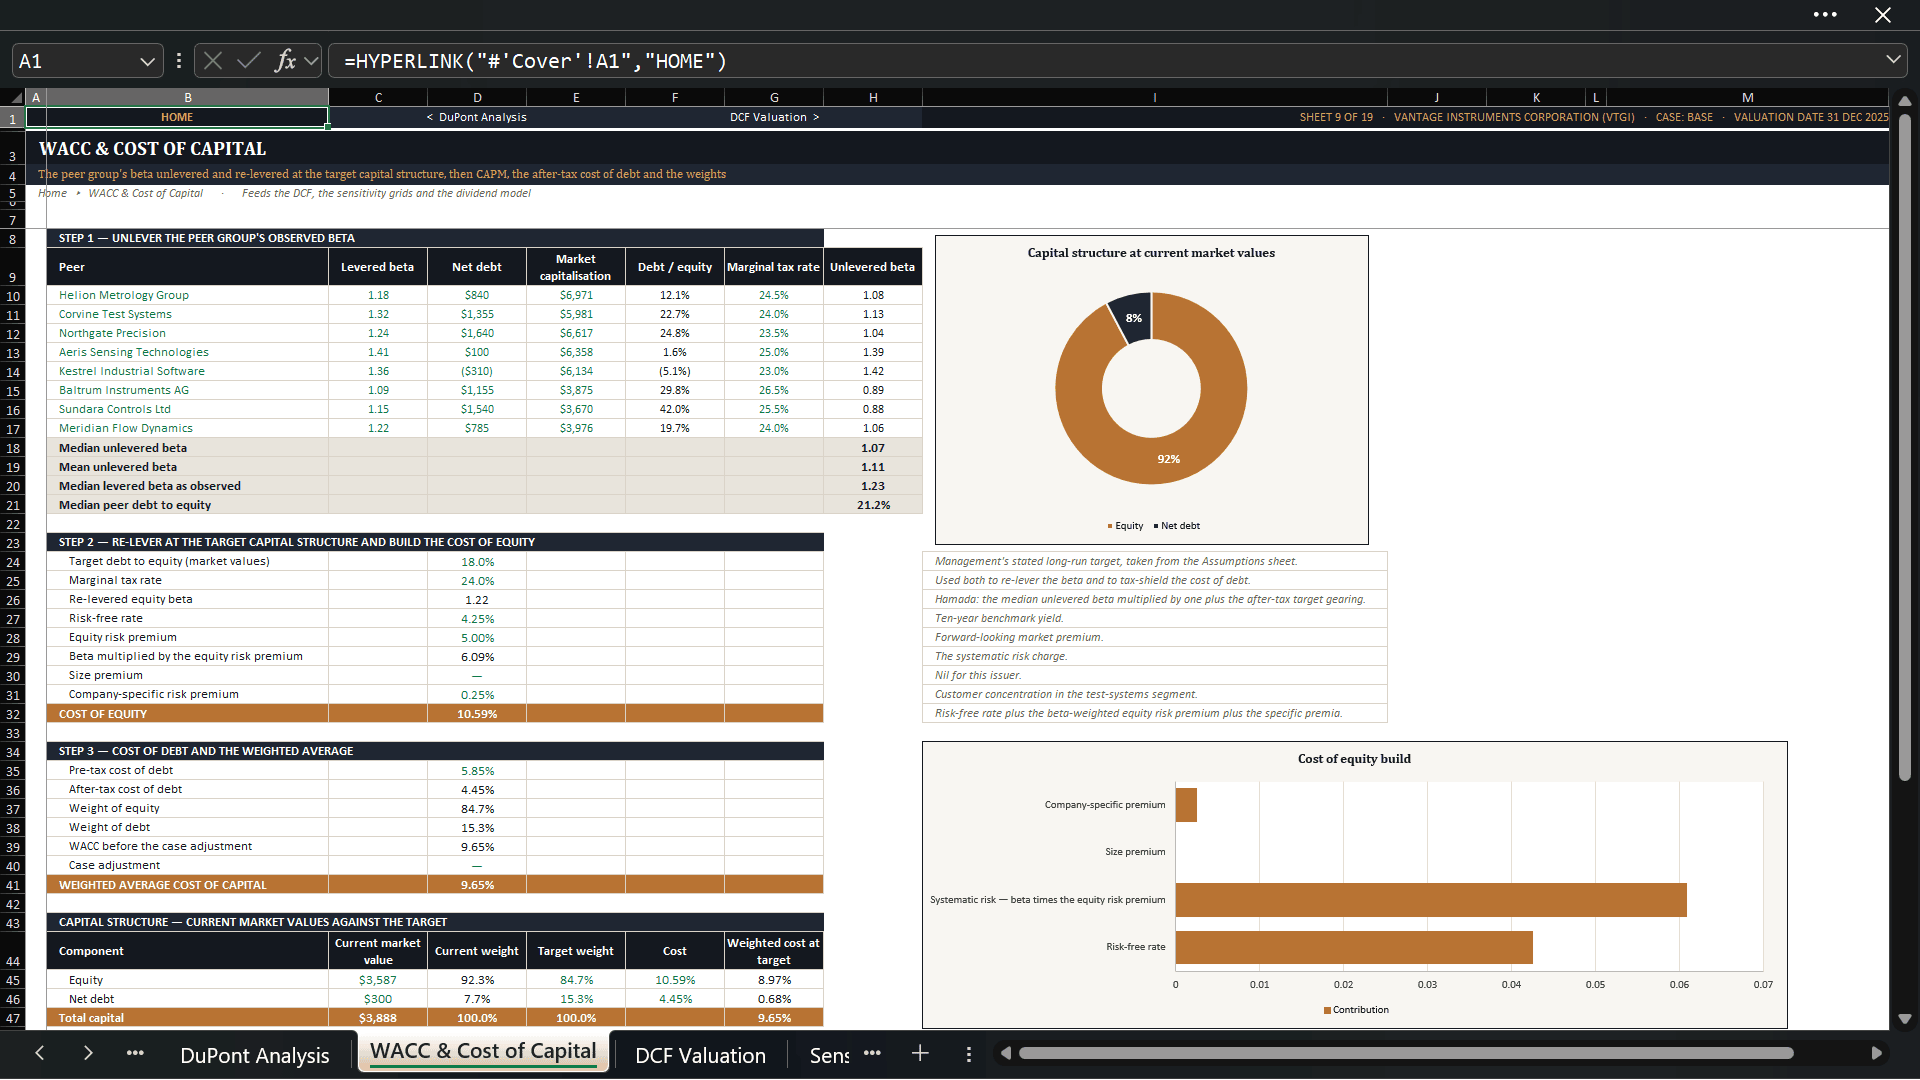
- WACC and cost-of-capital build
- Discounted cash flow valuation
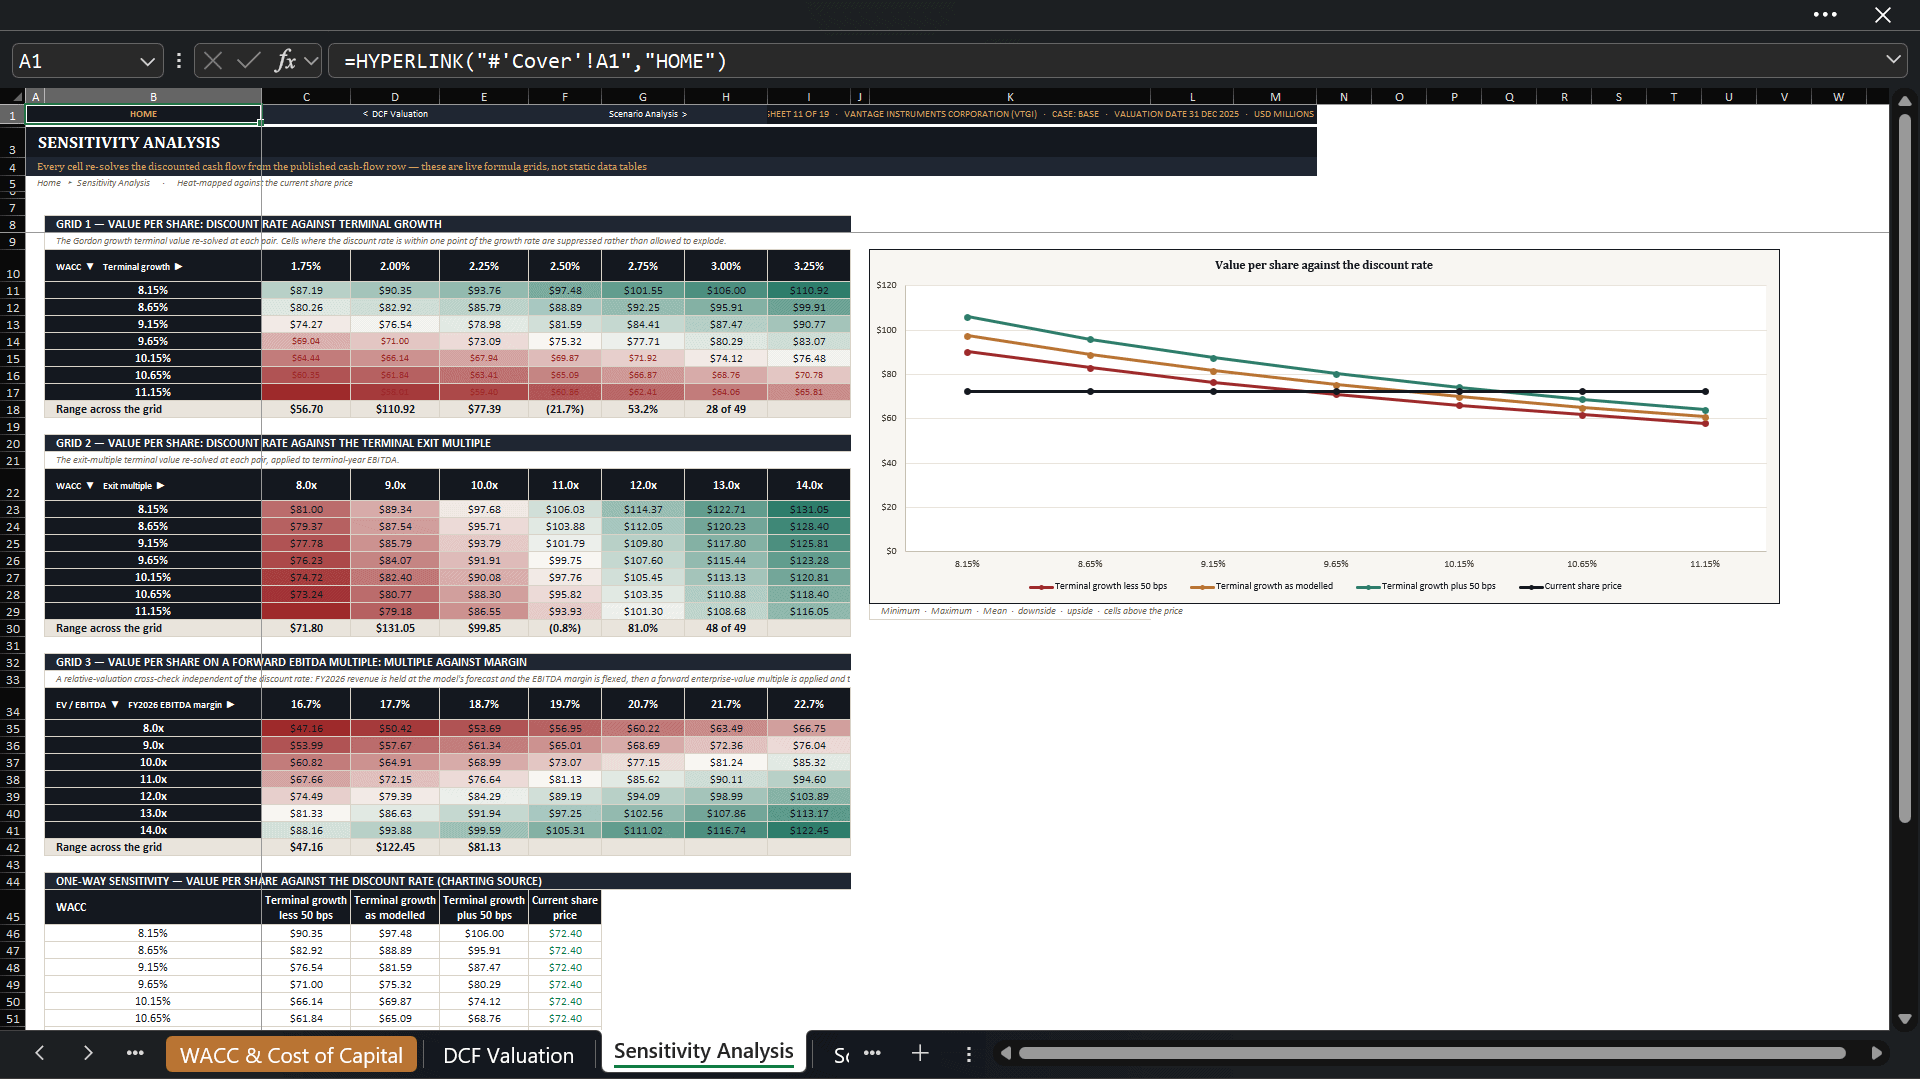
- Sensitivity analysis
- Base, Bull, and Bear scenario analysis
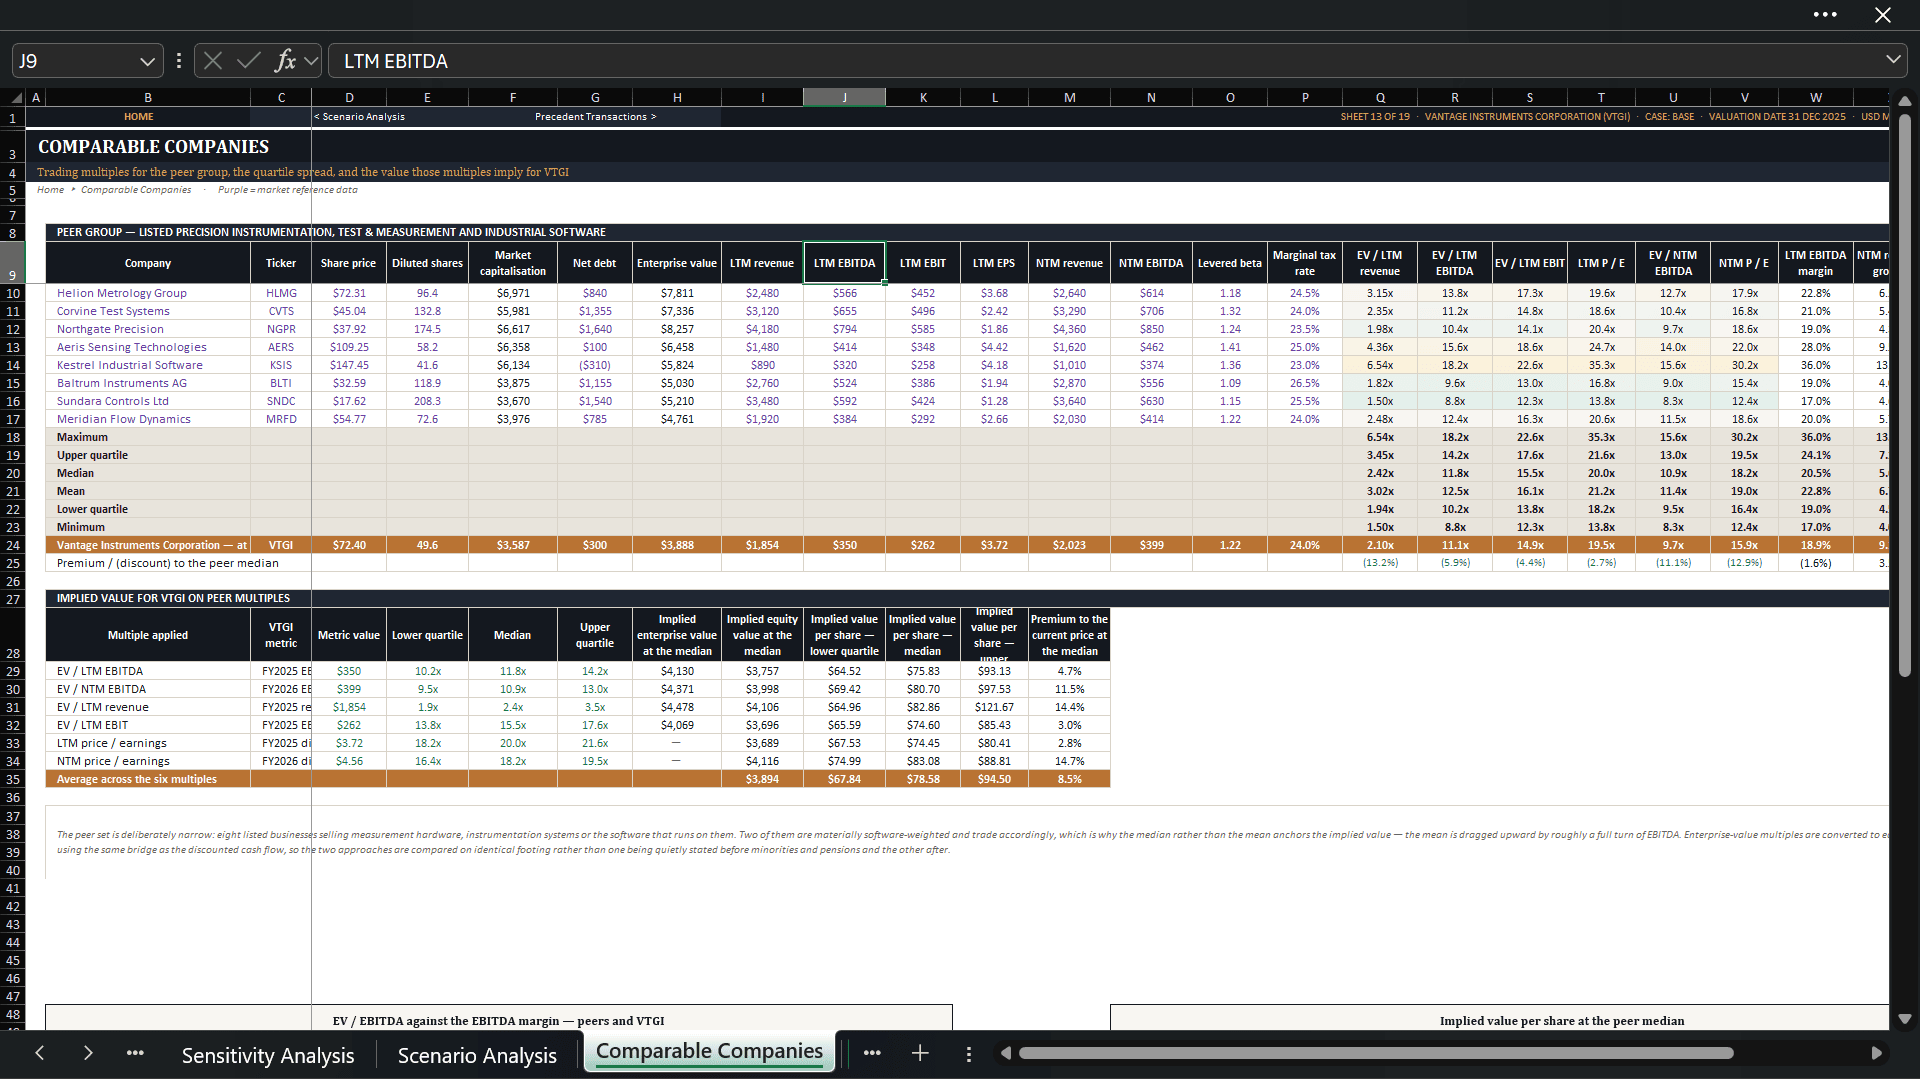
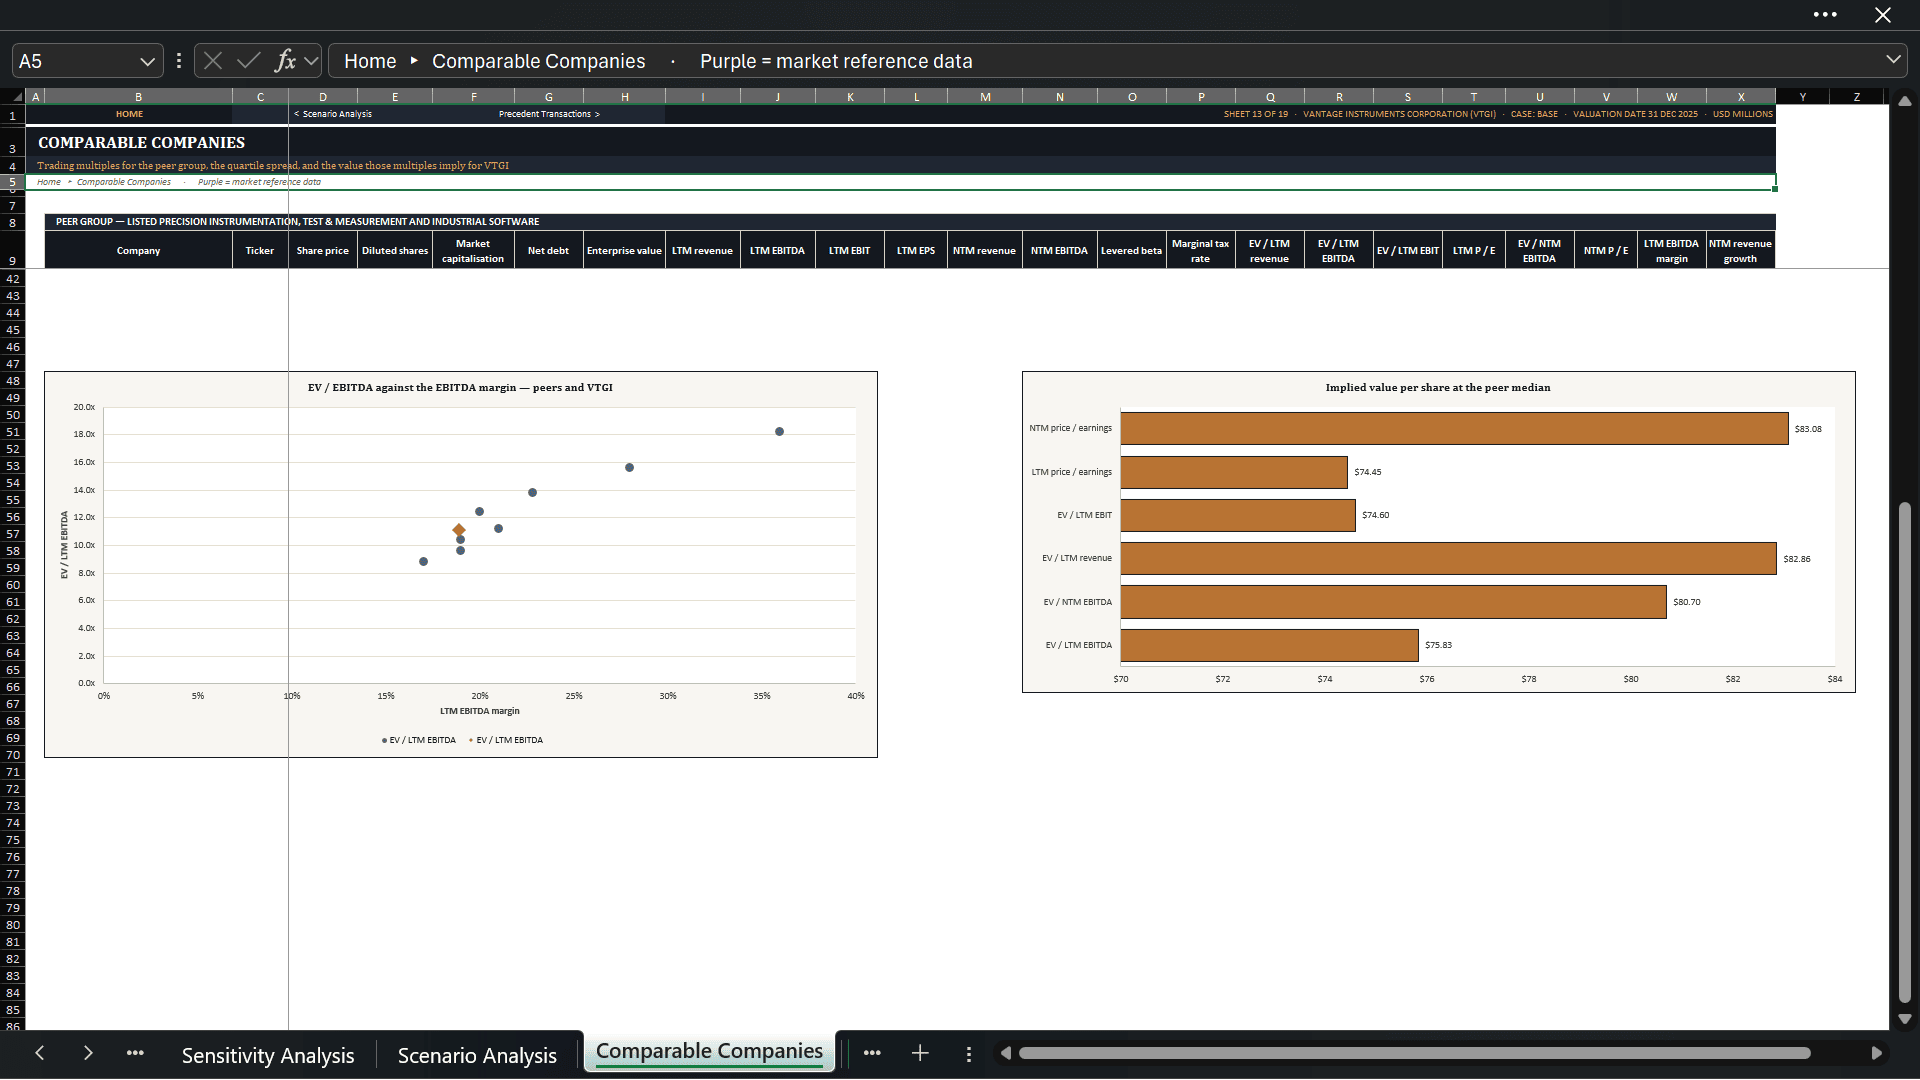
- Comparable-company analysis
- Precedent-transaction analysis
- Football-field valuation
- Multi-stage dividend discount model
- Executive dashboard
- Audit log with 28 live checks
- Disclaimer and model disclosures
Together, the historical and forecast periods provide a ten-year financial view from FY2021 through FY2030, with FY2020 opening balance-sheet support where required.
🏭 Segment-Level Operating Forecast
Instead of applying one growth rate to total revenue, the forecast is built around four distinct operating segments:
- Precision Sensors
- Test & Measurement Systems
- Industrial Software & Analytics
- Aftermarket & Services
Each segment can carry its own growth assumptions, allowing the model to reflect different demand patterns, recurring-revenue characteristics, and maturity profiles. Operating assumptions then flow through gross margin, selling and administrative expenses, research and development, capital expenditure, depreciation and amortization, working capital, taxes, financing, dividends, and share count.
This makes the template especially useful for industrial, manufacturing, instrumentation, technology-enabled, and mixed hardware–software businesses. It can also be adapted to other non-financial listed companies whose economics can be represented through operating segments and standard corporate financial statements.
🧾 Fully Linked Three-Statement Model
The workbook integrates the Income Statement, Balance Sheet, and Cash Flow Statement across the forecast period. The model covers revenue, cost of sales, operating expenses, EBITDA, EBIT, taxes, net income, cash, receivables, inventory, other working capital, property and equipment, intangible assets, debt, equity, retained earnings, cash from operations, investing activity, financing activity, dividends, buybacks, diluted shares, and earnings per share.
Key supporting mechanics include:
- Revenue and margin assumptions by operating segment
- Working-capital drivers based on operating days and percentages
- Property, plant and equipment and intangible-asset roll-forwards
- Debt amortization and revolver mechanics
- Minimum-cash support
- Dividend and share-repurchase assumptions
- Basic and diluted share-count development
- Stock-based-compensation cash-cost toggle
- Opening-balance interest convention that avoids circular references
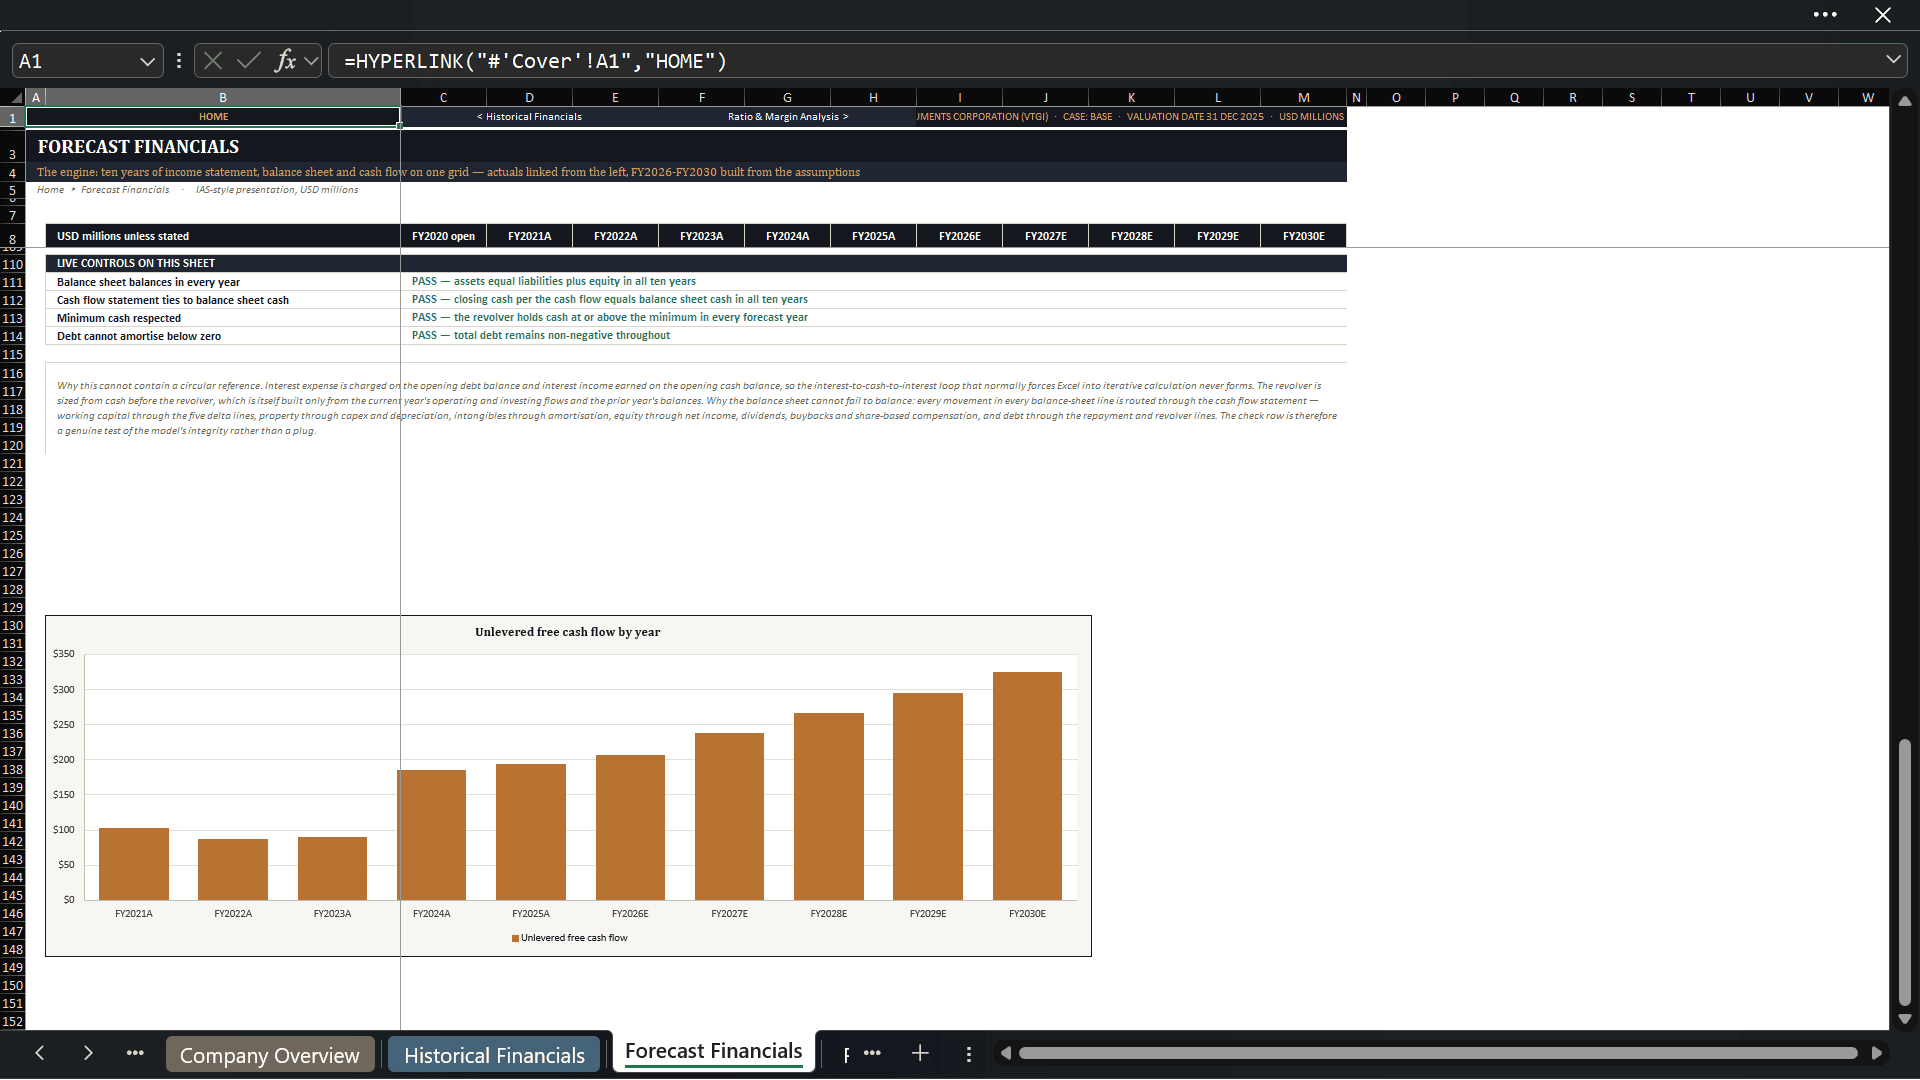
The statements are designed to articulate with each other, so a change in an operating assumption is carried through cash flow, the balance sheet, financing needs, per-share results, and valuation.
⚙️ Central Assumptions and Case Controls
User-editable assumptions are centralized and visually distinguished from calculated cells. The model includes an active Base / Bull / Bear case selector, a valuation date, mid-year versus end-year discounting, a terminal-method selector, and valuation-specific inputs.
Scenario overlays can adjust:
- Segment revenue growth
- Gross margin
- Selling and administrative expense as a percentage of revenue
- Capital expenditure as a percentage of revenue
- WACC
- Perpetual terminal growth
- Terminal exit multiple
The active case drives the complete three-statement model. The Scenario Analysis sheet also runs independent mirrored cash-flow engines for all three cases, preventing the Bull and Bear outputs from becoming static typed numbers.
💰 Peer-Based WACC and Cost of Capital
The cost-of-capital module provides a transparent build rather than asking the user to type a discount rate without support. It includes:
- Peer levered betas
- Unlevering using peer capital structures and tax rates
- Median unlevered beta
- Re-levering at the target debt-to-equity structure
- CAPM cost of equity
- Risk-free rate, equity risk premium, and specific premia
- Pre-tax and after-tax cost of debt
- Current and target capital-structure weights
- Scenario-specific WACC adjustment
In the included sample case, the workbook calculates a 9.65% WACC and a 10.59% cost of equity. These are illustrative model outputs, not current market assumptions.
🧮 Institutional-Style DCF Valuation
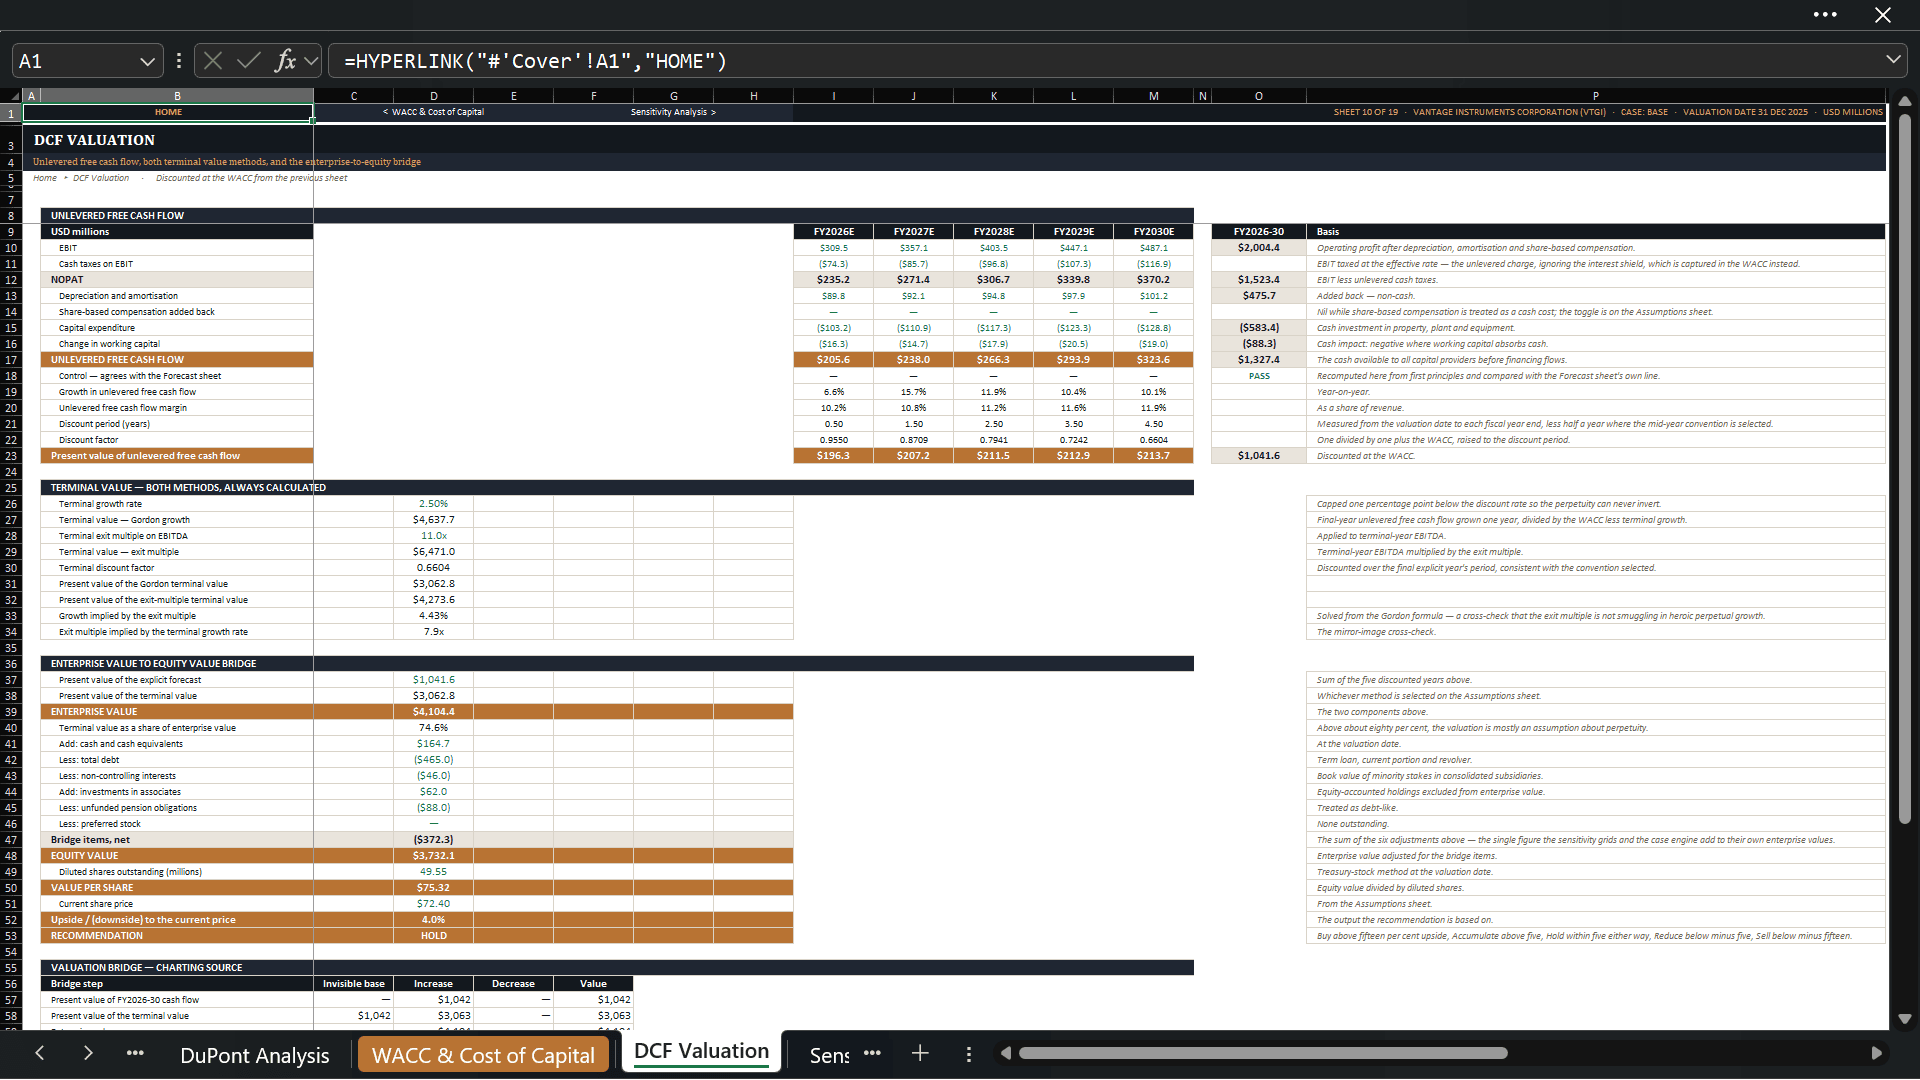
The DCF converts operating forecasts into unlevered free cash flow using EBIT, cash taxes, depreciation and amortization, capital expenditure, and changes in net working capital. Forecast cash flows are discounted from the selected valuation date, with a toggle for mid-year or end-year convention.
Both principal terminal-value methods are calculated:
- Gordon Growth perpetuity
- Exit multiple on terminal-year EBITDA
The user can select the active method while retaining the alternative as a cross-check. The model also calculates the perpetual growth rate implied by the exit multiple and the exit multiple implied by the perpetual growth rate—useful tests for identifying inconsistent terminal assumptions.
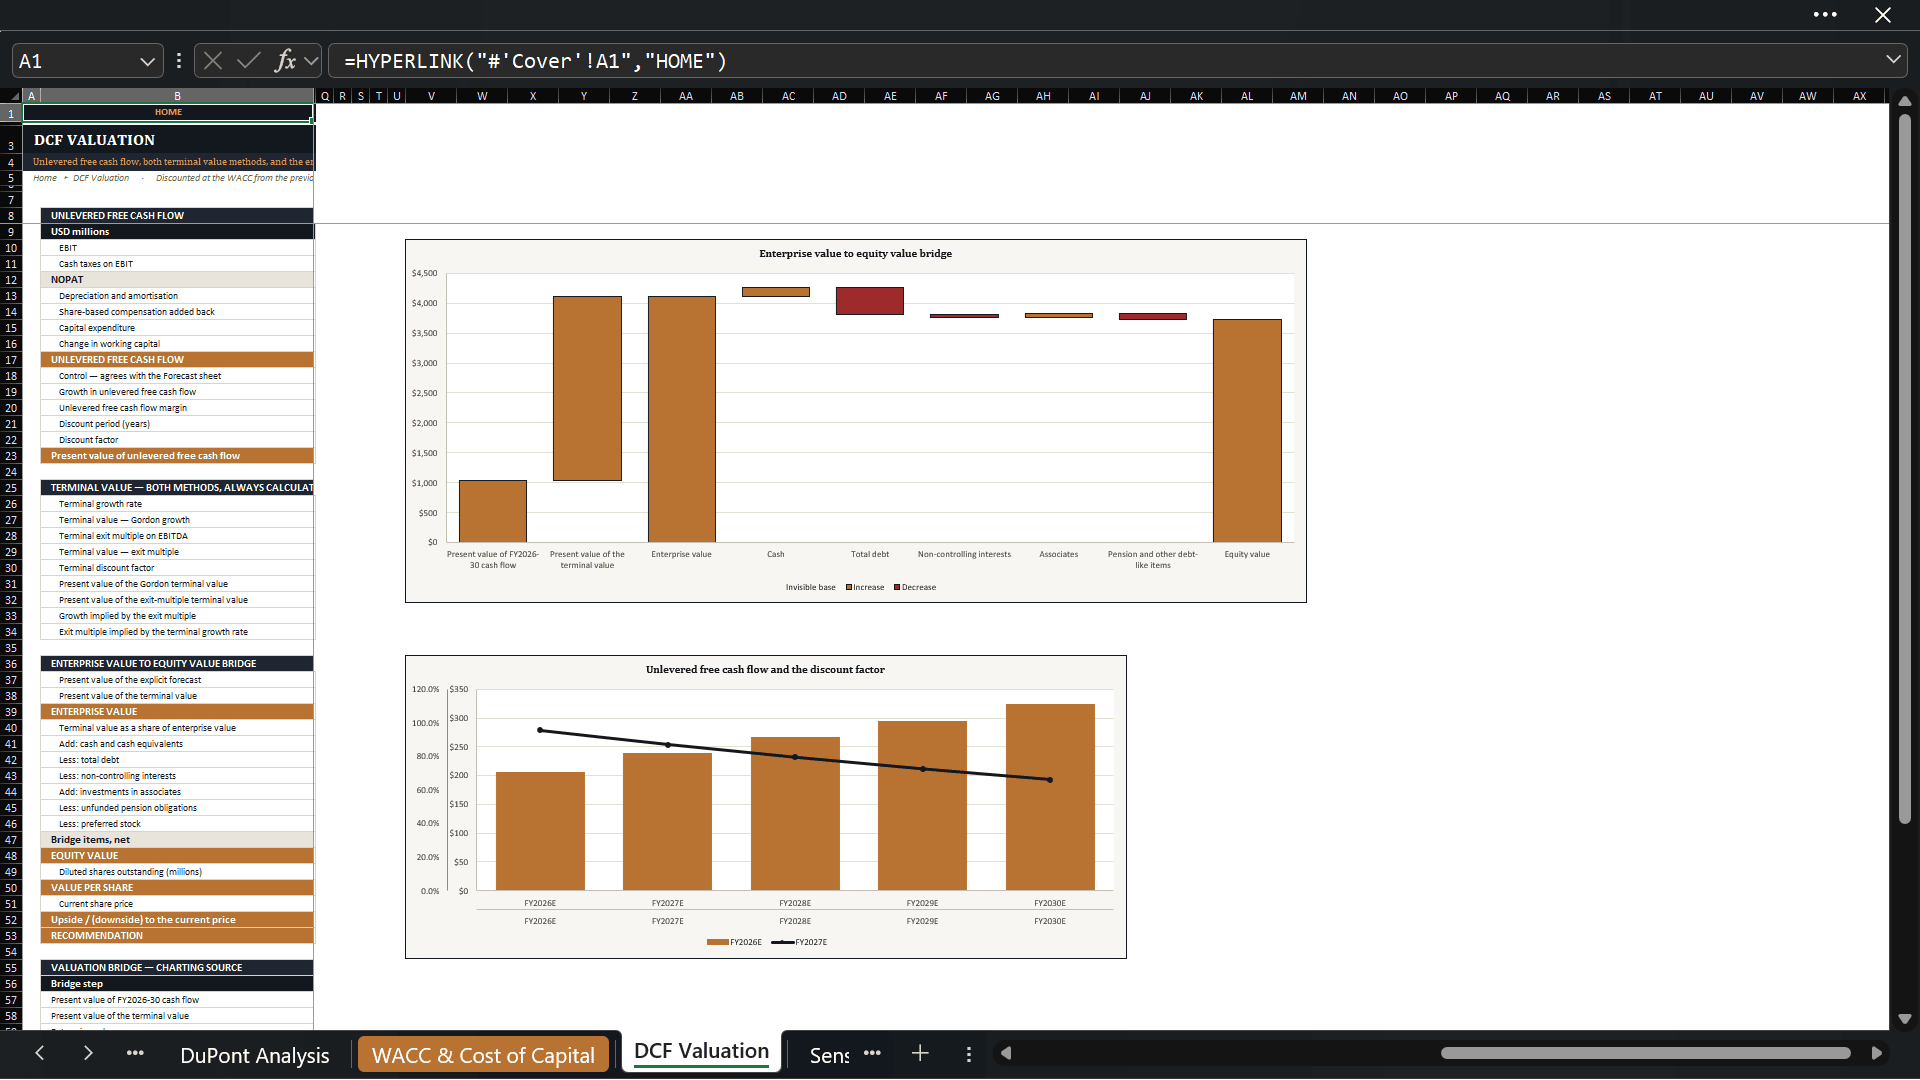
Enterprise value is converted to equity value through a clear bridge covering cash, debt, non-controlling interests, and other relevant claims before dividing by diluted shares. The resulting value per share, upside or downside, and formula-driven recommendation update automatically.
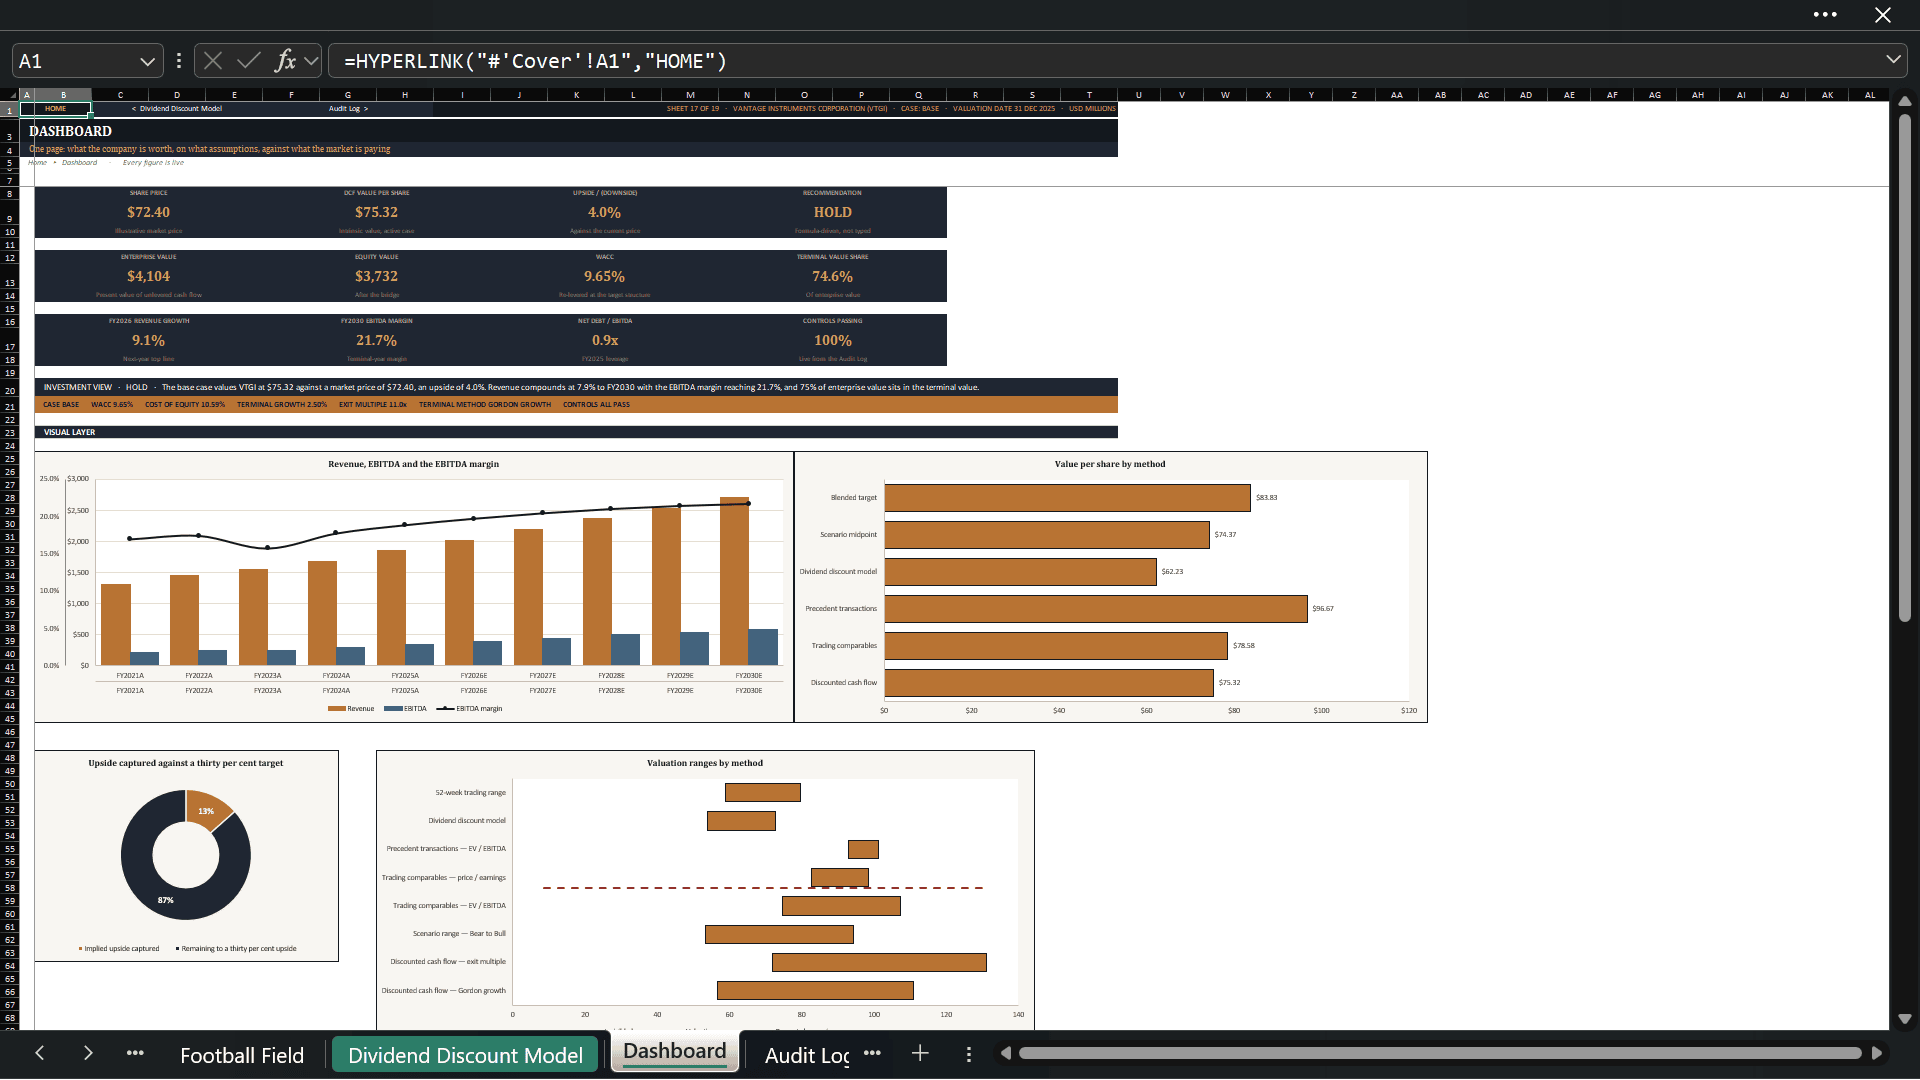
In the fictional Base Case, the sample DCF produces $75.32 per share versus a $72.40 illustrative market price, or approximately 4.0% upside, resulting in a formula-driven HOLD classification. These values demonstrate the mechanics and must be replaced with researched inputs before real-world use.
🧪 Sensitivity and Genuine Three-Case Analysis
The workbook helps the analyst understand valuation risk instead of relying on a single point estimate. It includes two-dimensional DCF sensitivity tables for key terminal assumptions and additional operating sensitivities.
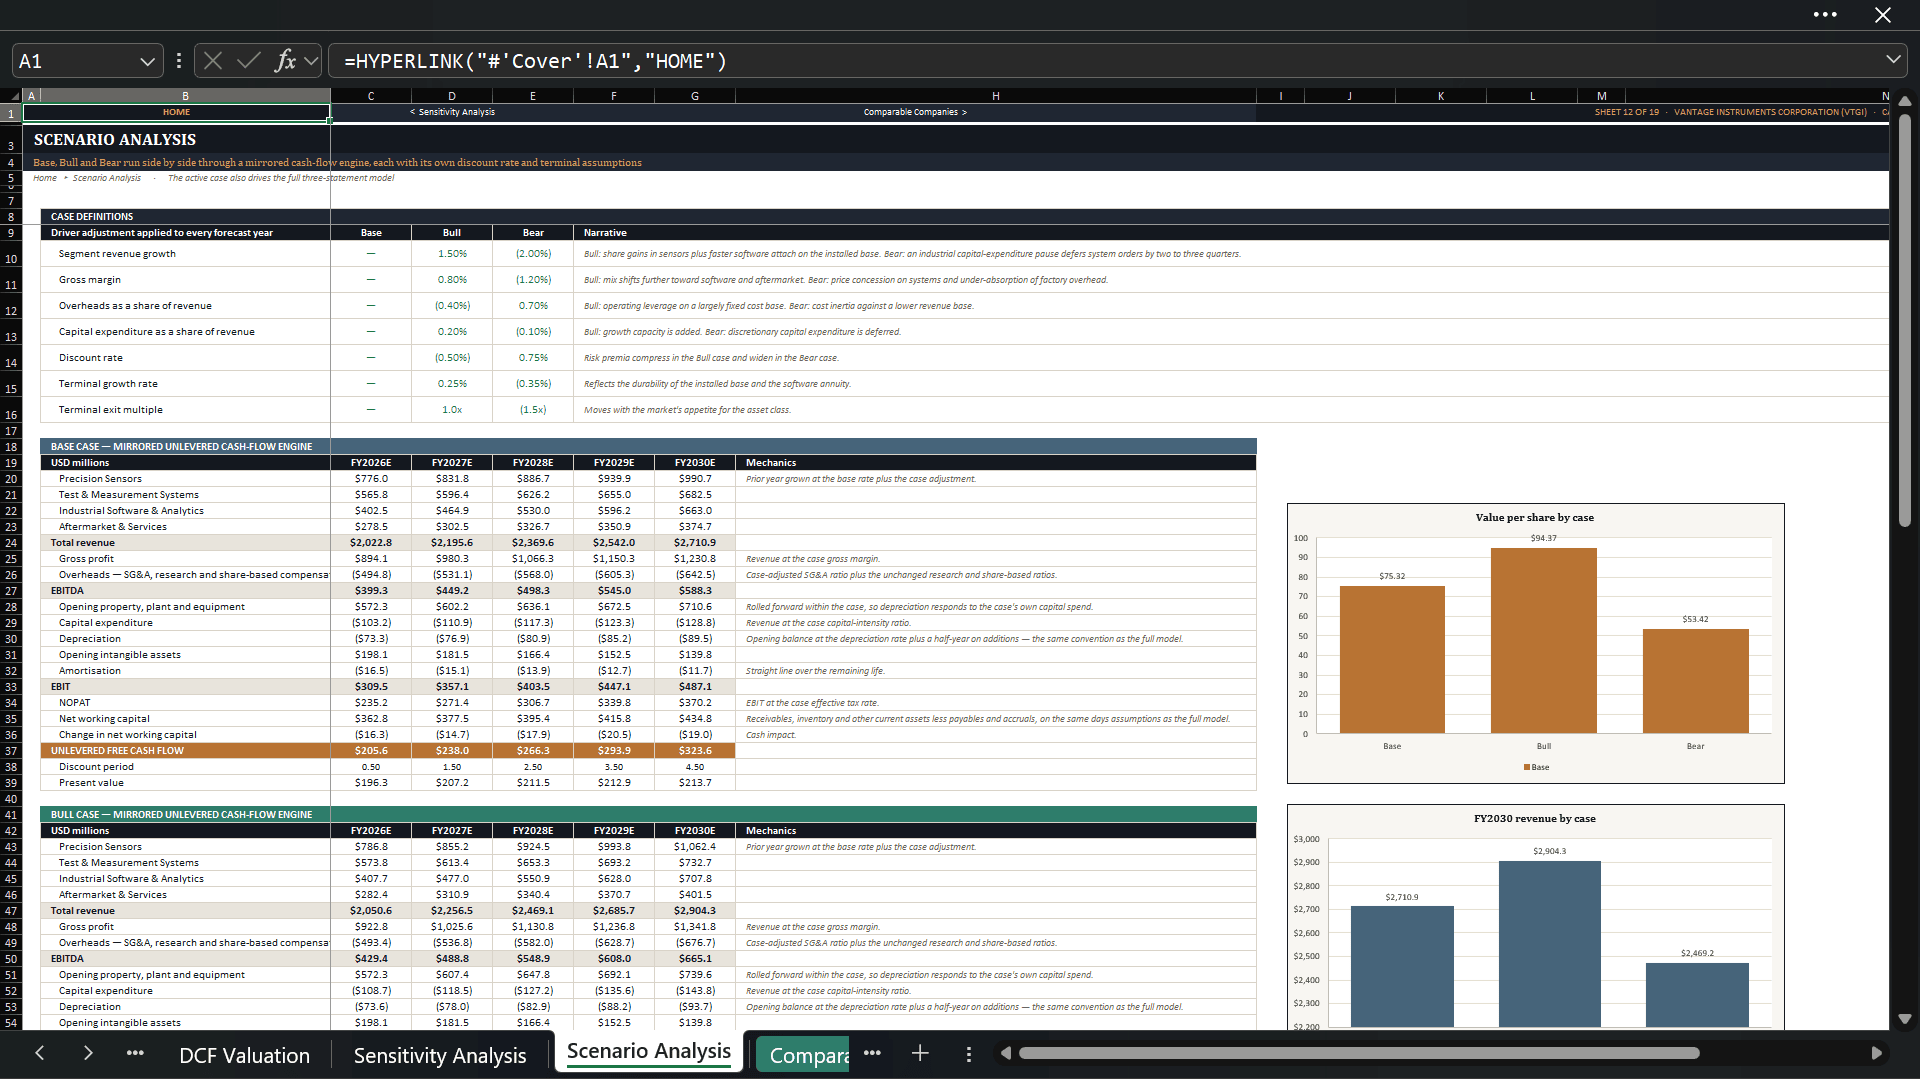
The Scenario Analysis sheet runs complete Base, Bull, and Bear cash-flow engines. In the sample data, the model calculates:
- Base Case: $75.32 per share
- Bull Case: $94.37 per share
- Bear Case: $53.42 per share
Each case reflects changes in operating performance, capital intensity, discount rate, and terminal assumptions. A live consistency control proves that the selected scenario reproduces the active three-statement model’s unlevered free cash flow.
🏢 Trading Comparables and Precedent Transactions
The Comparable Companies module includes eight fictional peer companies and supports analysis of:
- Enterprise value to revenue
- Enterprise value to EBITDA
- Enterprise value to EBIT
- Price to earnings
- Forward EBITDA and earnings multiples
- Growth, margin, and leverage statistics
- Median and quartile ranges
- Implied enterprise and equity values
- Implied value per share
The Precedent Transactions module contains eight fictional transactions announced over an illustrative thirty-six-month period. It analyzes revenue and EBITDA transaction multiples, target margins, acquisition premiums, quartiles, and implied value per share. Both approaches use the same enterprise-to-equity bridge as the DCF, improving comparability across methods.
💵 Multi-Stage Dividend Discount Model
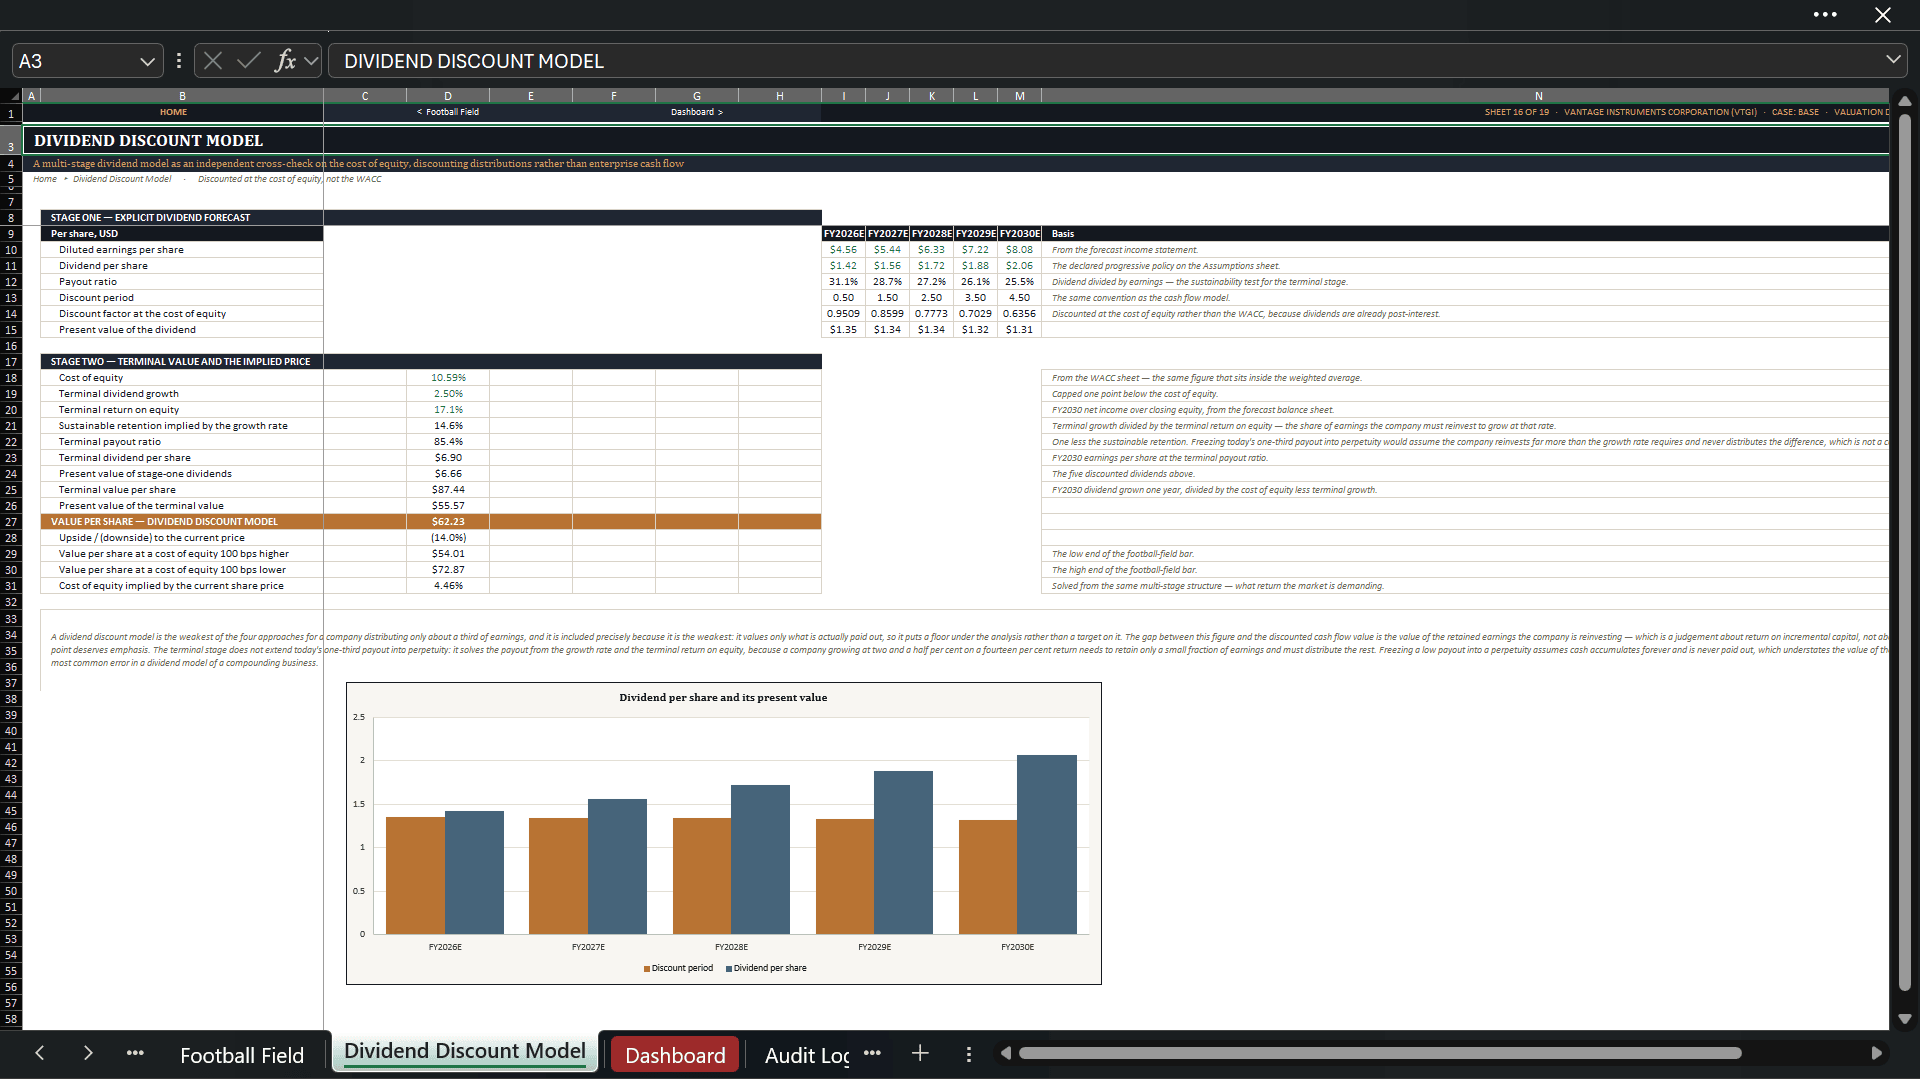
The dividend model provides an independent equity-value cross-check by discounting distributions at the cost of equity rather than the WACC. It includes five explicit forecast dividends, a terminal-growth stage, a terminal payout ratio linked to growth and return on equity, value per share, upside or downside, and a valuation range based on the cost of equity plus or minus 100 basis points.
The DDM is intentionally treated as a supporting floor for a company retaining and reinvesting a meaningful portion of earnings. This avoids presenting dividend value as interchangeable with enterprise free-cash-flow value.
📊 Football Field and Executive Dashboard
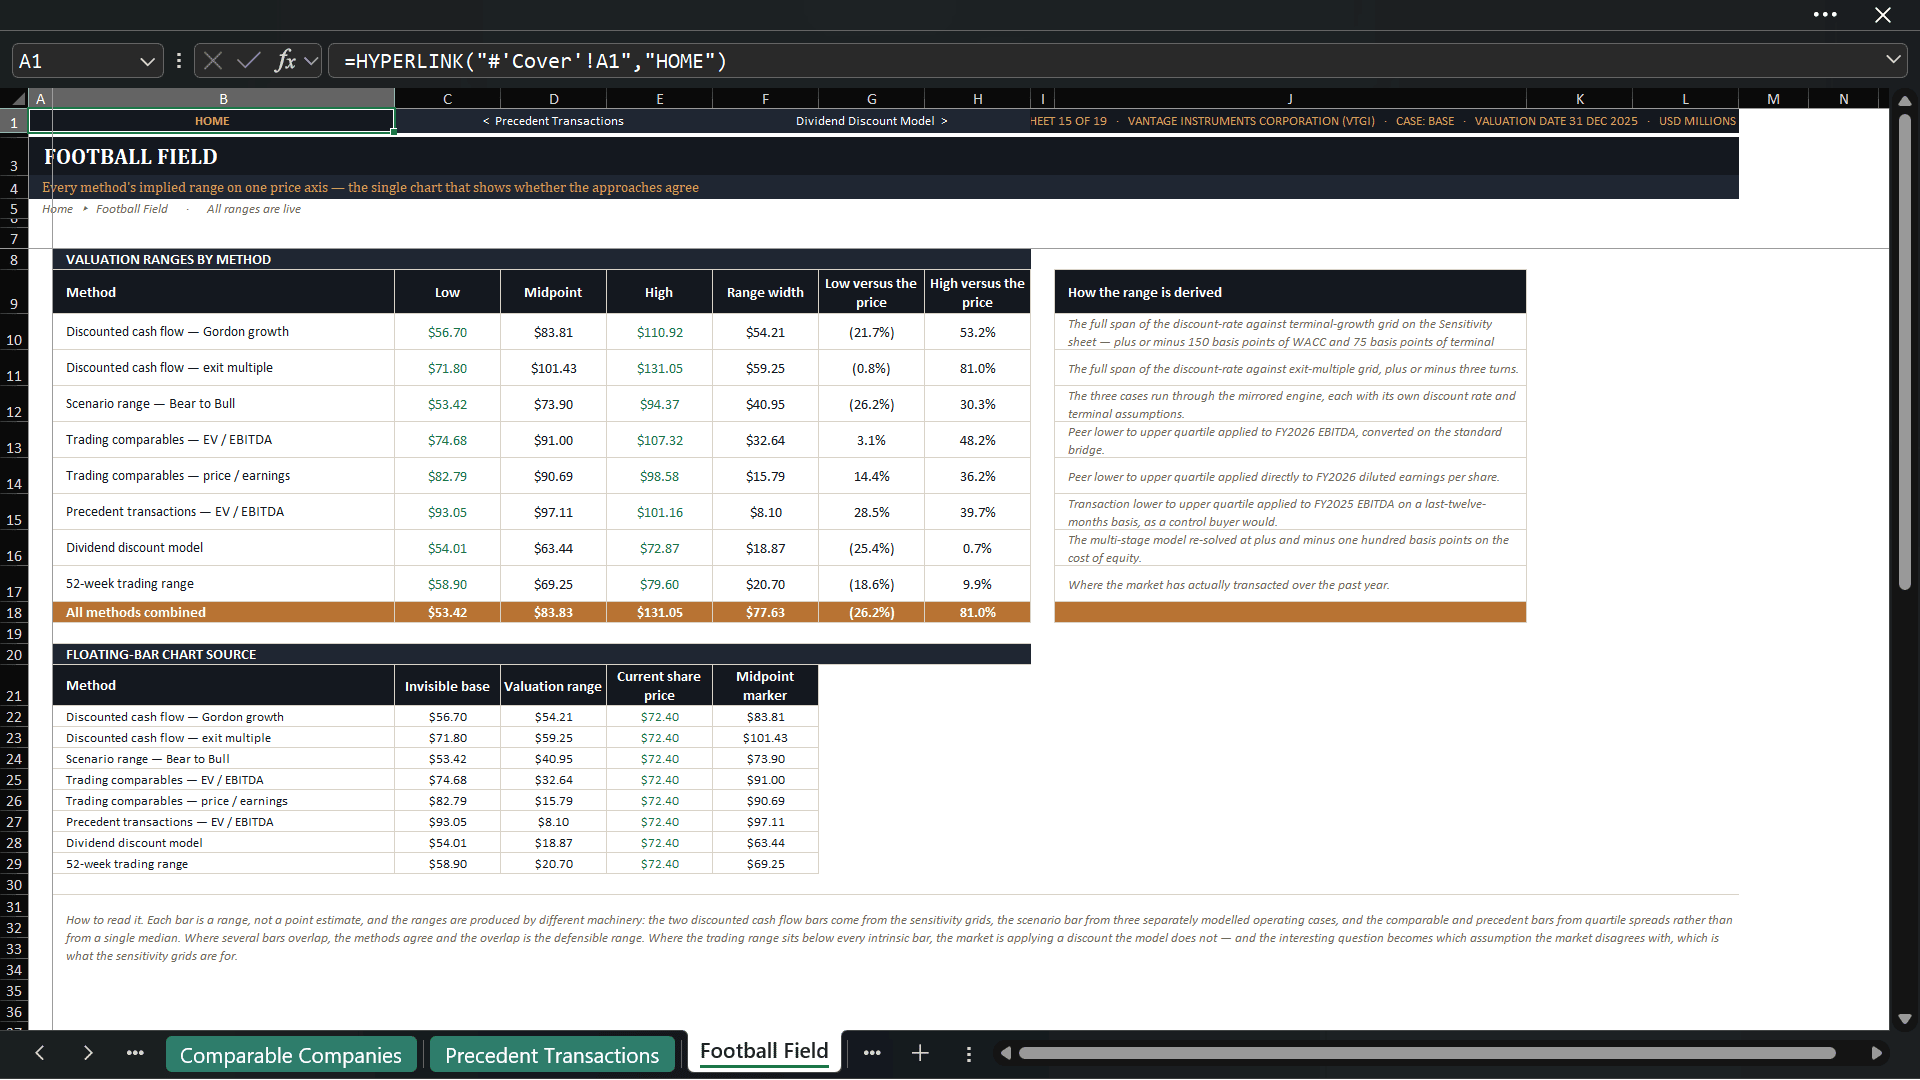
The Football Field consolidates valuation ranges from:
- DCF using Gordon Growth
- DCF using an exit multiple
- Bear-to-Bull scenarios
- Trading comparables using EV/EBITDA
- Trading comparables using P/E
- Precedent transactions
- Dividend discount sensitivities
- The illustrative 52-week share-price range
An executive dashboard summarizes the share price, DCF value per share, upside or downside, recommendation, case selection, WACC, cost of equity, terminal assumptions, operating forecast, valuation-method comparison, and control status. The workbook contains 23 charts across the analysis, including trend, valuation-range, bridge, and diagnostic visuals.
✅ 28 Live Audit and Integrity Checks
The Audit Log monitors the integrity of the model with 28 formula-based checks. These cover balance-sheet balancing, cash-flow reconciliation, cash roll-forward, debt and share-count logic, scenario consistency, valuation bridges, football-field ranges, terminal assumptions, dashboard outputs, and other critical dependencies.
The supplied sample file reports all 28 controls passing with zero exceptions. Because the checks are live, they continue to help identify issues as users replace the assumptions and data.
🛠️ How to Use the Model
- Read the How to Use & Legend sheet and review the disclosures.
- Replace the fictional company, market, peer, and transaction inputs with researched data.
- Enter historical financial statements and opening balances.
- Set segment growth, margins, working capital, capital expenditure, financing, dividend, and share-count assumptions.
- Select the active Base, Bull, or Bear case.
- Review the linked forecast statements, ratios, and DuPont analysis.
- Validate the WACC inputs and target capital structure.
- Select the DCF convention and terminal method.
- Review sensitivities, scenario values, comparables, precedents, the DDM, and the football field.
- Confirm that the Audit Log is fully passing before using or presenting any conclusion.
🎯 Who Should Buy This Model?
This workbook is designed for:
- Equity research analysts
- Investment analysts and portfolio professionals
- Corporate finance and valuation teams
- Investment-banking and transaction-advisory professionals
- Private-equity and venture-capital analysts evaluating mature operating businesses
- Finance students, educators, and modeling trainees
- Business owners and consultants preparing decision-support analysis
🚫 When Is It Not the Right Fit?
The workbook is not designed for banks, insurers, funds, pre-revenue startups, project-finance vehicles, real estate assets, or highly regulated financial institutions without material restructuring. It does not automatically download market data, perform trade execution, guarantee investment outcomes, or replace professional due diligence.
The forecast is annual and does not explicitly model intra-year seasonality. Taxes use an effective-rate approach rather than a full deferred-tax and loss-carryforward schedule. Acquisitions, disposals, foreign-currency translation, and complex equity issuances are not modeled as standalone transaction modules.
📦 Delivery and Technical Details
- One fully editable Microsoft Excel workbook
- Approximate file size: 0.22 MB
- 19 worksheets
- 23 charts
- 28 live audit checks
- No macros or VBA
- No external links
- No external data connections
- No locked black-box calculations
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.