
0 ITEMS

Mobile Notary Financial Model Excel Template
The Mobile Notary Financial Model helps turn a mobile notary business idea into a structured, editable financial forecast that can be used for planning, budgeting, funding preparation, and day-to-day decision-making. Instead of starting with a blank spreadsheet, users can work from a ready-to-use model designed around the economics of notary services, including standard notarizations, mobile appointments, loan signings, premium after-hours work, customer acquisition, travel-related costs, and operating capacity. It gives entrepreneurs, founders, consultants, analysts, and business owners a practical way to estimate revenue potential, startup costs, operating expenses, cash flow, profitability, and the level of capital required to launch or grow. This template is especially useful for anyone preparing a mobile notary business plan, applying for financing, evaluating a new service territory, or testing whether the numbers support a full-time or part-time notary operation. Users can customize revenue assumptions, pricing, customer volume, marketing spend, payroll, and cost drivers to reflect their own market and service mix. The model helps connect commercial assumptions with financial outputs, making it easier to understand how changes in appointment volume, customer acquisition cost, staffing, vehicle expenses, and service pricing affect future performance. The Mobile Notary Financial Model includes a five-year forecasting structure that supports professional financial planning across income, expenses, cash flow, and profitability. It helps users evaluate whether the business can cover payroll and operating expenses, when it may reach break-even analysis milestones, and how much cash may be needed during early growth periods. By showing the relationship between startup investment, monthly operating costs, service revenue, and future returns, the template supports clearer decisions before committing money, time, or resources. Built for both non-financial users and experienced planners, the template is designed to be fully customizable and presentation-ready. It can support internal planning, stakeholder discussions, lender submissions, investor conversations, and strategic reviews. Whether the goal is to launch a new mobile notary service, expand an existing notary practice, improve pricing strategy, or create a more credible funding document, this financial model template provides a structured framework for forecasting, analyzing, and communicating the business case with confidence.
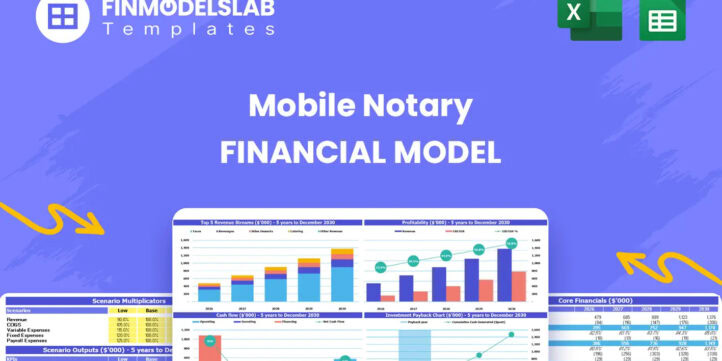


Financial Model Overview
The Mobile Notary Financial Model is a ready-to-use financial model template designed to help entrepreneurs, founders, business owners, consultants, and analysts plan the economics of a mobile notary business in a structured and professional way.
A mobile notary operation depends on more than simply completing appointments, because the business must balance appointment volume, pricing, service mix, customer acquisition, travel costs, payroll, equipment, insurance, technology, and available cash. This template brings those moving parts into one organized forecasting tool so users can estimate revenue, understand startup funding needs, track operating expenses, analyze cash flow, evaluate profitability, and prepare investor-ready or lender-ready financial outputs.
It is built to support up to five years of projections and can be customized for a new startup, an independent notary expanding into mobile services, a loan signing agent building a full-time business, or an established operator planning additional service areas. By using pre-structured assumptions and formulas, the model helps replace guesswork with a planning process that is easier to update, explain, and present.
All-in-One Dashboard
The all-in-one dashboard gives users a central view of the most important inputs and outputs in the Mobile Notary Financial Model. This component is designed to make the model easier to navigate by bringing together core assumptions such as appointment volume, service pricing, customer acquisition activity, startup investment, operating costs, payroll plans, and growth expectations, then linking those assumptions to headline outputs such as revenue, EBITDA, cash flow, profit margins, funding needs, and return metrics.
For a mobile notary business, this is especially valuable because many financial outcomes depend on small operational assumptions, including how many appointments are completed per month, how much is charged for mobile services, how much is spent on marketing, and how efficiently the owner or team can travel between clients.
The dashboard helps users quickly see whether the plan is financially balanced, whether cash reserves appear sufficient, and whether projected profitability is improving over time. It can be used as a management view for internal planning, a discussion tool during investor or lender conversations, and a practical starting point for reviewing the overall business case before going deeper into the detailed schedules.
Low Base High Scenario Analysis
The low, base, and high scenario analysis component helps users evaluate how the mobile notary business might perform under different operating conditions. Instead of relying on a single forecast, this section allows users to compare outcomes when assumptions change, such as customer acquisition rates, service pricing, repeat customer activity, marketing efficiency, travel costs, staffing timing, or demand for loan signings and after-hours appointments.
The low scenario can be used to stress-test the business if demand grows more slowly, customer acquisition costs remain high, or expenses rise faster than expected. The base scenario can represent the most realistic operating plan, while the high scenario can show upside potential if marketing performs well, premium services gain traction, or appointment volume scales efficiently. Outputs may include changes in revenue, gross profit, EBITDA, cash balance, funding requirements, payback period, and profitability.
This component is useful for planning and decision-making because mobile notary revenue can vary by location, referral network, customer mix, and market conditions. By comparing multiple cases, users can set more realistic goals, understand downside risk, identify the assumptions that matter most, and prepare more credible conversations with lenders, investors, or internal stakeholders.
Professional Charts
The professional charts component converts the financial forecast into clear visual reports that are easier to understand and present. A spreadsheet with detailed numbers is useful for analysis, but charts help communicate the story behind the business plan, especially when explaining growth, profitability, cash flow, expense trends, or investment needs to stakeholders.
In the Mobile Notary Financial Model, charts may visualize revenue growth by year, monthly cash balance movement, EBITDA improvement, operating expense categories, service mix changes, customer growth, margin development, and other performance indicators. These visuals help users identify trends that may not be obvious from raw numbers alone, such as periods when cash becomes tight, when revenue begins to scale, or when fixed costs become more efficient as appointment volume grows.
For a mobile notary business, charts are especially helpful because the model may include several revenue streams, including standard notarizations, mobile appointments, loan signings, and after-hours services. A visual presentation can show which areas are driving the forecast and where operational focus may be needed. This component supports business planning, funding preparation, management reviews, and pitch discussions by making the financial case more polished, accessible, and presentation-ready.
ROE Components and DuPont Analysis
The ROE components and DuPont analysis section helps users understand the drivers behind return on equity rather than looking at a single return metric in isolation. For a mobile notary business, return on equity can be influenced by profit margin, asset efficiency, and the way the business is funded, including the level of owner investment, debt, retained earnings, and asset requirements such as a vehicle, technology, equipment, and working capital.
This component breaks return performance into more meaningful parts so users can see whether returns are being limited by low margins, insufficient revenue volume, high operating costs, underused assets, or the financing structure of the business. Inputs may include net income, revenue, total assets, equity, debt assumptions, and balance sheet projections. Outputs help explain how efficiently the business converts sales into profit, how effectively it uses its asset base, and how the equity structure affects owner or investor returns.
This is useful for strategic decision-making because a mobile notary operator may improve financial returns by increasing premium service pricing, raising appointment density, controlling travel expenses, improving marketing conversion, or delaying unnecessary asset purchases. DuPont-style analysis adds depth to the model and makes the financial plan more useful for users who need to evaluate return quality, not just revenue growth.
Revenue Inputs
The revenue inputs component is where users define the commercial assumptions that drive the financial forecast. For a mobile notary business, revenue is usually built from the number of customers or appointments, the mix of notary services, pricing by service type, growth in demand, customer acquisition efficiency, and the share of higher-value services such as loan signings and after-hours appointments.
This section may include assumptions for standard notarizations, mobile service appointments, loan signing services, after-hours or urgent work, average pricing, billable hours, appointment frequency, marketing spend, and customer acquisition cost. By organizing these drivers clearly, the model helps users move beyond broad revenue guesses and build projections from the actual mechanics of the business. Outputs from this section flow into the revenue forecast, gross margin analysis, cash flow forecast, profitability statements, and scenario comparisons.
This is useful because small pricing or volume changes can materially affect the viability of a mobile notary operation. Users can test whether their planned service mix generates enough income to cover vehicle expenses, marketing, insurance, technology, payroll, and administrative costs. The revenue inputs also support more defensible business plans because assumptions can be explained in practical terms that lenders and investors understand.
Bank-Ready Reports
The bank-ready reports component organizes the financial outputs in a format that supports lender reviews, funding applications, stakeholder presentations, and formal business planning. Mobile notary entrepreneurs often need to show more than an idea; they need to explain how much capital is required, how the funds will be used, how the business will generate cash, and whether projected income can support ongoing expenses and any debt obligations.
This section may include projected profit and loss statements, cash flow forecasts, balance sheet summaries, debt schedules, funding requirements, repayment assumptions, and key ratios that banks or financing partners commonly review. Inputs from the model, including revenue assumptions, startup costs, payroll, operating expenses, loan amounts, interest rates, and working capital needs, flow into these reports automatically. The resulting outputs help users present a more complete and credible financial case.
This is useful for a mobile notary business because lenders may want to see whether early cash flow is sufficient, whether the startup investment is reasonable, and whether the business can sustain operations during the ramp-up period. Bank-ready reporting saves time, improves presentation quality, and helps users approach financing discussions with organized numbers instead of disconnected estimates.
Revenue Breakdown
The revenue breakdown component provides a detailed view of how different service lines contribute to total income. A mobile notary business may earn revenue from several sources, and each one can have a different price point, margin profile, customer acquisition path, and operational requirement. Standard notarizations may create steady demand but lower average transaction value, while mobile services may command higher fees because of travel convenience.
Loan signings may offer higher-value opportunities through real estate, mortgage, and title-related work, while after-hours services may generate premium pricing due to urgency and availability. This component helps users separate those revenue streams and understand how the business mix changes over time. Inputs may include pricing by service, appointment volume, service share, growth rates, seasonality, customer conversion, and expected demand by category. Outputs can show revenue by service type, percentage contribution to total sales, year-over-year growth, and the impact of shifting toward higher-margin or higher-value services.
This is useful for planning because it helps users identify which services deserve marketing focus, which offerings may support profitability fastest, and whether the forecast depends too heavily on one type of demand. A detailed revenue breakdown also makes the financial model more transparent for investors, lenders, advisors, and business partners.
KPI Dashboard
The KPI dashboard component tracks the performance metrics that matter most for a mobile notary business and gives users a practical way to compare projected results against operational targets. While the financial statements show revenue, expenses, cash flow, and profit, key performance indicators help explain why those results occur.
This section may include metrics such as customer acquisition cost, number of customers, appointments completed, average revenue per appointment, service mix, gross margin, EBITDA margin, cash runway, payroll as a percentage of revenue, marketing efficiency, break-even progress, and return metrics. Inputs are drawn from the assumptions and financial statements, while outputs are displayed in a way that supports quick review and ongoing decision-making.
For example, if customer acquisition cost is rising while average revenue per customer is flat, the business may need to adjust marketing channels, improve referral strategies, or focus on higher-value loan signing and after-hours services. If payroll grows faster than revenue, staffing plans may need to be delayed or optimized. The KPI dashboard is useful for founders, operators, consultants, and analysts because it translates the financial model into actionable business signals. It supports performance tracking, planning meetings, investor updates, and operational decisions throughout the life of the business.
Startup Costs and Funding Requirements
The startup costs and funding requirements component helps users estimate how much capital is needed before the mobile notary business can operate smoothly and reach stable revenue. A mobile notary startup may require investment in a vehicle or vehicle setup, technology, laptops or tablets, website development, booking tools, business registration, notary supplies, insurance, marketing, training, certifications, office setup, working capital, and early operating reserves.
This section allows users to organize one-time launch expenses separately from recurring monthly costs, which is important because startup costs affect the initial funding requirement while ongoing expenses affect cash flow and profitability. Inputs may include cost amounts, payment timing, financing assumptions, owner contribution, loan proceeds, and contingency reserves. Outputs may include total startup investment, funds needed before launch, cash runway, use of funds, and the level of financing required to avoid a cash shortfall during the ramp-up period.
This component is useful for planning because many service businesses underestimate early cash needs, especially when revenue takes time to build through marketing, referrals, and repeat customers. By documenting startup costs clearly, users can prepare stronger funding requests, make more informed launch decisions, and avoid undercapitalizing the business from the beginning.
Break-Even Analysis
The break-even analysis component helps users understand when the mobile notary business may generate enough revenue to cover its costs and move toward sustainable profitability. Break-even can be measured on a monthly operating basis, where revenue covers fixed and variable operating expenses, or on a cumulative basis, where the business has recovered its startup investment and earlier losses.
Inputs may include service pricing, appointment volume, gross margins, payroll, marketing spend, vehicle expenses, insurance, software, administrative costs, startup investment, and financing assumptions. Outputs may include break-even month, break-even revenue level, required appointment volume, margin of safety, cumulative profit recovery, and the impact of changes in pricing or cost structure. This is especially useful for a mobile notary business because profitability often depends on building appointment density, improving marketing efficiency, and increasing the share of higher-value services over time.
Similar ProductsOther customers were also interested in...


 HenrySheykin
Monthly Recurring Revenue SaaS Financial Model Exc...
The SaaS Business Financial Model helps founders, entrepreneurs, consultants, analysts, and business... Read more
SaaS Application Freetrial Financial Model Excel T...
The SaaS Business Financial Model helps founders, entrepreneurs, consultants, analysts, and business... Read more
SaaS Model Templates – Small Bundle Version
Since you are planning to start your very own SaaS business, you will certainly need to prepare a ... Read more
SaaS Model Templates – Big Bundle Version
Since you are planning to start your very own SaaS business, you will certainly need to prepare a ... Read more
 eFinancialModels
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more
 Jason Varner
SaaS Financial Model Bundle
This is a bundle of Financial Model Templates for SaaS businesses and their related sectors such as ... Read more
Website / App Financial Model (Recurring Revenue S...
A great tool to model out any recurring revenue service that acquires users through a website or app... Read more
General Mobile App – Economic Feasibility
If you or your organization is looking to launch a mobile app or any service that has an 'in-app' or... Read more
 Giorgos
Buy Now Pay Later (BNPL) Platform – 5 Year F...
Financial Model presenting an advanced 5-year financial plan for a startup BNPL Platform which provi... Read more
Online Payments Platform – 5 Year Financial Mode...
Financial Model providing an advanced 5-year financial plan for a startup Online Payments Platform p... Read more
You must log in to submit a review.