
0 ITEMS

Bus Mass Transit Financial Model (Excel) | Concession, Farebox & Subsidy, DSCR Debt & Cost per KM
An institutional, lender grade Excel model for an urban bus operator or concession over the concession life. It builds the network (fleet, peak vehicle requirement, revenue and service kilometres, ridership ramp), then revenue from farebox plus a per vehicle kilometre subsidy or availability payment and ancillary income, so you can see who carries volume risk. It sculpts senior debt to a target DSCR, adds a debt service reserve, LLCR and PLCR and a fleet replacement reserve, reconciles traditional and reorganized statements to zero in every period, and reports project and equity IRR, coverage and cost per vehicle kilometre. All inputs are benchmarked to public ranges with no private data, and the workbook carries zero formula errors. A 31 page development and modelling guide is included.
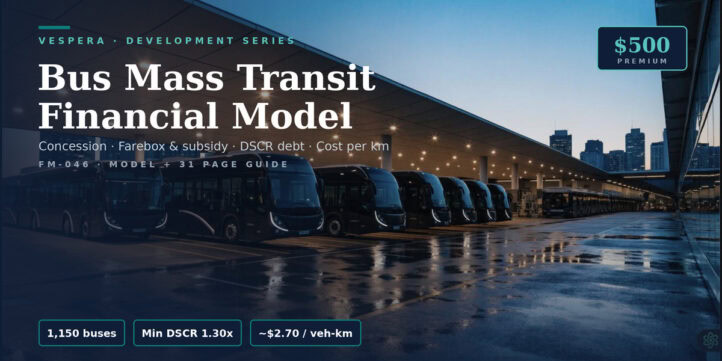
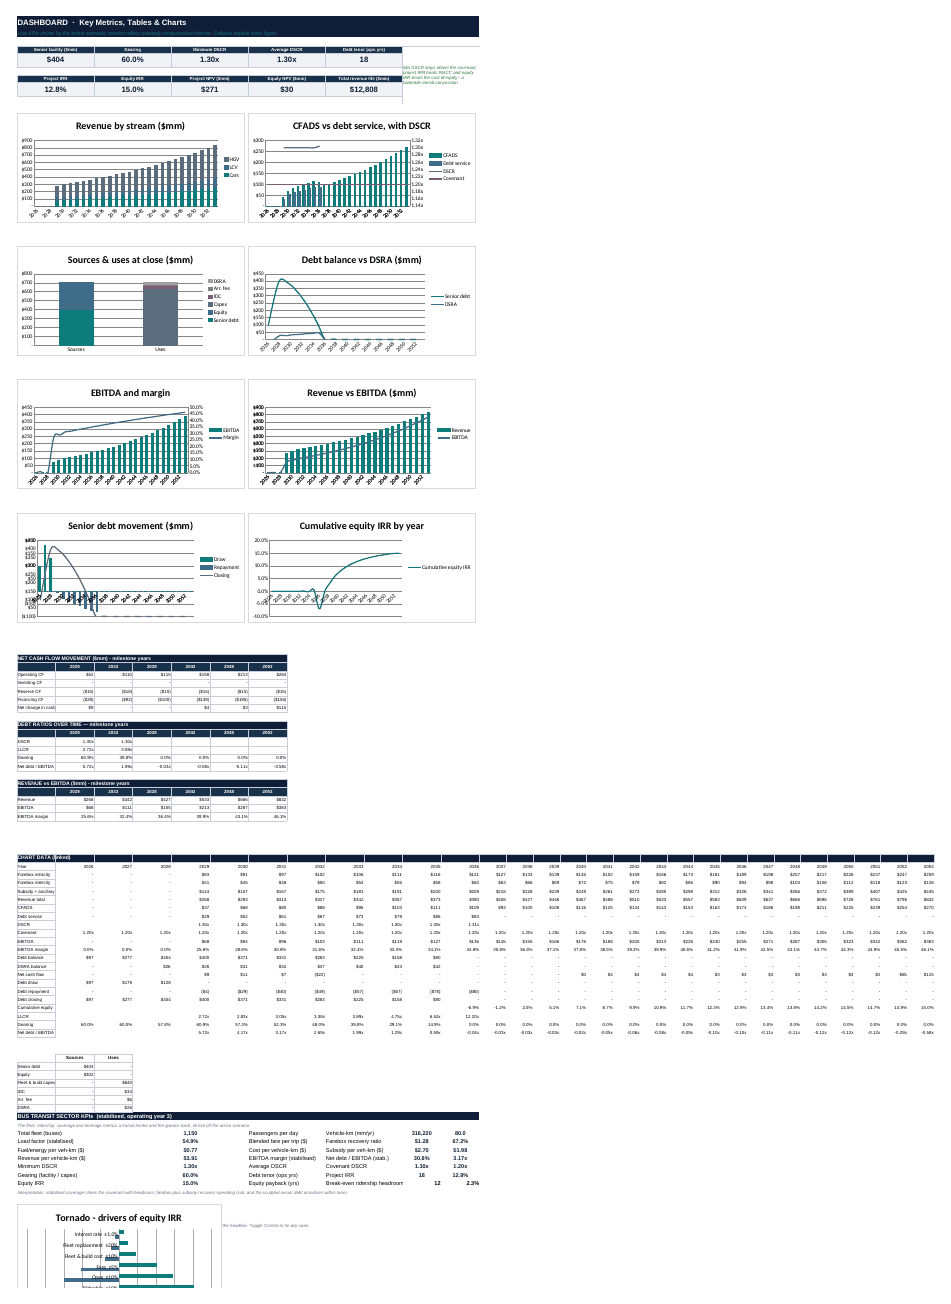
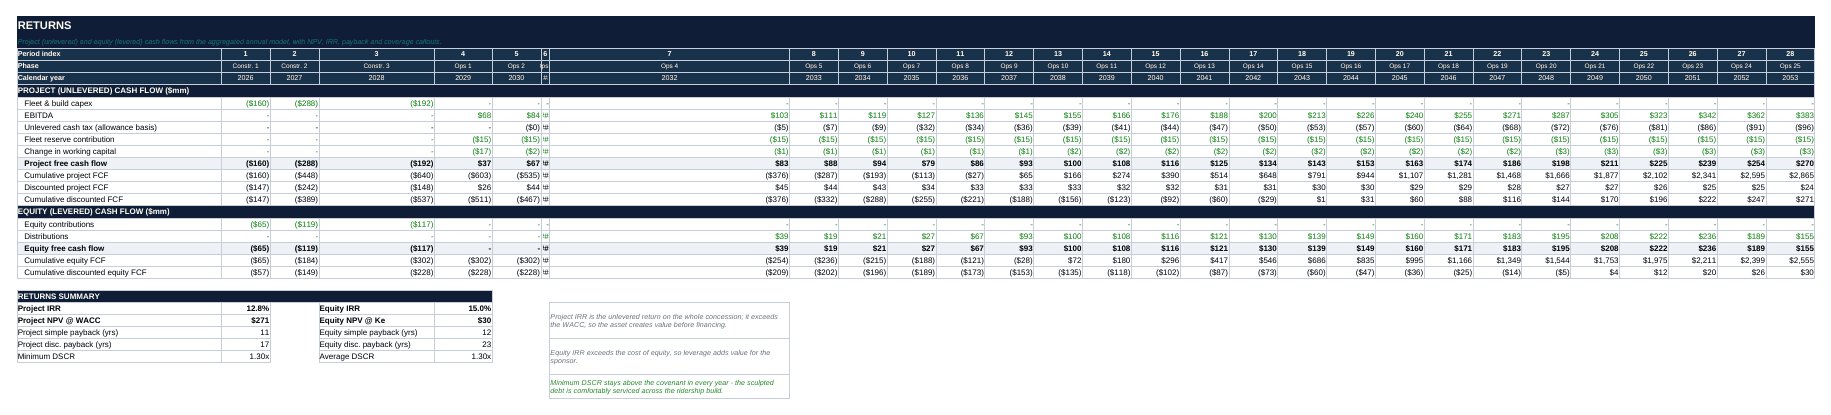
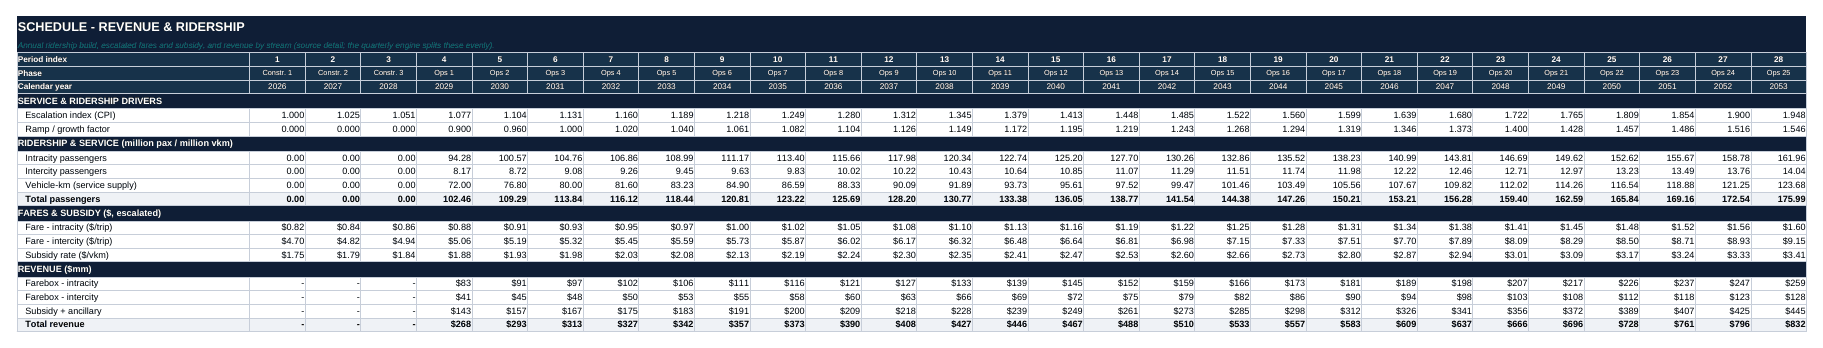
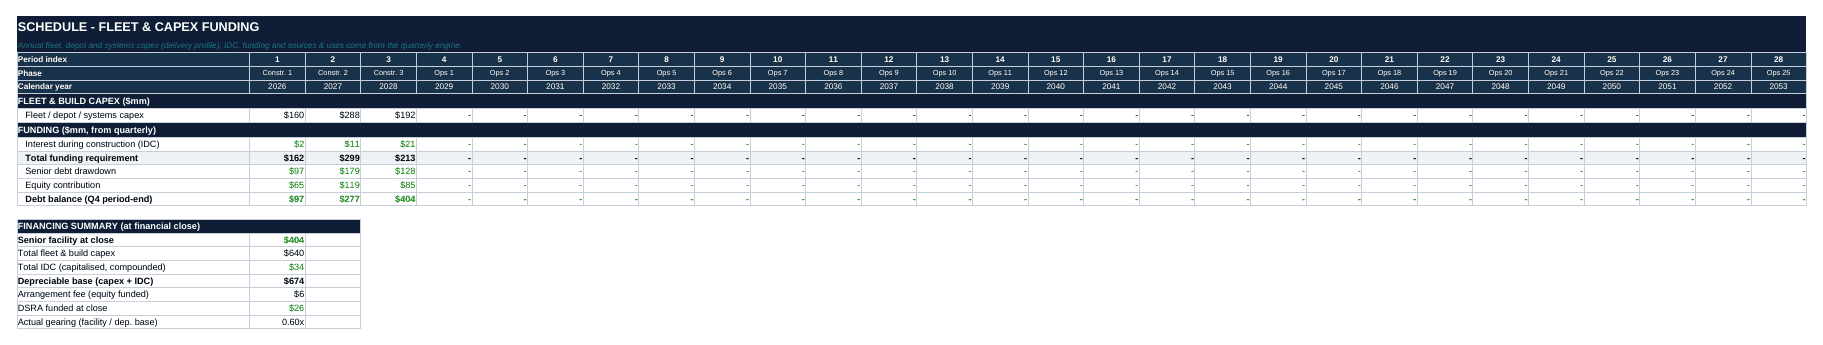
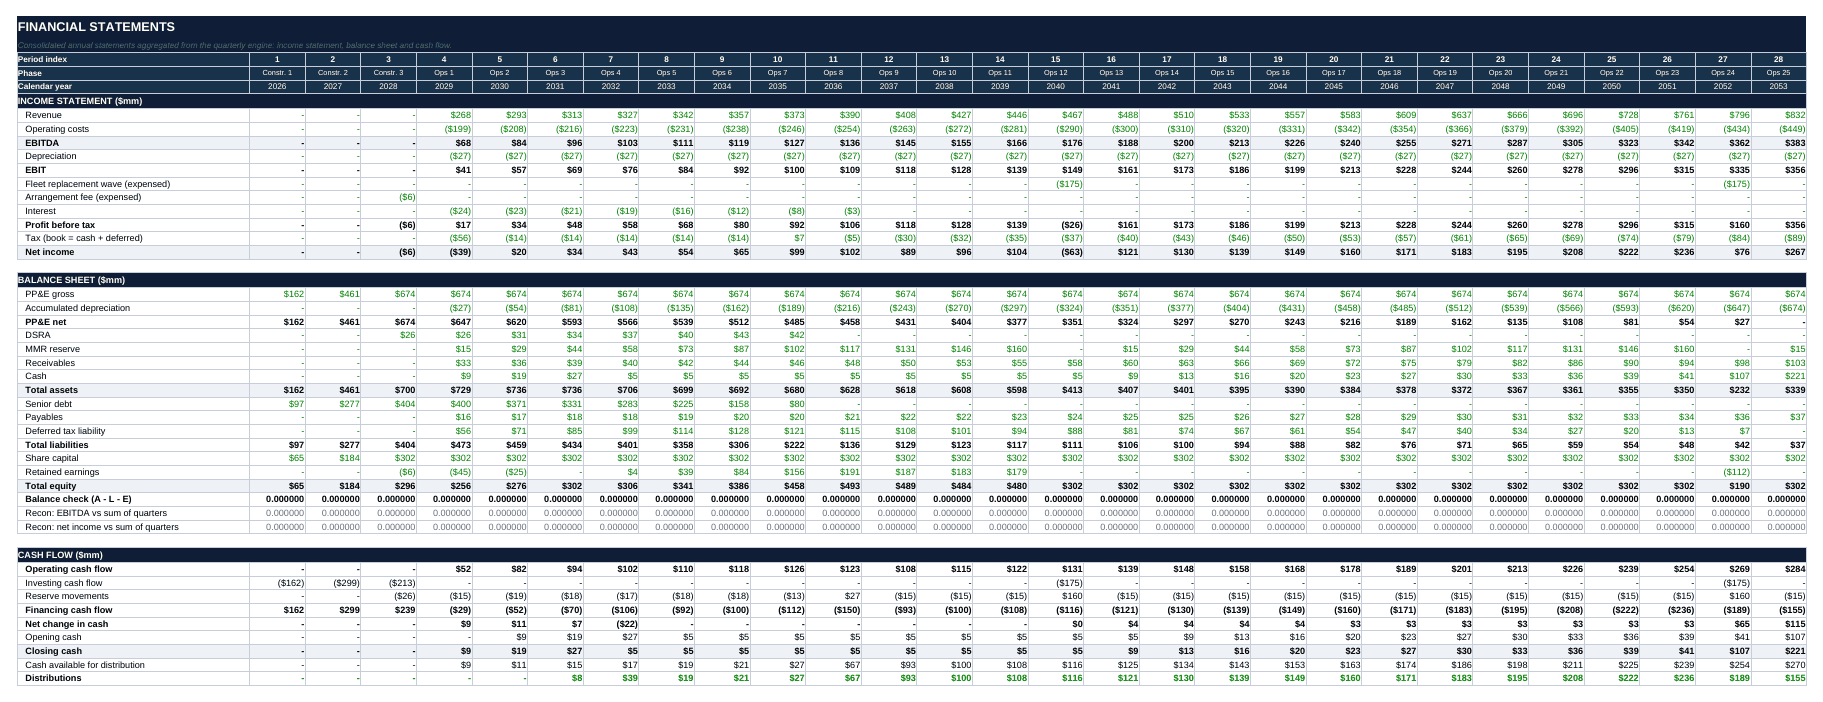
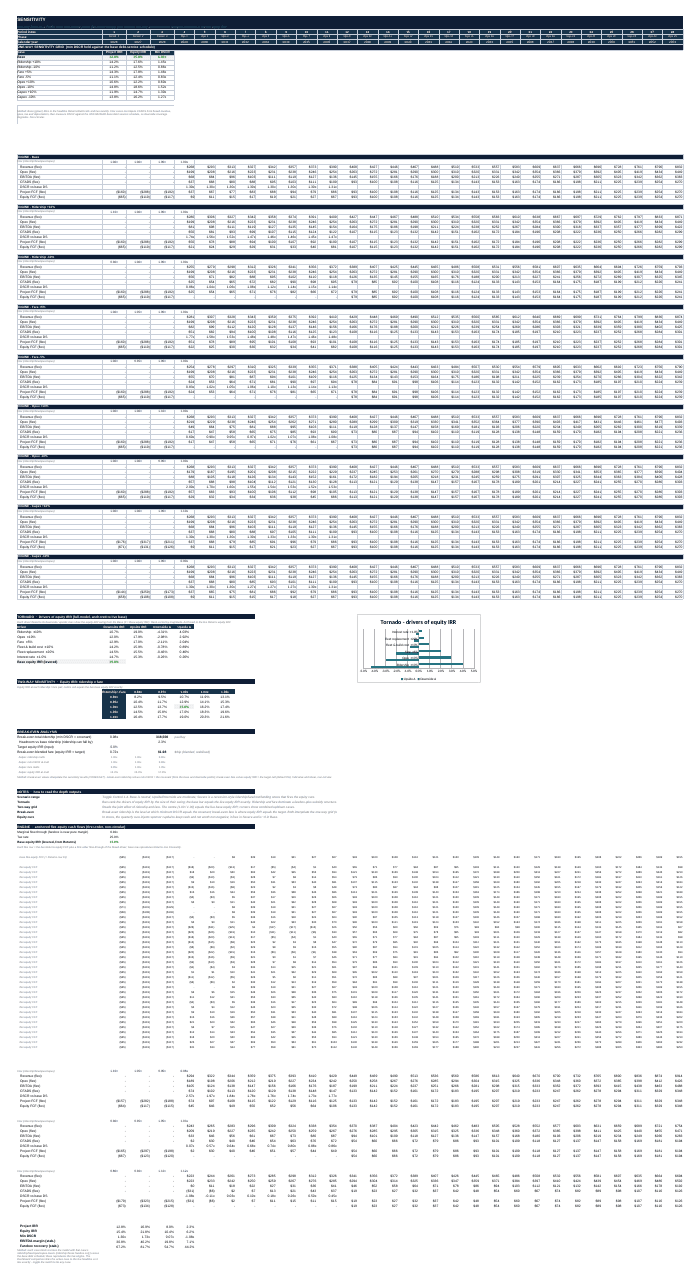
The Bus Mass Transit Financial Model is an institutional, lender-grade Excel model for an urban bus operator or concession, built on the same rigour as a full project-finance underwriting. It takes a fleet, a network and a revenue mechanism and turns them into a defensible investment case: revenue, coverage, returns and cost per vehicle-kilometre, over the concession life.
Bus mass transit is contracted infrastructure, and the central question is who carries revenue risk. I represent both sides of that: a farebox stream the operator earns from passengers, and a subsidy or availability payment the authority pays per vehicle-kilometre, indexed to inflation. That mix, close to a gross-cost concession at one extreme and a net-cost concession at the other, drives how stable the cash flow is and how much debt the operator can carry.
What is inside
- A network and service engine: fleet, peak vehicle requirement, revenue and service kilometres, and a ridership ramp.
- A revenue build combining farebox, a per vehicle-kilometre subsidy or availability payment, and ancillary income.
- A fleet and depot capital schedule with interest during construction and a fleet replacement reserve.
- DSCR-sculpted senior debt with a debt service reserve, LLCR and PLCR, and covenant headroom.
- Traditional statements and reorganized statements (NOPLAT, invested capital, ROIC, economic profit) reconciled by three bridges that equal zero every period.
- Capital allowances and deferred tax, a minimum operating cash balance, and distributions limited to distributable reserves.
- Project and equity IRR, equity multiple, payback, minimum and average DSCR, LLCR, PLCR and cost per vehicle-kilometre.
- A four-case scenario manager, a tornado, a two-way sensitivity grid, break-even analysis and a sponsor equity cure, feeding a live dashboard.
Every calculation is formula-driven and transparent, with no macros. All inputs are illustrative and benchmarked to public industry ranges and clearly flagged; there is no reference to any specific city, authority, operator or private contract. The model is independently checked and carries zero formula errors. A 31-page development and modelling guide is included, covering network planning, depot and fleet, the concession and revenue mechanism, operations and fleet renewal, mapped to the model.
Who it is for: bus operators, transit authorities, concessionaires, sponsors, and infrastructure lenders sizing debt against a transit concession.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.