
0 ITEMS

Empower Your Finances: Personal Financial Planning Strategies
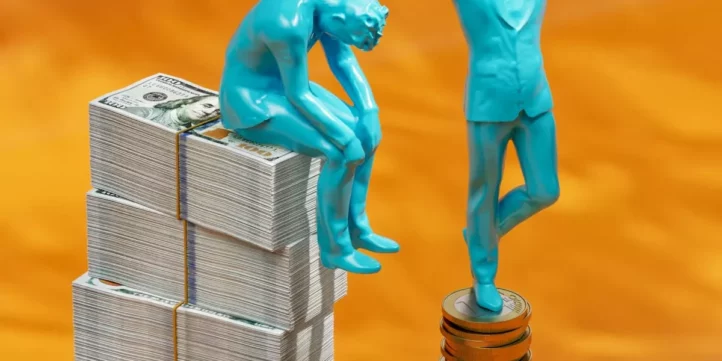
Effective personal financial planning helps you gain control over your money and work toward your financial goals.
- Creating a detailed budget tracks income, expenses, and savings, providing clarity on spending habits.
- Setting specific short-term and long-term financial goals guides your saving and investing strategies.
- Building an emergency fund with three to six months of living expenses offers a financial safety net.
- Investing wisely in diversified assets grows wealth over time while managing risk.
- Regularly monitoring and updating your financial plan ensures it remains aligned with changing circumstances.
By applying these methods, you can develop a solid financial foundation for a secure future.
The Importance of Setting Financial Goals
Setting clear and achievable personal finance goals is a crucial step in personal financial planning. Without goals, it’s challenging to measure your progress and stay motivated. When setting financial goals, it’s essential to identify both short-term and long-term objectives. Short-term goals may include saving for a vacation or paying off a credit card debt, while long-term goals can involve buying a house or planning for retirement. By defining your goals, you can create a financial plan that aligns with your aspirations, making it easier to make informed financial decisions.
Creating a Budget that Works for You
A budget is the foundation of any successful personal financial plan. It helps you track your income, expenses, and savings, ensuring that you have a clear understanding of where your money is going. Start by listing your monthly income and fixed expenses such as rent, utilities, and loan payments. Then, allocate a portion of your income towards savings and discretionary spending. Review your budget regularly and make adjustments as needed to ensure that you are meeting your financial goals. Remember, a budget should be flexible and tailored to your specific needs.
One useful budgeting strategy is the 50/30/20 rule, which suggests allocating 50% of your income towards necessities, 30% towards wants, and 20% towards savings and debt repayment. This approach allows you to prioritize your needs while still having room for enjoyment and saving for the future. Whichever budgeting method you choose, tracking your expenses diligently and being mindful of your spending habits will help you stay on track.
Building an Emergency Fund
Having an emergency fund is a crucial aspect of personal financial planning. Life is full of unexpected events, such as medical emergencies, car repairs, or sudden job loss. Having a financial safety net in the form of an emergency fund can help you navigate these situations without going into debt or relying on credit cards. Aim to save at least three to six months’ worth of living expenses in your emergency fund, which will act as a financial cushion during challenging times.
Consider automating your savings by setting up an automatic transfer from your checking account to your emergency fund every month. This way, you won’t even have to think about saving—it will happen automatically. Additionally, make sure your emergency fund is easily accessible, such as in a high-yield savings account, so you can quickly access the funds when needed.
Investing for Your Future
While saving money is essential, investing allows you to grow your wealth over the long term. Investing involves putting your money into different financial vehicles, such as stocks, bonds, real estate, or mutual funds, with the expectation of generating a return. Before diving into the world of investing, it’s crucial to educate yourself about different investment options, risk tolerance, and diversification.
Consider working with a financial advisor who can help you navigate the complexities of investing and tailor a strategy that aligns with your goals and risk tolerance. They can also assist in developing a well-diversified investment portfolio to minimize risks. Keep in mind that investing always carries some level of risk, so it’s important only to invest money that you can afford to leave untouched for an extended period.
Taking Control of Your Debt
Debt can be a significant burden on your finances, making it challenging to achieve your financial goals. As part of your personal financial planning, it’s crucial to develop a strategy for managing and reducing your debt. Start by listing all your debts, including credit card balances, student loans, and car loans. Prioritize paying off high-interest debts first while making sure to make minimum payments on other debts.
Consider different debt repayment strategies, such as the snowball method or the avalanche method. The snowball method involves paying off the smallest debts first while making minimum payments on the rest, giving you a sense of accomplishment and motivation as you eliminate debts one by one. In contrast, the avalanche method focuses on paying off debts with the highest interest rates first, helping you save more money in the long run. Choose the method that works best for you and stick to it consistently.
Protecting Your Assets and Insurance Needs
As you work on empowering your financial future, it’s vital to protect your assets and manage any risks. One crucial aspect of financial planning is insurance. Evaluate your insurance needs, such as auto insurance, health insurance, homeowners or renters insurance, and life insurance. Having adequate coverage can provide you with peace of mind and protect your financial well-being in the event of accidents, illness, or unforeseen circumstances.
Work with an insurance professional to assess your needs and choose the right coverage that fits your lifestyle and budget. Regularly review your policies to ensure they still meet your requirements as your circumstances change over time. Additionally, consider setting up a will or a trust to protect your assets and ensure that your wishes are carried out after your passing.
Key Takeaways
- Create a budget and track your expenses to understand where your money is going.
- Set financial goals and make a plan to achieve them.
- Save money regularly to build an emergency fund and for future investments.
- Invest wisely by diversifying your portfolio and seeking professional advice if needed.
- Stay informed about personal finance topics through reading books, attending seminars, or following reputable financial blogs.
Frequently Asked Questions
Welcome to our Frequently Asked Questions section on empowering your finances through personal financial planning strategies. If you’re looking for ways to take control of your finances and make informed decisions, you’ve come to the right place. In this section, we will address some common questions related to personal financial planning strategies and provide valuable insights to help you enhance your financial well-being.
1. How can personal financial planning strategies help me empower my finances?
Personal financial planning strategies serve as a roadmap to help you achieve your financial goals and secure a stable financial future. These strategies involve analyzing your current financial status, setting clear objectives, and identifying the steps needed to reach those objectives. By implementing effective financial planning strategies, you can gain control over your spending, save for the future, and make informed investment decisions.
Through financial planning, you can develop a deep understanding of your financial situation, which will enable you to make better financial decisions. It will also help you identify any potential risks or gaps in your finances, allowing you to take proactive measures to mitigate them. Overall, personal financial planning strategies empower you by giving you the tools and knowledge to make smart financial choices that align with your long-term goals.
2. What are some key components of personal financial planning strategies?
Personal financial planning strategies encompass several essential components that work together to help you achieve your financial goals. These components include:
Goal setting: Defining your short-term and long-term financial objectives, such as saving for retirement, purchasing a home, or paying off debt.
Budgeting: Creating a budget that outlines your income, expenses, and savings, allowing you to track and manage your money effectively.
Saving and investing: Establishing a saving plan and exploring investment options that align with your risk tolerance and long-term goals.
Debt management: Managing debt responsibly through strategies like debt consolidation, repayment plans, or negotiating lower interest rates.
Insurance: Evaluating your insurance needs to protect your finances from unexpected events, such as health issues, accidents, or property damage.
By integrating these components into your personal financial planning strategies, you can develop a comprehensive plan that brings you closer to financial empowerment.
3. How can I create a personal financial plan?
Creating a personal financial plan involves several steps to ensure you develop a strategy tailored to your individual goals and circumstances. Here are some key steps to get started:
1. Assess your current financial situation: Start by evaluating your income, expenses, assets, and liabilities. This will give you a clear understanding of where you stand financially.
2. Set financial goals: Identify your short-term and long-term financial goals, such as saving for emergencies, buying a house, or planning for retirement.
3. Develop a budget: Create a budget that outlines your income, expenses, and savings targets. This will help you allocate your funds effectively and track your progress.
4. Create an emergency fund: Set aside a portion of your income to build an emergency fund that covers at least three to six months’ worth of living expenses.
5. Explore investment options: Research and consider different investment vehicles, such as stocks, bonds, mutual funds, or real estate, based on your risk tolerance and financial goals.
6. Regularly review and adjust your plan: Financial planning is an ongoing process, so it’s important to regularly review your plan, make necessary adjustments, and stay informed about changes in your financial situation.
By following these steps and seeking guidance from a financial advisor, you can create a personal financial plan that empowers you to achieve your financial aspirations.
4. Why is it important to regularly monitor and update my financial plan?
Regularly monitoring and updating your financial plan is essential because your financial situation and goals may change over time. Life events, economic fluctuations, and personal milestones can impact your financial priorities and require adjustments to your plan. By staying proactive and up-to-date with your financial plan, you can ensure it remains relevant and effective.
Monitoring your plan allows you to track your progress towards your goals, identify any gaps or areas for improvement, and make necessary adjustments accordingly. It also gives you the opportunity to take advantage of new investment opportunities, evaluate changes in tax laws, and adapt to any unforeseen circumstances that may impact your financial stability. Ultimately, regularly monitoring and updating your financial plan ensures that it continues to align with your evolving needs and helps you stay on track towards financial empowerment.
5. How can I overcome financial challenges and setbacks through personal financial planning strategies?
Financial challenges and setbacks are a common part of life, but with the right personal financial planning strategies, you can navigate through them effectively. Here are some approaches to overcome financial challenges:
1. Identify the root cause: Analyze the underlying causes of your financial challenges. This could be overspending, lack of proper budgeting, or unexpected expenses.
2. Take immediate action: Once you’ve identified the root cause, take decisive steps to address the issue. This might involve cutting back on expenses, exploring additional income sources, or seeking professional advice.
3. Evaluate your financial plan: Review your financial plan and identify areas that need adjustment. Look for opportunities to save more, restructure debt, or reallocate funds to meet your current needs and goals.
4. Seek support and guidance: Consider consulting with a financial advisor who can provide expert guidance and help you develop a strategy to overcome challenges and create a more resilient financial plan.
5. Stay motivated and persistent: Overcoming financial challenges takes time and effort. Stay motivated, remain patient, and make consistent progress towards your goals. Every small step counts.
By implementing these strategies and remaining resilient, personal financial planning can help you overcome challenges and setbacks, ultimately empowering you to achieve financial success.
Empowered Planning: Your Personal Financial Strategy
Summary
Managing your money can be easier and more empowering than you think. By following some simple strategies, you can take control of your finances and achieve your goals.
Start by creating a budget, tracking your expenses, and setting financial goals. Remember to save and invest for the future, and always pay yourself first. Avoid unnecessary debt and be mindful of your spending habits. Finally, educate yourself about personal finance and seek professional advice when needed. With these steps, you can become financially empowered and secure a better future for yourself.

























You might also like:
- 10-Step Financial Planning Checklist for Smart Executives
- 5 Smart Ways To Manage Personal Finances In A Pandemic
- Achieve Financial Success By Knowing Your Business Plan Model
- The Essential Guide to Personal Finance 101
- Building a Monthly Budget – Using Monthly Budget Templates
- Creating a Budget Plan – Using the Best Excel Budget Template
- 10 Ideas to Increase Average Revenue Per User
- 12 Funding Sources for Businesses and Startups
- Financial Planning for Small Business Owners – Taking an SBA Loan
- Personal Budgets
- Investing
- Financial Planning
- Budgeting
- Saving Plans
- Financial Model Templates Easy to Use
- Startup Model Templates in Excel that can help your Business Grow
- Simple Budget Planner Template
- Monthly Budget Template (with Financial Statements)
- Cash Flow Analysis in Excel
- Financial Forecasting Models by eFinancialModels


