
0 ITEMS

Savings Bank Financial Model Excel Template
The Savings Bank Financial Model helps entrepreneurs, bank founders, consultants, analysts, and business planners build a structured financial forecast for a savings bank or community banking institution. Instead of relying on a generic spreadsheet, this financial model template is designed around the real drivers of banking performance, including deposit balances, loan portfolios, net interest income, funding costs, non-interest income, operating expenses, payroll, capital investment, liquidity, and profitability. It gives users a practical way to organize assumptions and understand how the bank may perform over a multi-year planning period. This template is useful for preparing business plans, investor presentations, lender discussions, internal budgets, and strategic decision-making. Users can model core revenue assumptions such as loan growth, interest yields, deposit costs, fee income, and investment income, while also planning startup costs, technology investments, regulatory setup, staffing, branch or office expenses, and ongoing operating costs. By connecting these assumptions into financial statements and visual summaries, the model helps users evaluate whether the savings bank can build a sustainable balance sheet and generate attractive returns. The Savings Bank Financial Model also supports scenario planning, cash flow forecasting, profitability analysis, and break-even analysis. Users can test how changes in deposit growth, lending volume, net interest margin, payroll, compliance costs, and overhead affect performance. This makes the model valuable for assessing capital requirements, reviewing liquidity needs, planning hiring, and identifying the point at which the institution may become profitable. It is built to help decision-makers move beyond rough estimates and develop a more defensible financial plan. Fully editable and ready to use, the template can be customized for a new savings bank, a community banking concept, a financial institution expansion, or a planning case prepared by consultants and analysts. It is compatible with Excel and Google Sheets, making it easy to update assumptions, collaborate with stakeholders, and present results in a professional format. For anyone developing a savings bank business plan or funding package, this financial model provides a clear framework for forecasting revenue, costs, cash flow, profitability, and long-term financial viability.
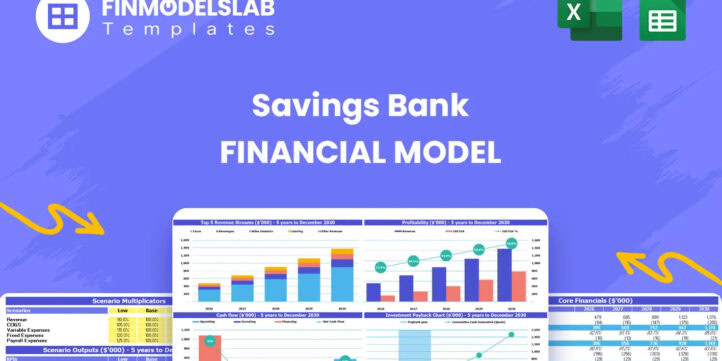


Savings Bank Financial Model Overview
The Savings Bank Financial Model is a ready-to-use financial model template built for planning, forecasting, and evaluating a savings bank or community banking institution. Unlike a generic business spreadsheet, it is structured around the financial mechanics that matter most in banking, including deposit growth, loan balances, interest income, interest expense, net interest margin, non-interest income, operating costs, staffing, capital needs, liquidity, and profitability. This makes it useful for entrepreneurs, founders, consultants, analysts, business owners, and planning teams that need a clear financial forecast for a savings bank business plan, investor discussion, internal budget, or funding document.
The model helps users translate assumptions into a five-year financial outlook, review the relationship between assets and liabilities, estimate startup and operating requirements, and understand how the business may scale over time. Because the template is editable, users can adjust assumptions for their local market, regulatory environment, lending strategy, deposit pricing, staffing plan, and growth objectives. The result is a more organized and defensible planning tool that supports better decisions before launch, during fundraising, or while preparing for expansion.
All-in-One Dashboard
The all-in-one dashboard brings the most important inputs and outputs of the Savings Bank Financial Model into one organized view, giving users a fast way to understand the overall financial picture without reviewing every calculation tab individually. This component typically connects assumptions such as deposit balances, loan portfolio growth, asset yields, deposit rates, staffing levels, operating expenses, capital expenditures, and starting cash with outputs such as revenue, net interest income, EBITDA, profitability, cash balance, return metrics, and key banking ratios.
For a savings bank, this is especially useful because management needs to see how balance sheet growth, interest rate spreads, and operating scale interact over time. The dashboard helps users quickly identify whether the bank is generating enough income to support its cost structure, whether liquidity remains adequate, and whether the projected business plan is moving toward sustainable profitability. It is also practical for investor meetings, board updates, lender conversations, and internal planning sessions because it summarizes detailed financial modeling into a clear and decision-ready format.
Low, Base, and High Scenario Analysis
The low, base, and high scenario analysis component allows users to test different versions of the savings bank forecast under conservative, expected, and optimistic assumptions. A savings bank business can be highly sensitive to changes in deposit growth, loan origination volume, interest rate spreads, credit demand, fee income, payroll costs, technology expenses, and operating efficiency, so a single forecast is rarely enough for serious planning. This section gives users a structured way to compare how financial performance changes when core assumptions move up or down.
For example, the low scenario may reflect slower deposit acquisition, narrower net interest margin, higher overhead, or delayed loan growth, while the high scenario may reflect faster customer adoption, stronger lending demand, improved operating leverage, or higher fee income. The model can then generate different outcomes for revenue, cash flow, profitability, break-even timing, capital requirements, and return metrics. This is useful for risk management, funding preparation, and strategic decision-making because it shows stakeholders not only what may happen under the base plan, but also how resilient the business may be if conditions are weaker or stronger than expected.
Professional Charts
The professional charts component converts the model’s financial projections into visual outputs that are easier to interpret and present. For a savings bank, key trends such as loan portfolio growth, deposit growth, net interest income, fee income, operating expenses, EBITDA, net profit, cash balance, and return metrics can be difficult to communicate through spreadsheets alone.
Charts help users and stakeholders quickly see whether the business is scaling, whether profitability is improving, and whether the bank is maintaining a healthy relationship between assets, liabilities, and capital. This section may include visual trend lines, comparison charts, and performance summaries that support board presentations, investor updates, business plan submissions, and internal reviews. The value of this component is not only presentation quality, but also decision support. When financial outputs are visualized, it becomes easier to spot unusual movements, validate assumptions, compare scenarios, and explain the logic behind the forecast. For founders and analysts preparing a savings bank financial plan, professional charts make the model more persuasive, easier to review, and more useful in stakeholder discussions.
ROE Components and DuPont Analysis
The ROE components section uses a DuPont-style analysis to help users understand what is driving return on equity rather than simply showing the final ROE figure. In a savings bank financial model, return on equity is a critical measure because investors and stakeholders want to know how effectively the institution can convert shareholder capital into profits. This component may break ROE into drivers such as profitability, asset utilization, leverage, margin performance, operating efficiency, and balance sheet structure.
Inputs can include net income, total assets, shareholder equity, interest income, non-interest income, operating expenses, and capital assumptions. The outputs help users see whether ROE is improving because of stronger margins, better cost control, increased asset productivity, or higher leverage. This is particularly important for banking because growth funded by deposits and capital must be managed carefully to maintain credibility, liquidity, and regulatory strength. By showing the underlying drivers of return on equity, the model supports investor analysis, management decision-making, pricing strategy, capital planning, and long-term performance improvement.
Revenue Inputs
The revenue inputs component is where users define the assumptions that drive the savings bank’s income forecast. Because a bank’s revenue is not based only on simple sales volume, this section is structured around banking-specific drivers such as loan balances, loan categories, interest yields, deposit funding costs, investment securities, service fees, ATM charges, account fees, and other non-interest income sources. Users can adjust assumptions for mortgages, auto loans, business loans, consumer loans, investment income, deposit pricing, interest rate spreads, and customer activity.
The model then uses these assumptions to estimate net interest income and additional fee-based revenue over the forecast period. This component is valuable because small changes in yield, funding cost, or portfolio mix can significantly affect profitability. It also helps users document the logic behind revenue projections, which is important when preparing a business plan or discussing the forecast with investors, lenders, regulators, or advisors. By making revenue assumptions transparent and editable, the Savings Bank Financial Model gives users a more credible way to forecast income and test the financial impact of different lending and deposit strategies.
Bank-Ready Reports
The bank-ready reports component organizes financial outputs into a professional reporting format suitable for stakeholders who expect clear and structured financial statements. This may include projected income statements, cash flow forecasts, balance sheet summaries, profit and loss views, annual and monthly outputs, and banking-specific summaries that show how revenue, expenses, assets, liabilities, and equity develop over time. For a savings bank, reporting must be more detailed than a standard startup forecast because stakeholders need to understand both operating profitability and balance sheet strength.
The reports can help users track net interest income, operating expenses, EBITDA, net income, cash position, loan balances, deposit balances, capital investment, and funding needs. This component is useful for preparing lender-friendly financial outputs, investor packages, board materials, and internal management reports. It also improves model usability because users can move from detailed assumptions to polished summaries without rebuilding reports manually. A clear reporting structure makes the financial plan easier to review, easier to challenge, and easier to update as actual performance data becomes available.
Revenue Breakdown
The revenue breakdown component provides a detailed view of the savings bank’s different income streams so users can understand where revenue is coming from and how each line contributes to overall performance. Instead of presenting total revenue as a single figure, this section separates major drivers such as interest on loans, interest from investment securities, account service fees, ATM fees, transaction charges, and other non-interest income. It may also show how revenue changes by year, by product category, or by balance sheet driver.
This is useful because a savings bank’s earnings quality depends heavily on the mix between interest income and fee income, the size and yield of the loan book, the cost of deposits, and the stability of recurring revenue sources. Users can adjust assumptions to test whether higher loan growth, stronger fee adoption, different product mixes, or improved deposit pricing create a more attractive financial profile. The revenue breakdown also helps with strategy because it highlights which activities deserve more attention, which products may carry the strongest margin contribution, and where the bank may need additional marketing, staffing, or technology investment to reach its targets.
KPI Dashboard
The KPI dashboard tracks the key performance indicators that matter most when evaluating a savings bank’s financial health and operating performance. This component may include metrics such as net interest margin, return on assets, return on equity, efficiency ratio, deposit growth, loan growth, cash balance, EBITDA, profitability, capital ratios, and other performance benchmarks. For founders and management teams, these KPIs help connect day-to-day assumptions with the metrics investors, lenders, regulators, and senior stakeholders typically review.
Inputs may come from the revenue forecast, operating expense schedule, payroll plan, balance sheet, and cash flow statement, while the outputs provide a concise view of financial performance over time. This dashboard is valuable for monitoring whether the business is scaling efficiently, whether profitability is improving, whether expenses are under control, and whether the bank’s balance sheet is developing in a sustainable way. It can also support benchmarking by helping users compare their assumptions and outcomes against industry expectations. For a savings bank business plan, the KPI dashboard makes the forecast more actionable because it turns detailed calculations into measurable performance targets.
Startup and Operating Cost Planning
The startup and operating cost planning component helps users estimate the upfront investment and recurring expenses required to launch and run a savings bank. A new banking institution can require significant initial spending on core banking systems, digital banking platforms, office build-out, furnishings, compliance setup, licensing, legal support, technology infrastructure, security, marketing, and working capital. Ongoing costs may include software subscriptions, rent, utilities, insurance, compliance costs, audit and accounting services, customer support, technology maintenance, marketing, professional fees, and general administrative expenses.
This section allows users to separate one-time startup costs from recurring operating expenses so they can understand both the capital needed before launch and the monthly cost base once operations begin. It is especially useful for funding preparation because investors and lenders will want to see that the startup budget is realistic and that the bank has enough capital to operate through the early loss-making period. By organizing expenses clearly, the model helps users avoid underestimating launch requirements, plan cash reserves, and make more informed decisions about timing, hiring, technology investment, and branch or office setup.
Break-Even and Capital Funding Analysis
The break-even and capital funding analysis component helps users determine when the savings bank may become profitable and how much funding may be required to reach that point. This section connects revenue growth, net interest income, non-interest income, payroll, operating expenses, startup costs, cash flow, and capital assumptions to show whether the institution can cover its cost structure over time. Break-even analysis is especially important for a savings bank because early operations may require substantial investment before the loan book, deposit base, and fee income reach efficient scale.
Inputs may include initial equity contributions, planned funding rounds, startup investment, fixed costs, variable expenses, interest rate assumptions, customer growth, loan origination pace, and deposit growth. Outputs can include break-even timing, cumulative cash needs, minimum cash balance, payback period, and funding gaps. This component supports better decision-making by showing whether the business plan is adequately capitalized and whether additional funding may be needed before profitability is reached. It is also useful for investor discussions because it explains how capital will be used, when losses may narrow, and what operational milestones are required for the savings bank to become financially sustainable.
File types:
Excel – Single-User: .xlsx
Excel – Multi-User: .xlsx
Free Demo – .xlsx
Similar ProductsOther customers were also interested in...


 Jason Varner
Multi-Member Investment Fund Portfolio and Distrib...
A fund management tool to track many positions over time as well as distributions to up to 20 member... Read more
 HenrySheykin
Legal Services Financial Model Excel Template
The Legal Services Financial Model Financial Model Template helps entrepreneurs, law firm founders, ... Read more
Mortgage Bank Financial Model Excel Template
The Mortgage Bank Financial Model helps users turn a mortgage banking concept, expansion plan, or fu... Read more
Offshore Bank Financial Model Excel Template
The Financial Model Template helps founders, banking entrepreneurs, consultants, analysts, and busin... Read more
 MENA Research Partne...
Alternative Investment Company Valuation Template
Alternative Investment Company Valuation: All-In-One Model for Private Equity, Asset Management, and... Read more

 Giorgos
Crowdlending (P2P) Platform – 5 Year Financi...
Financial Model providing an advanced 5-year financial plan for a startup Crowdlending (Peer-to-Peer... Read more
 Eastwich Advisors
Debt Fund Excel Model
Explore the Debt Fund Excel Model, a comprehensive tool for evaluating new credit fund opportunities... Read more

Crypto Token Valuation Model
A cutting-edge crypto token valuation model, designed to provide comprehensive insights and analytic... Read more
Amortization Schedules Template (Loans, Mortgages,...
User friendly template including Amortization Schedules for Loans, Mortgages, Operating and Finance ... Read more
Online Bank Financial Model Excel Template
The Online Bank Financial Model Financial Model Template helps founders, fintech entrepreneurs, cons... Read more
You must log in to submit a review.