
0 ITEMS

Bridge-to-Agency Refinance Model — Value-Add Multifamily Bridge Loan, Renovation Roll-Up, Rent Lift, Agency Takeout Sizing and LP/GP Returns
Value-add multifamily: bridge loan, monthly renovation roll-up, trailing NOI, agency takeout at MIN(LTV, DSCR, DY), cash-out, promote returns.

This Excel template models a value-add multifamily acquisition from bridge closing through renovation, agency refinance and sale over 60 months. It is built the way a bridge lender, an agency lender and an equity investor each look at the same deal, and it is designed for sponsors preparing a bridge loan request and an investor presentation, lenders underwriting the business plan and the takeout, and analysts who need to show whether the refinance repays the bridge and what comes back to equity.
Inputs
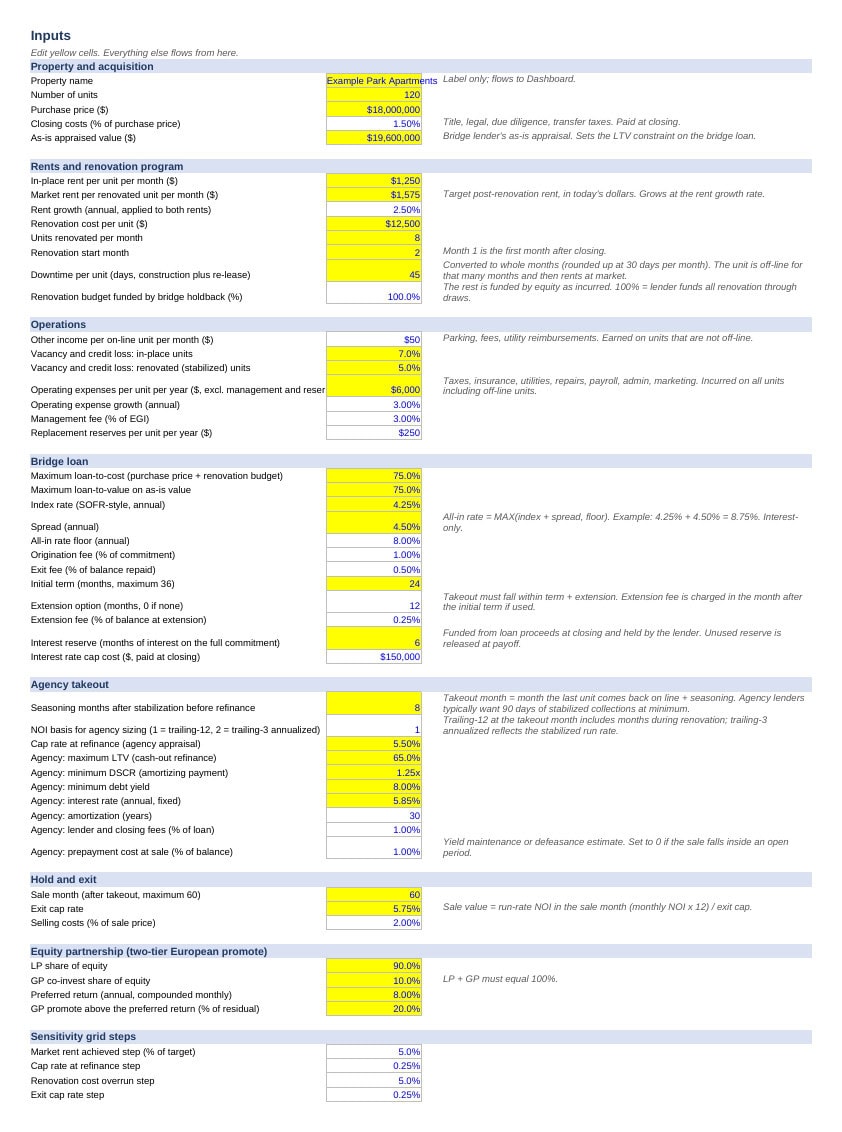
The Inputs sheet holds the full assumption set in one place: units, purchase price, closing costs and as-is appraised value; in-place and market rent with annual growth, renovation cost per unit, pace in units per month, start month and downtime in days (converted to whole months), and the share of the renovation funded through the bridge holdback; vacancy for in-place and renovated units, other income, operating expenses and growth, management fee and replacement reserves; bridge terms including maximum loan-to-cost on purchase plus renovation, maximum loan-to-value on as-is value, an index rate plus spread with a floor, origination and exit fees, an initial term of up to 36 months, an extension option with its fee, interest reserve months and the rate cap cost; agency terms including seasoning months after stabilization, a trailing-12 or trailing-3 NOI switch, cap rate at refinance, maximum LTV, minimum DSCR, minimum debt yield, rate, amortization, lender fees and prepayment cost; the sale month, exit cap and selling costs; and the LP/GP equity split, preferred return and promote.
Bridge Loan, Renovation and Agency Takeout
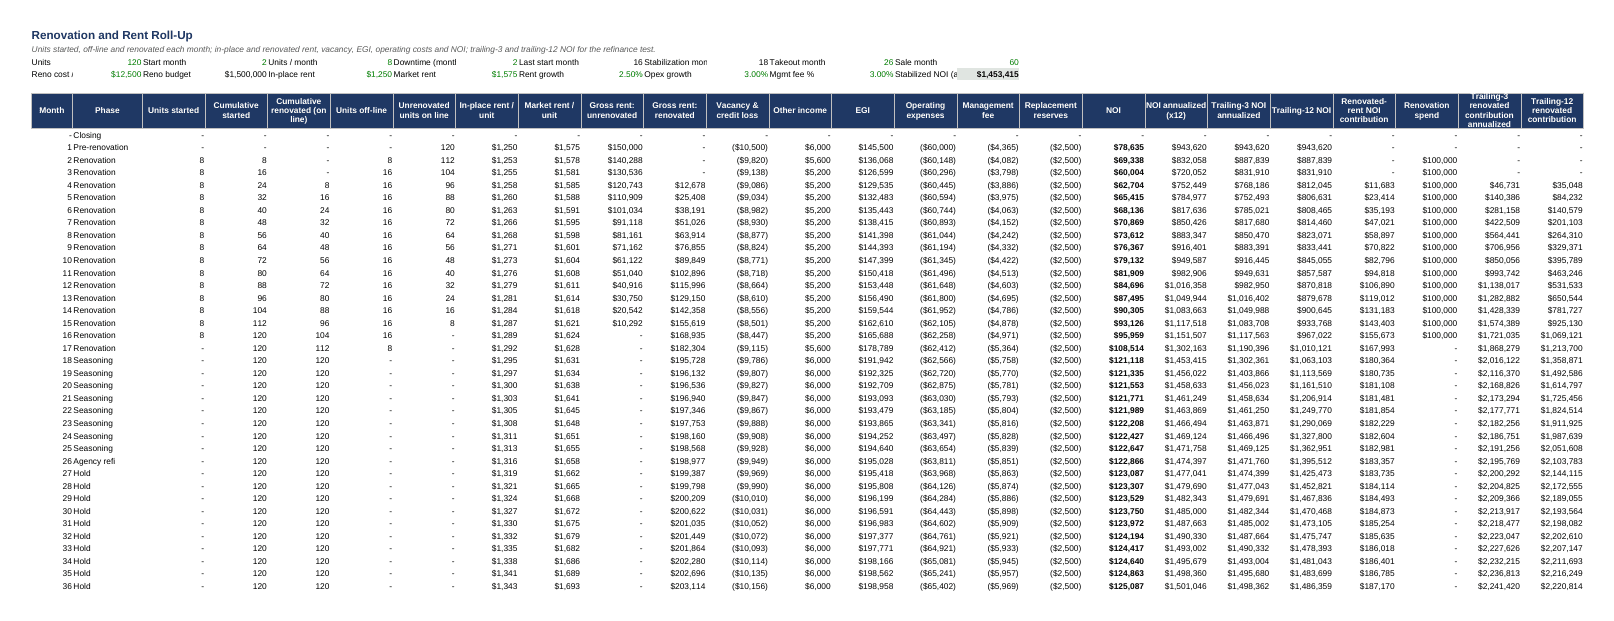
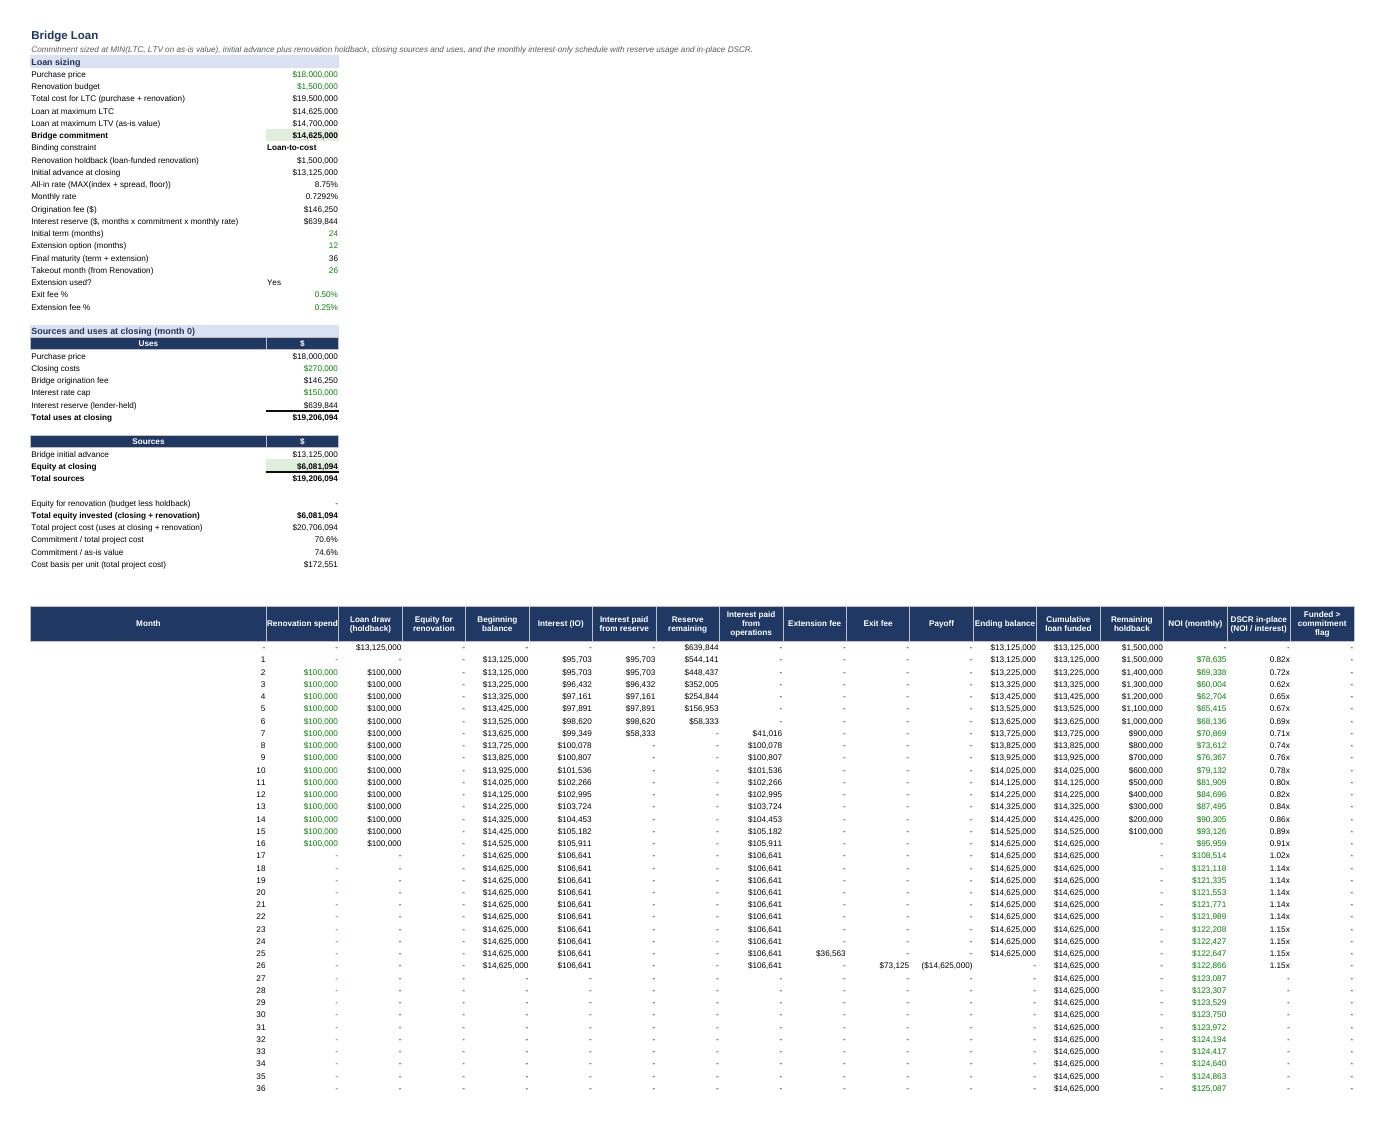
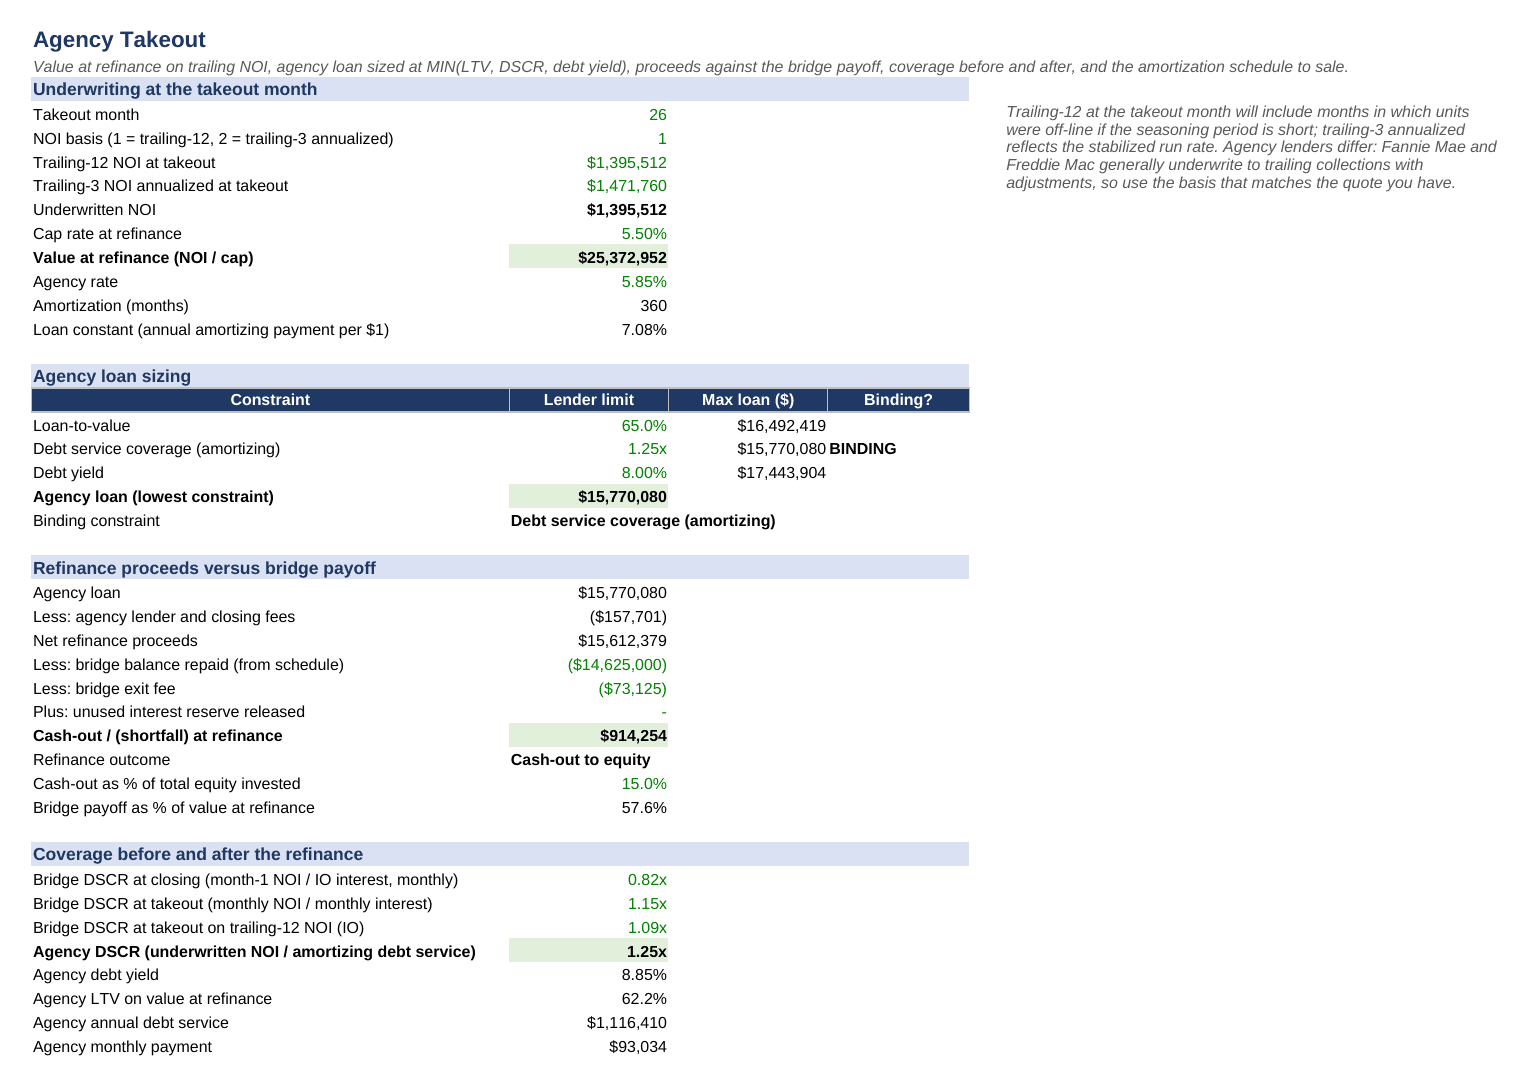
Bridge Loan sizes the commitment at the lower of LTC and LTV, flags the binding constraint, splits it into the initial advance and the renovation holdback, builds the closing sources and uses, and runs the monthly schedule: holdback draws until exhausted and equity thereafter, interest-only interest on the prior month’s balance, interest paid first from the lender-held reserve and from operations once it is spent, extension fee if the takeout falls after the initial term, exit fee, payoff, cumulative funding against the commitment and the in-place DSCR each month. Renovation runs the unit roll-up with units started, off-line and renovated, in-place and renovated gross rent, vacancy, other income, EGI, operating expenses, management fee, reserves, NOI and the trailing-3 and trailing-12 NOI an agency lender will underwrite. Agency Takeout values the property at underwritten NOI divided by the cap rate at refinance, sizes the loan at the lowest of LTV, DSCR on the amortizing payment and debt yield with the binding constraint flagged, nets lender fees against the bridge payoff and exit fee, adds back the unused reserve, reports cash-out or shortfall, shows bridge DSCR at closing and at takeout next to agency DSCR, debt yield and LTV, and amortizes the agency loan to the sale month.
Returns, Sensitivity and Dashboard
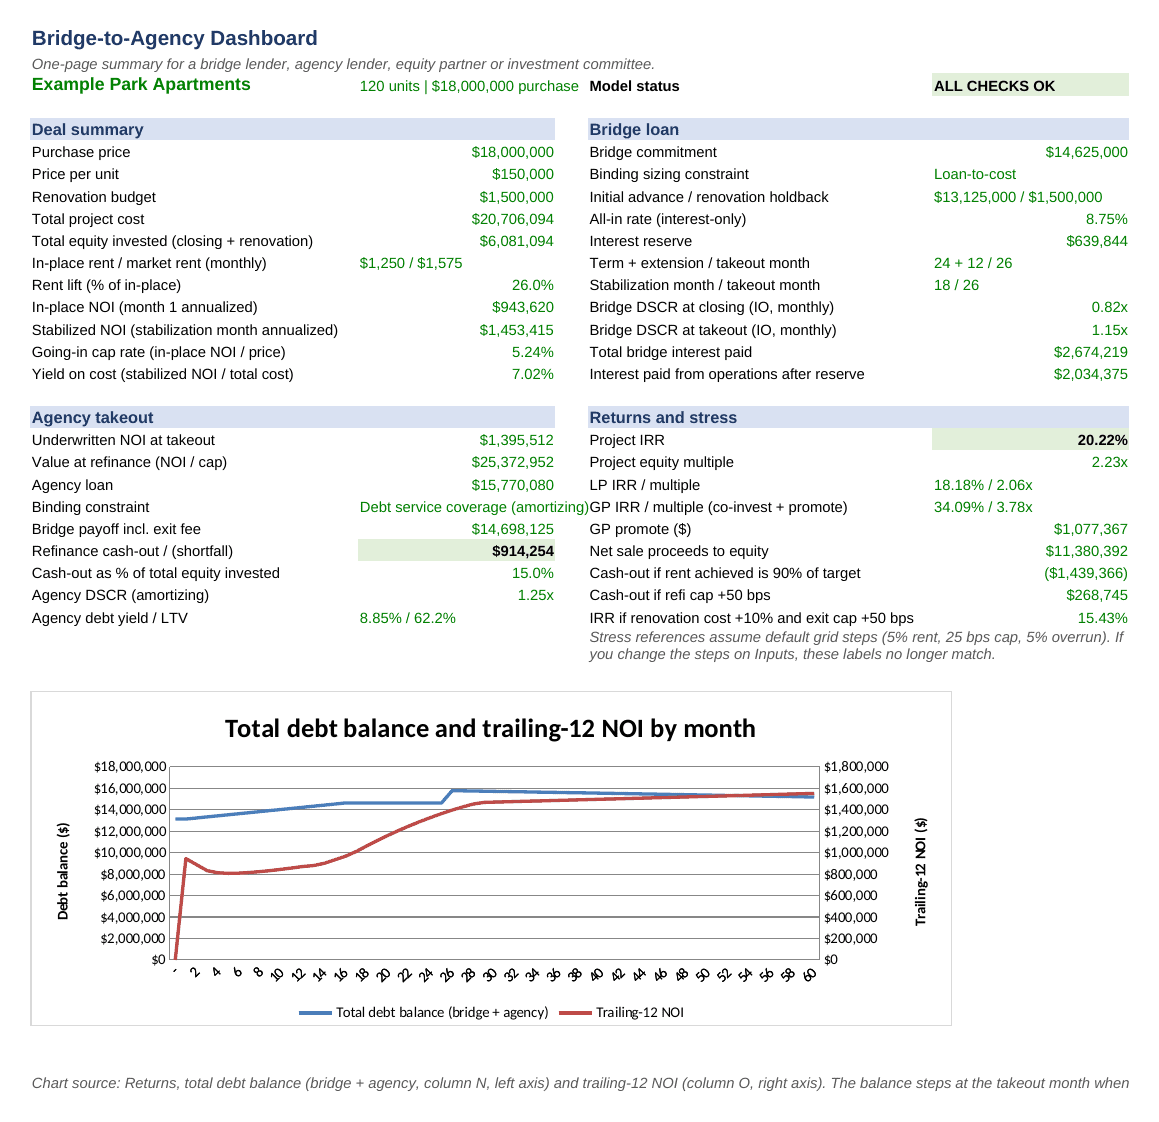
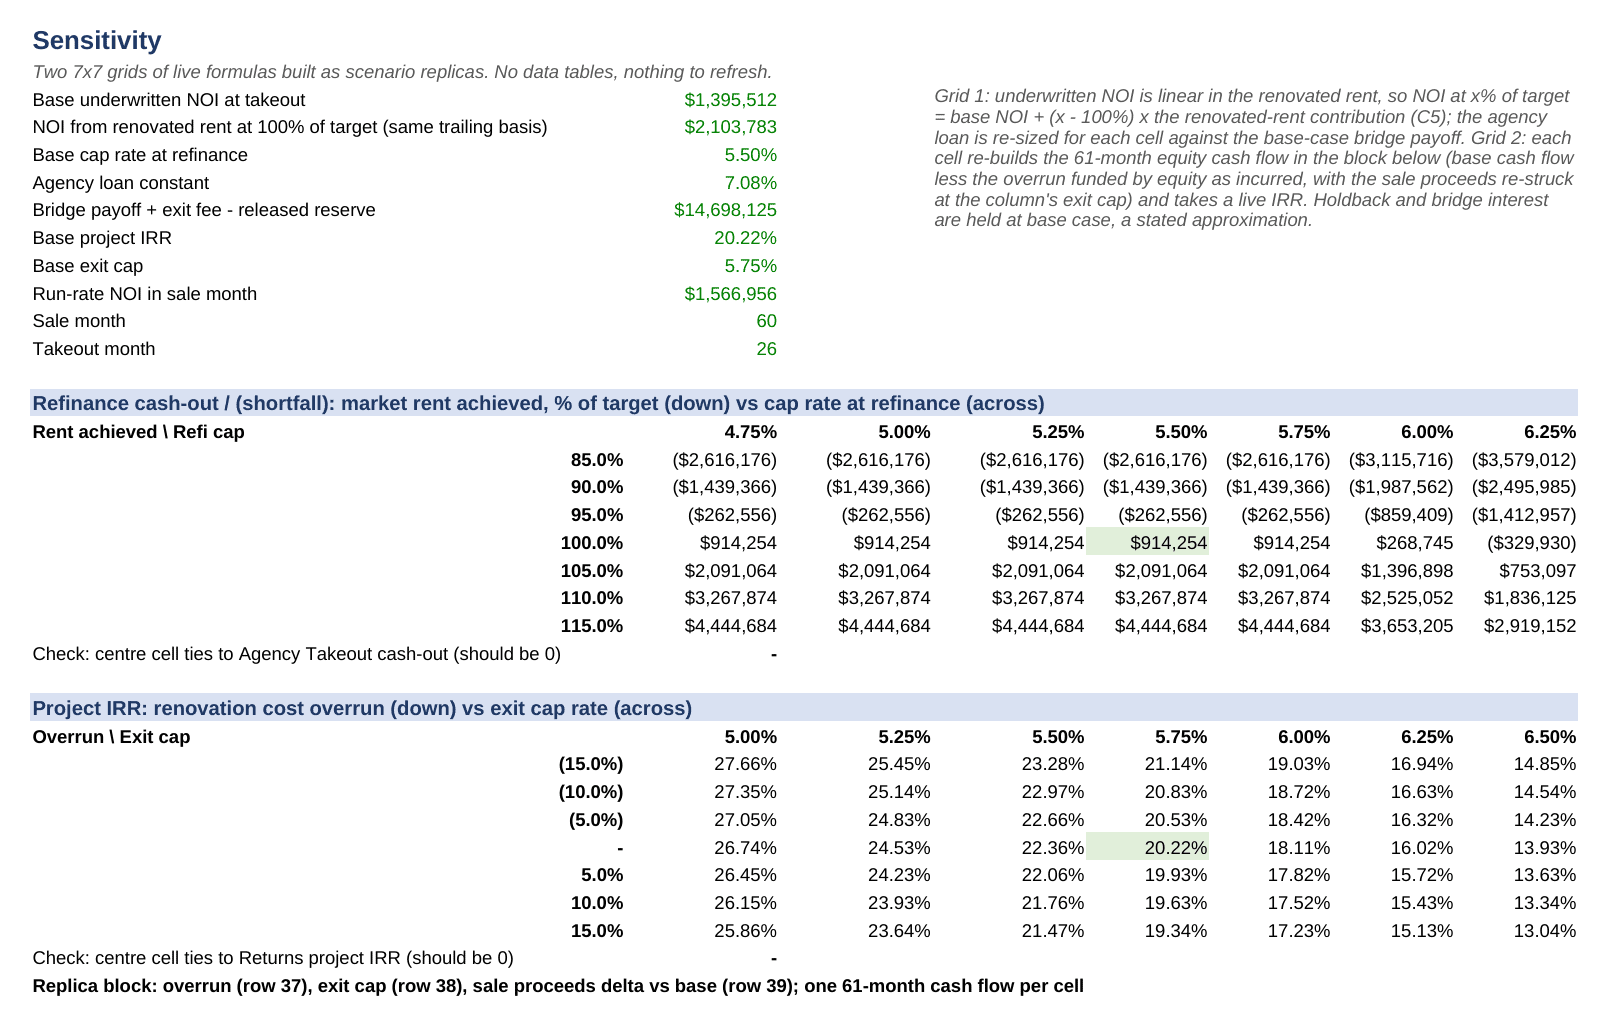
Returns builds the monthly equity cash flow (equity at closing, renovation equity, NOI less bridge interest not covered by the reserve, extension fee, agency debt service, refinance cash-out or shortfall, net sale proceeds after the agency payoff and prepayment cost), reports project IRR, equity multiple, peak equity and cash-out as a percent of equity, and runs a European two-tier waterfall with an IRR-lookback hypothetical capital account to produce LP and GP returns and the promote. Sensitivity contains two live 7×7 grids with no data tables: refinance cash-out against market rent achieved and cap rate at refinance, which re-sizes the agency loan exactly for each cell, and project IRR against renovation cost overrun and exit cap, which rebuilds the 61-month cash flow for each of the 49 cells and takes a live IRR. The Dashboard summarizes the deal, the bridge, the takeout and the returns on one page with a chart of total debt balance and trailing-12 NOI by month and a single status cell that rolls up fifteen checks.
Format
Formatting follows standard conventions: blue inputs, black formulas, green cross-sheet links, yellow fill on primary inputs. No macros, no data tables, no circular references, no external links, no protected sheets. Runs in Excel 2016 or later and in LibreOffice. The example case is a 120-unit property with a 15-month renovation, an agency takeout in month 26 and a sale in month 60.
This template was built and tested by an AI system under a finance professional’s standing specification, recalculated with an independent engine and reviewed before release. It is a modelling tool, not financial, investment, lending or legal advice; match it to the terms of your bridge and agency commitments before relying on it.
Similar ProductsOther customers were also interested in...



 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more

Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more

Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more

 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.