
0 ITEMS

Residential Assisted Living / Adult Family Home Acquisition & SBA Underwriting Financial Model
Acquisition & SBA underwriting model for a single residential assisted living / adult family home (6-16 beds). Census x payer-mix (private vs Medicaid) revenue, caregiver-ratio cost engine, owner-administrator add-back, true-vs-naive DSCR, two prices, occupancy/caregiver-shortage down-case. 11 tabs, Excel + Google Sheets.
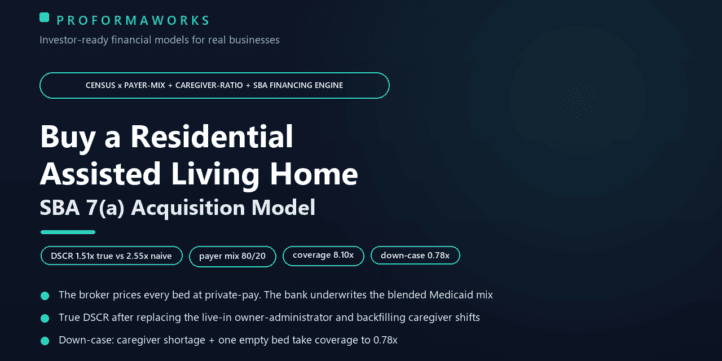
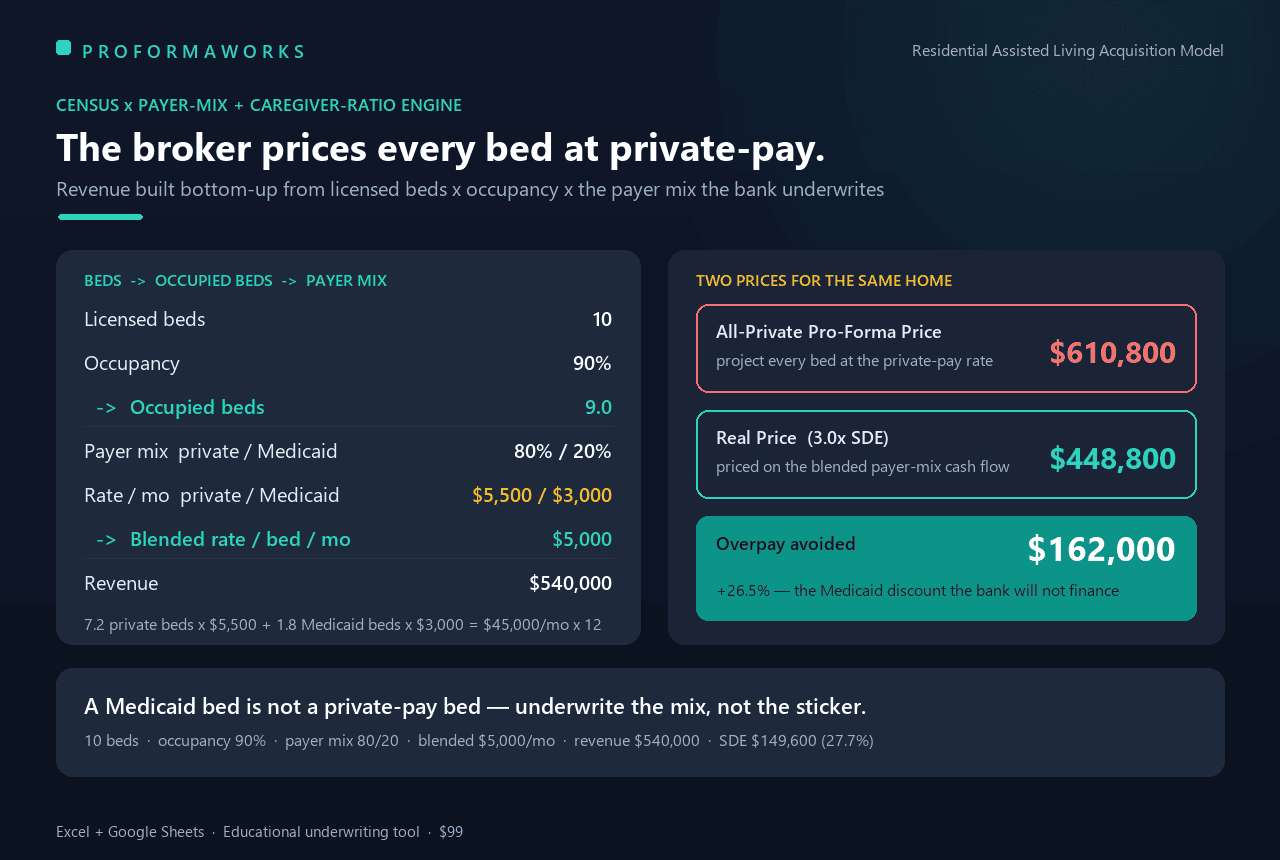
The broker prices this care home as if every bed paid private. One in five beds is Medicaid. That gap is $162,000 of purchase price.
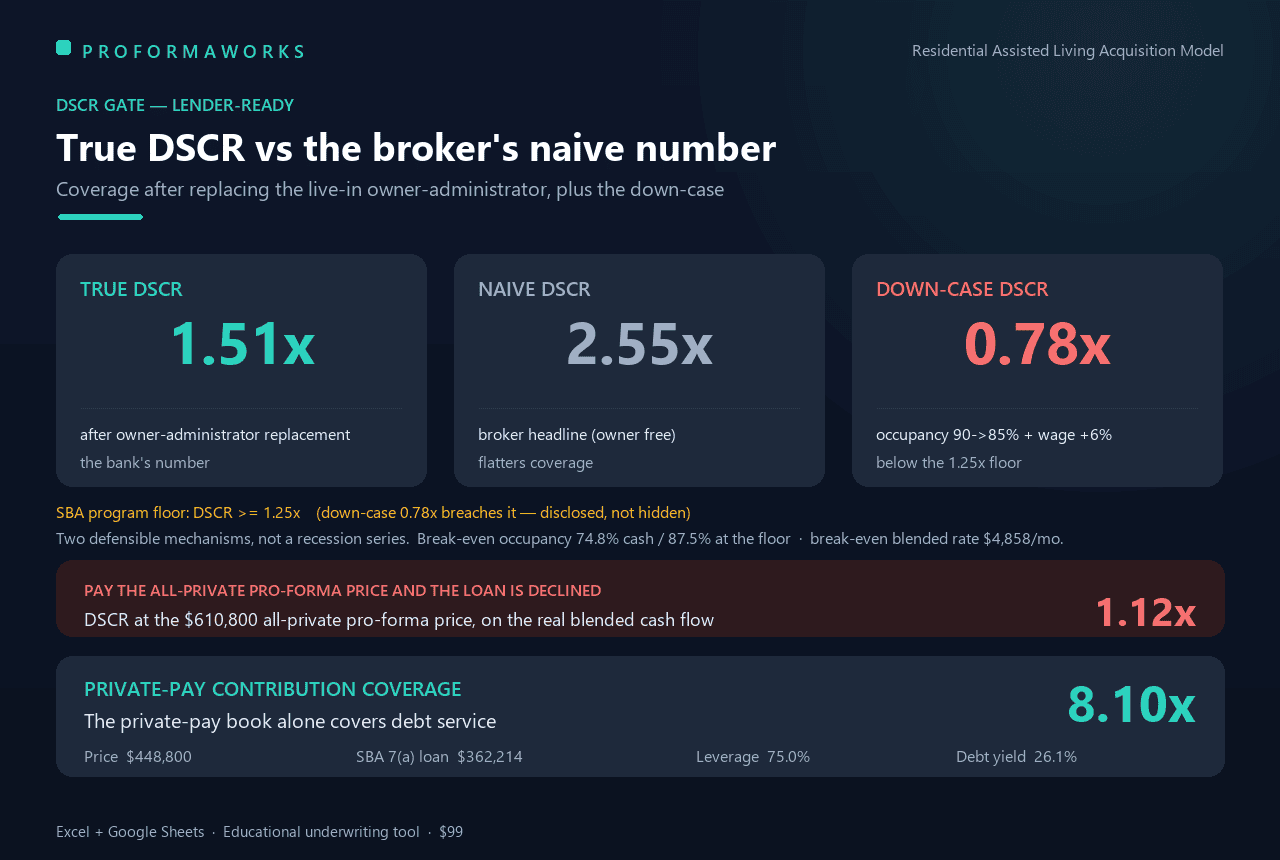
A residential assisted living home is a census business: beds times occupancy times the rate each resident actually pays. A private-pay bed and a Medicaid-waiver bed look identical on a tour and pay about 45% apart. Present the home as if all ten beds were private and you overstate SDE, because the caregiver coverage does not change with the payer. This model underwrites the blended net rate a bank accepts — not the private sticker — and shows the all-private pro-forma price ($610,800) next to the real, blended-rate price ($448,800), with the DSCR at each (1.12x, declined, vs 1.51x). Overpay avoided: $162,000 (26.5%).
It is the model a searcher / ETA buyer hands the lender, built the way a bank underwrites, not a startup forecast:
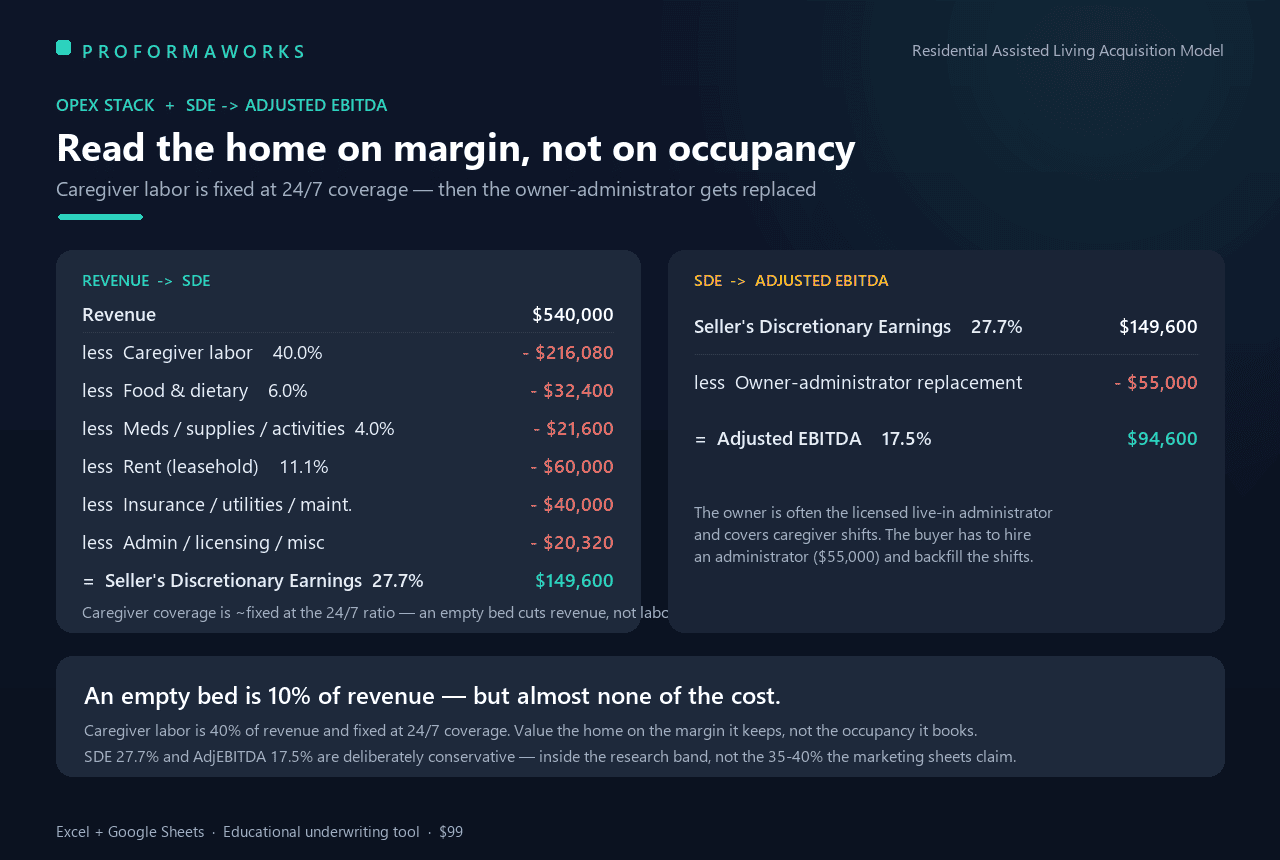
- Census and payer-mix revenue engine — 10 beds at 90% occupancy, 80% private / 20% Medicaid, at $5,500 private and $3,000 Medicaid-net, a $5,000 blended rate per occupied bed per month, $540,000 a year.
- Caregiver coverage-ratio engine — the dominant cost (about 40% of revenue), derived from a day/awake-night ratio and roughly fixed at 24/7 coverage. When a bed empties the labor barely drops. A light night ratio that a state audit would reject is a hidden cost.
- DSCR true (1.51x) vs naive (2.55x) — the true figure hires a $55,000 administrator to replace the owner who runs the home and covers shifts, and reserves capex. The gap is the owner’s own labor.
- Occupancy and caregiver-shortage down-case — one empty bed is 6-16% of a small home’s revenue, and with direct-care turnover near 75% a wage spike bites while coverage stays fixed. Occupancy 90 to 85% plus a 6% wage rise drives DSCR to 0.78x. Two mechanisms, not a recession back-test.
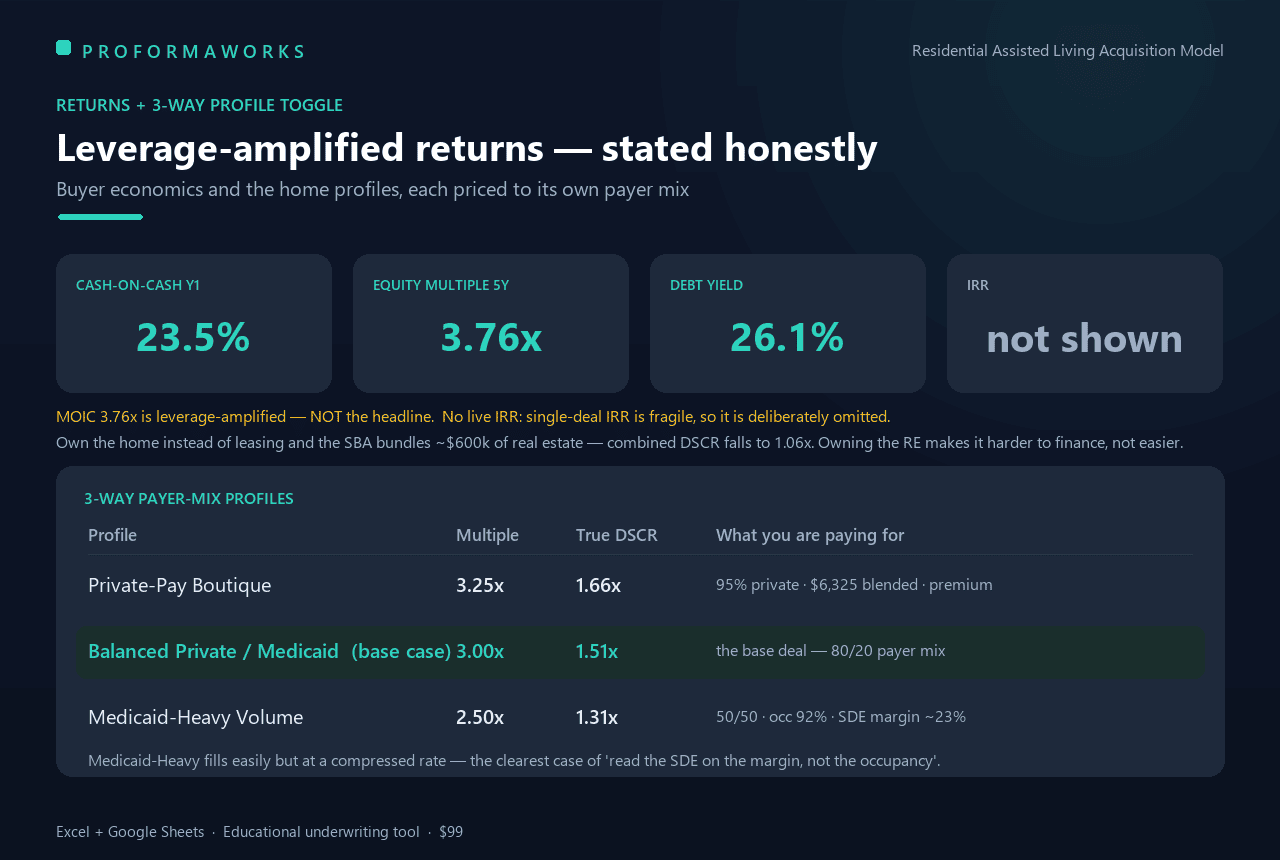
- Owning the real estate makes it harder, not easier — a fee-simple toggle shows bundling the ~$600,000 home into the SBA loan adds ~$65,000/yr of mortgage and compresses the combined DSCR to ~1.06x.
- SBA 7(a) capital stack, seller-note standby lever, real amortisation, debt yield (26.1%), three break-even occupancies (74.8% where SDE covers the loan with the owner still unpaid, 86.2% where your own after-tax cash flow is zero, 87.5% at the 1.25x floor) and break-even blended rate ($4,858/mo), and 3 profiles (Private-Pay Boutique 3.25x / Balanced 3.00x / Medicaid-Heavy Volume 2.50x).
Excel model, 11 tabs, 5-year, every assumption editable and highlighted (Google-Sheets compatible — no macros, no add-ins); a PDF guide with sources. SDE (27.7%) and Adjusted EBITDA (17.5%) are held deliberately conservative. No live IRR by design; the 5-year MOIC (3.76x) is flagged leverage-amplified. This is the first acquisition-underwriting model for residential assisted living / adult family homes — not the first RAL model; startup forecasts already exist. Benchmarks from CDC/NCHS, Genworth, NIC, AHCA/NCAL, PHI, BizBuySell and BLS. Educational planning tool — not financial, lending, legal or medical advice.
Similar ProductsOther customers were also interested in...



 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more

Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more

Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more

 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.