
0 ITEMS

Operating Solar Asset Acquisition Model | P50 Recalibration & Tax-Equity Flip Underwriting
Buy-side underwriting for a US utility-scale solar plant that is already built and running. Recalibrates the P50 from the measured production record and models the tax equity flip already in the capital structure.
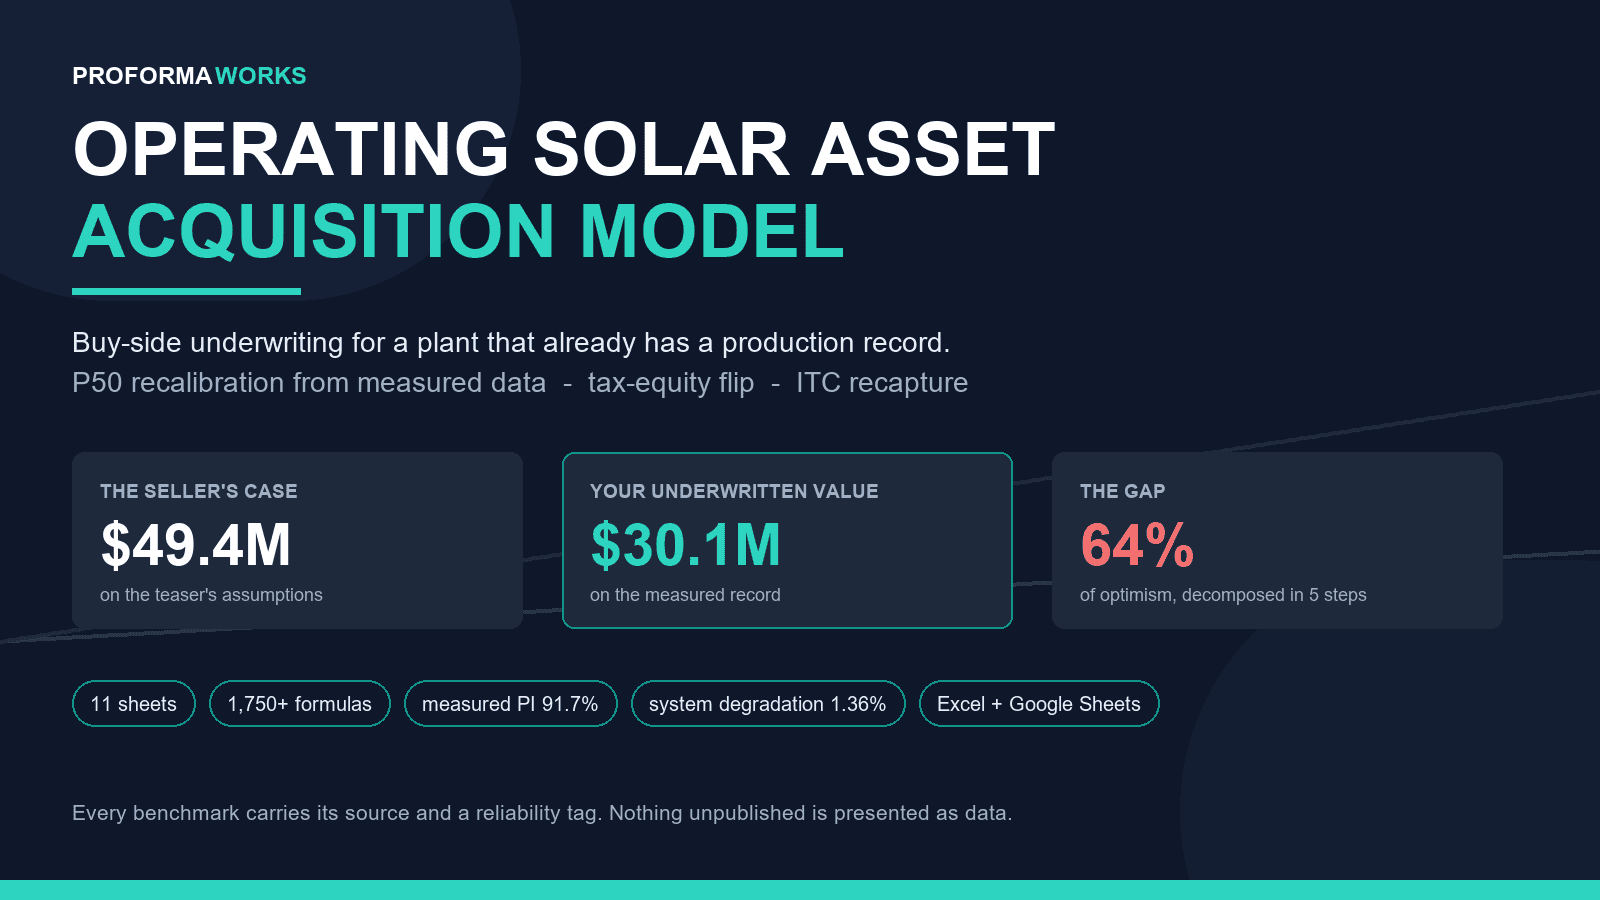
Most solar financial models forecast a plant that does not exist yet. This one underwrites a plant that does – and that changes everything, because an operating asset has a production record, and the record beats any forecast.
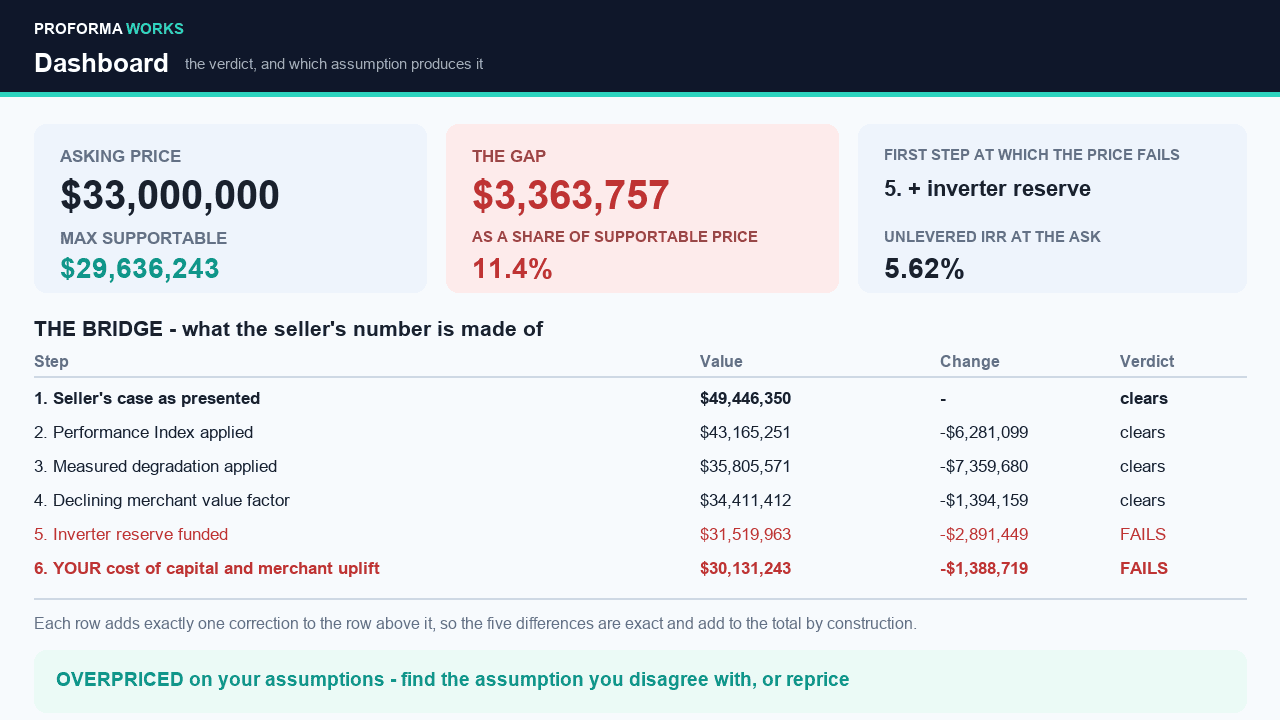
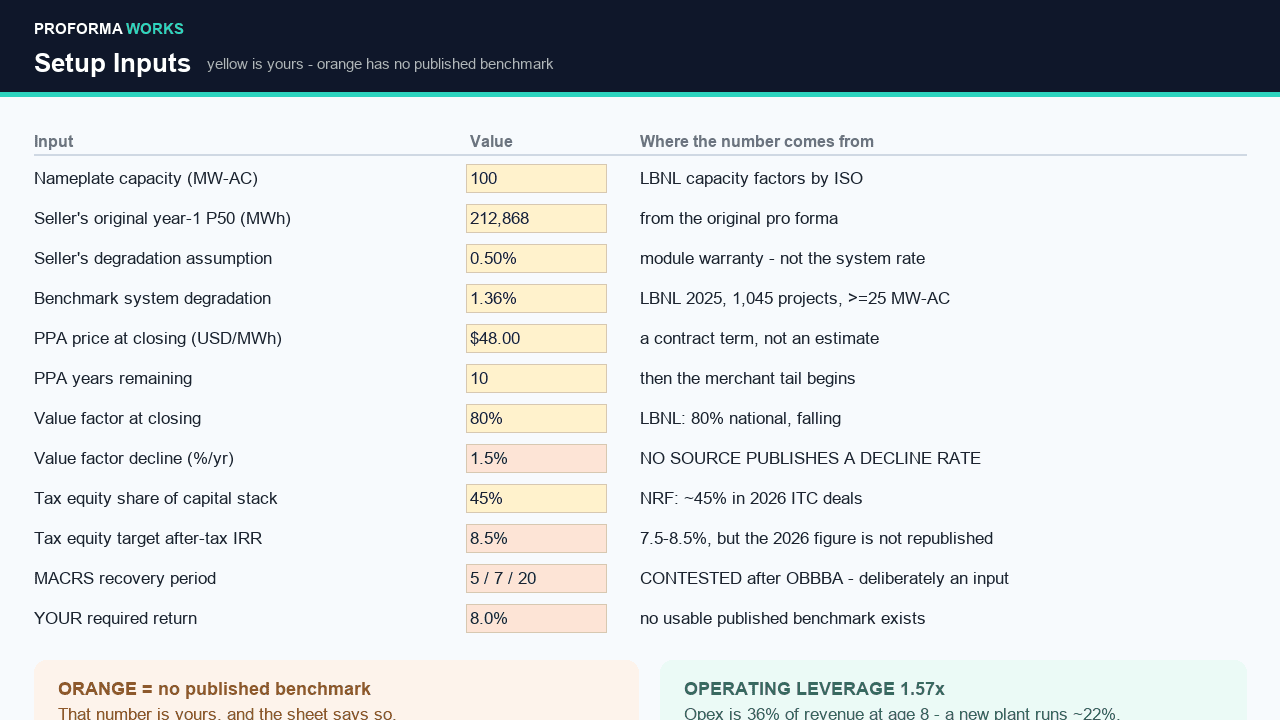
The model prices the same asset twice. The seller’s case runs on the assumptions in the teaser: the original P50 uncorrected, degradation at the module-warranty rate, a flat merchant value factor, no inverter reserve. The underwritten case runs on what survives diligence: the P50 recalibrated from the measured record, system degradation regressed from that same record, a merchant value factor that declines with penetration, a funded inverter reserve, and your required return. The distance between the two is decomposed into five exact steps, so you see not only that the price is wrong but what it is wrong about.
Three engines competing models do not contain
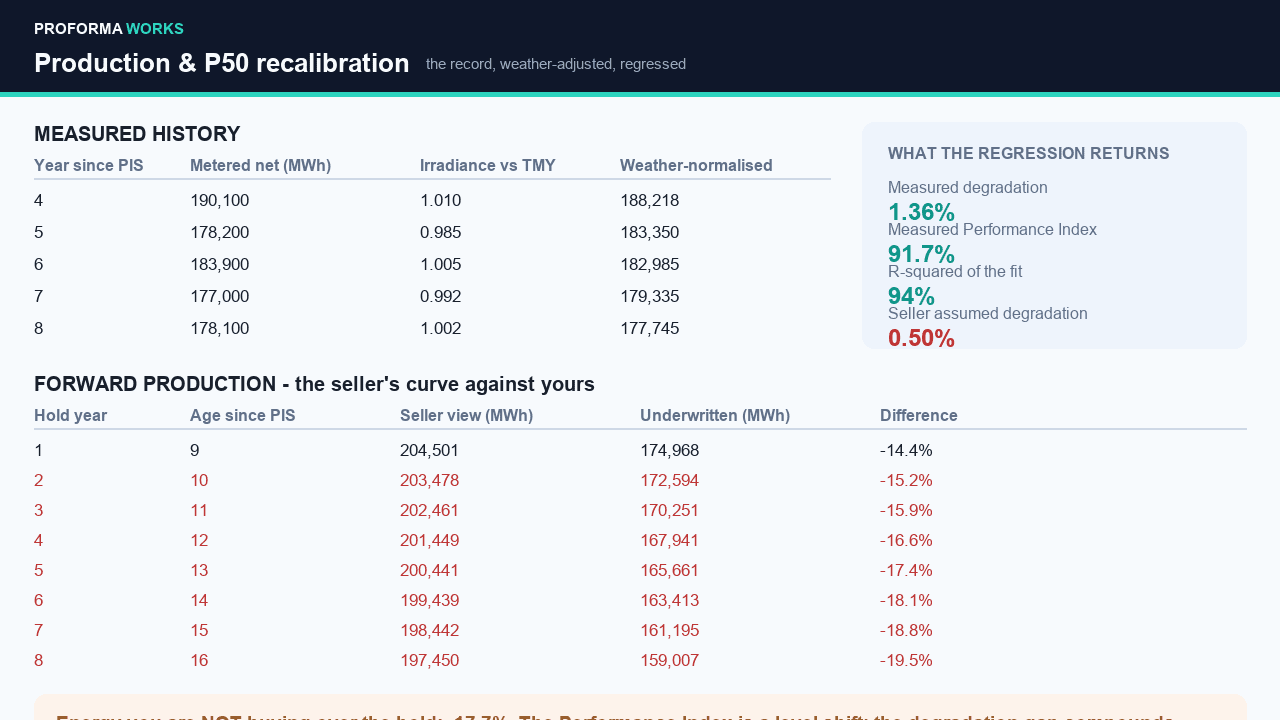
- Five-step P50 recalibration – weather-normalise the metered record against TMY, separate recurring losses from genuine one-offs, and regress the log of normalised output against age. The slope gives measured system degradation; the intercept gives the Performance Index. The US fleet delivers about 8.6% less than its own weather-adjusted P50 – on an operating asset you can measure it instead of assuming it.
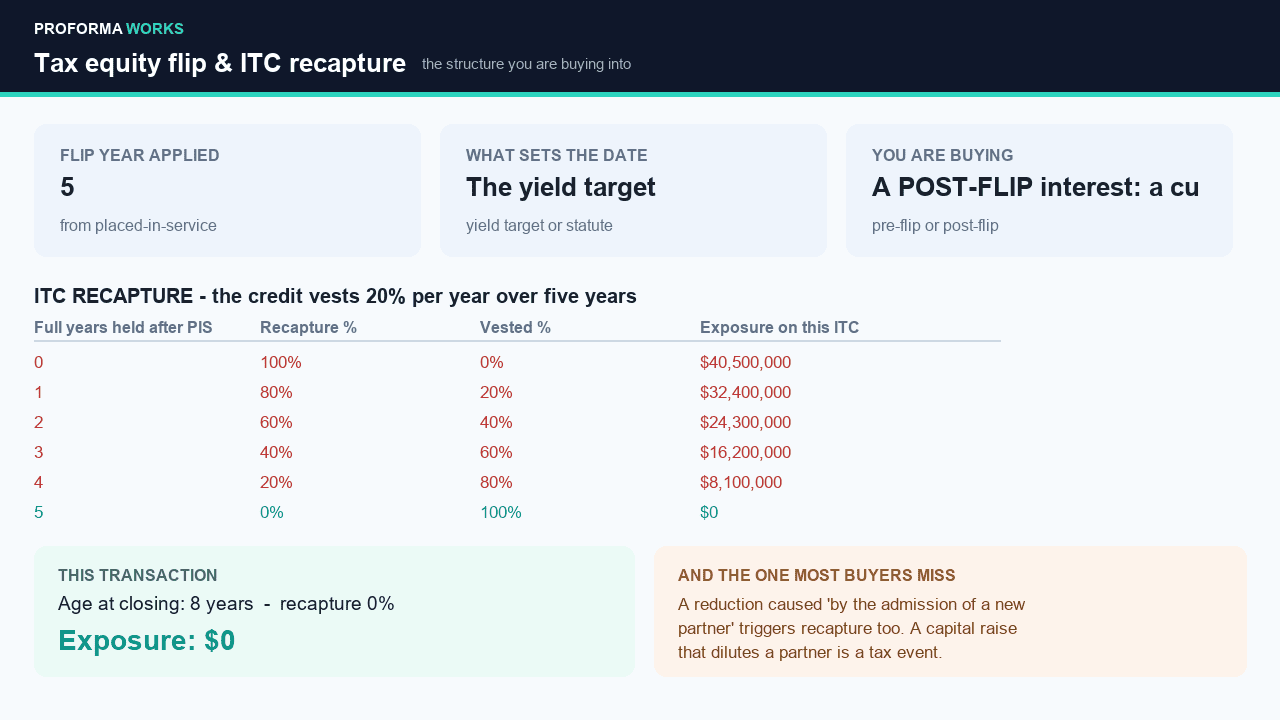
- Tax equity partnership flip waterfall – pre-flip and post-flip allocations of cash and of tax benefits held separately, the flip date determined from the target after-tax return, and the statutory five-year minimum enforced. Buying sponsor equity before and after the flip are two different assets.
- ITC recapture ladder – the 20%-per-year vesting scale, the two-thirds partnership threshold, and the exposure sized by the form of your transaction.
Also modelled: PPA mark-to-market, a merchant tail discounted separately at your rate plus an uplift, mid-life inverter reserve, back-leverage with contracted and merchant coverage tests, and the operating leverage of a mature asset – where opex runs over a third of revenue rather than the 22% of a new plant.
Every benchmark carries its source and a reliability tag. Where no published benchmark exists – the discount rate, the value-factor decline, inverter replacement timing, transaction costs – the workbook says so instead of inventing one. The MACRS recovery period is deliberately an input, because the sources contradict each other after OBBBA.
11 sheets, 1,752 formulas. Excel and Google Sheets, no macros, no external links. Includes a 7-page user guide. Tax law as published at 18 August 2026.
A free PDF demo tier is available above: it shows the sheets and the base-case results, with no formulas and no Excel file.
Educational planning tool. Not financial, investment, tax or legal advice.
Similar ProductsOther customers were also interested in...



 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more

Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more

Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more

 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.