
0 ITEMS

Boutique Hotel / Motel Acquisition & SBA Underwriting Model — RevPAR, PIP, FF&E Reserve, DSCR
Underwrite a hotel/motel acquisition the way an SBA lender does: build revenue from RevPAR, take it through a USALI P&L to the NOI a bank actually lends against (after a management fee and an FF&E reserve the seller skipped), price the deal two ways (the broker per-key comp vs the income method), load the brand PIP into the total project cost, and run the DSCR gate, a RevPAR down-case and the returns. 10 tabs, Excel + Google Sheets.
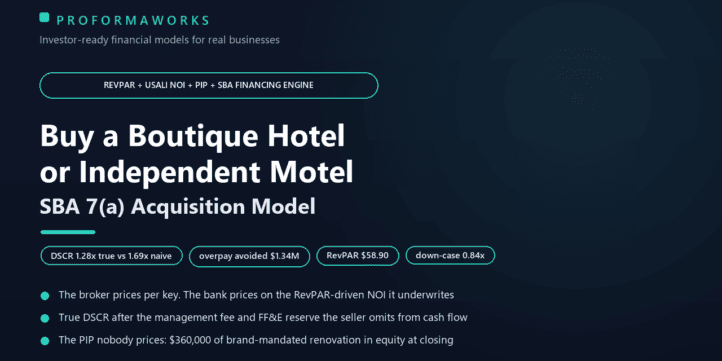


The broker prices this motel at $75,000 a key. The bank sizes it at $52,700 a key. The $1.34M gap is the whole game.
Every hotel pro-forma you will be shown leads with a RevPAR and stops at a proud “owner cash flow.” A lender does neither. It discounts the RevPAR to the NOI the property actually nets — after a management fee and an FF&E reserve the seller never booked — caps that at a going-in rate, and hands you a brand-mandated PIP cheque at closing. This is an acquisition-underwriting model for a single independent or flagged hotel/motel (~40–120 keys) bought with an SBA 7(a)/504 loan — hospitality is the single largest SBA lending category.
What it does
- RevPAR revenue engine — 60 keys x $95 ADR x 62% occupancy = a $58.90 RevPAR, ~$1.29M rooms + ~$0.11M other = $1.4M revenue.
- USALI flow-through to NOI — departmental and undistributed costs (incl. the franchise fee) to a $532,000 GOP (38%), then the two deductions a seller’s P&L skips: an absentee management fee (~3.5% = $49k) and an FF&E reserve (~4% = $56k). A $437,000 “owner cash flow” becomes a $332,000 underwritten NOI.
- Two prices, side by side — the broker’s per-key comp ($4,500,000) vs the bank’s income method ($3,163,555 = NOI / 10.5% cap), the overpay avoided ($1,336,445, 29.7%), and the DSCR at each price (0.93x at the broker price — declined).
- The PIP nobody prices — the brand’s Property Improvement Plan at change of ownership ($6–10k/key = $360k+), real capex financed on day one, ~10% of the deal.
- DSCR true vs naive — 1.28x on the NOI a lender accepts vs the 1.69x a seller’s sheet implies. A RevPAR down-case (-15%) drops coverage to 0.84x — NOI falls ~2.3x as fast as revenue.
- SBA capital stack — equity + seller note (full-standby vs amortizing lever) + loan, with the injection rule, a real amortisation schedule, debt yield (12.7%), rooms coverage (4.98x) and a break-even ADR ($92.60).
- 3 segment profiles — Economy Highway (DSCR 1.31x), Midscale Select-Service (1.28x), Upper-Midscale Branded (1.13x): the premium segment trades at a lower cap, so you pay up and the coverage thins.
Excel model, 10 tabs, 5-year, every assumption editable and highlighted (Google-Sheets compatible — no macros); a PDF guide with sources; yield-on-cost (9.1%), cash-on-cash and a 5-year MOIC (1.58x, leverage-amplified; no live IRR by design). Numbers are industry-representative reference bands (STR/CoStar, HVS, CBRE, AHLA, AAHOA, BLS) — replace them with the target’s STR report and trailing-12 P&L. The first acquisition-underwriting model built around RevPAR, the FF&E reserve, the PIP and an SBA/DSCR gate — not the first hotel operating model. Educational planning tool — not financial, lending, legal or tax advice.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.