
0 ITEMS

Understanding Debt Sizing & Project Finance Ratios
Table of Content
- Understanding the Project Finance Model
- Project Finance Debt Sizing: Three Key Financial Debt Ratios You Can't Ignore
- How to Calculate Debt Sizing in Project Finance?
- Master Debt Sizing for Project Finance: Unleash the Power of Financial Modeling
Debt sizing in project finance determines how much borrowing a project can support without risking financial stability.
- It relies on key financial ratios like DSCR, LLCR, and PLCR to evaluate short, mid-term, and long-term debt capacity.
- Proper debt sizing ensures projects can meet their debt obligations while maximizing returns for investors.
- These ratios help lenders and stakeholders assess risk and decide on appropriate loan amounts.
- Using financial modeling, you can tailor debt structures to specific project cash flows and risk profiles.
Understanding these ratios and their calculations is essential for structuring sustainable project finance deals.
Understanding the Project Finance Model
The project finance model originated in ancient times, with early traces found in financing methods for maritime voyages and infrastructure projects in the Roman Empire. However, its modern development began in the 20th century, particularly in the oil and gas industry, where massive capital investments were needed to fund risky ventures. The first widely recognized use of project finance in its modern form occurred in the 1930s with the development of the Texas oil fields. It has also been instrumental in funding some of the world’s most iconic infrastructures. The Channel Tunnel, connecting the UK and France, is a notable example of a complex project finance model involving multiple stakeholders. Similarly, the project finance model also funded large-scale energy projects like the Tengiz Oil Field in Kazakhstan and renewable energy ventures like the Gemini Offshore Wind Farm in the Netherlands. Other famous examples include the expansion of Hong Kong International Airport and numerous toll roads, bridges, and power plants across the globe, all built through this financial mechanism.
Unlike traditional bank loans, project finance focuses on a project’s potential success rather than its sponsors’ creditworthiness. The project finance model involves a lender providing financing to a specific project, and the project’s cash flows are used to repay the loan. It is commonly used to fund large-scale capital investments, such as infrastructure and energy projects. Project owners can raise debt and equity financing without risking their balance sheets under the project finance model. The structure includes off-balance sheet financing, which allows companies to acquire funding for a project by setting up special-purpose vehicles (SPVs) that are legally separate from the company and do not appear on its balance sheet. This type of financing provides more flexibility for companies because it does not affect their credit ratings or the debt-to-equity ratio in their financial statements. Additionally, the project finance model can be structured as non-recourse financing, meaning the lenders cannot sue the sponsors if the special purpose vehicle fails to make timely debt payments. It provides an alternative form of funding that allows companies to manage risk while taking advantage of higher returns associated with long-term investments.
Just like other lenders, the project finance model closely evaluates financial debt ratios to assess a project’s risk profile, focusing on key metrics such as the Debt Service Coverage Ratio (DSCR), Loan Life Coverage Ratio (LLCR), and Project Life Coverage Ratio (PLCR). The DSCR measures the project’s ability to cover debt payments from its operational cash flows, serving as a critical indicator of short-term solvency. LLCR evaluates the long-term capacity of the project to repay debt over the life of the loan, factoring in future cash flows and reserves. PLCR extends this analysis to the project’s entire life, offering insight into whether the total project value is sufficient to cover outstanding debt. These ratios are essential for determining the ability to meet obligations, a project’s financial health, and the risk for lenders.

Project Finance Debt Sizing: Three Key Financial Debt Ratios You Can’t Ignore
In project finance, debt sizing is critical in determining the feasibility and sustainability of large-scale investments. Properly sizing the debt ensures that a project can meet its financial obligations while delivering expected returns to investors. Financial analysts rely on key financial debt ratios to assess the project’s ability to service the loan under various scenarios to achieve this balance. Understanding these essential metrics is crucial for structuring successful deals and mitigating risk in complex financial models.

Gauge Short-Term Solvency with the Minimum Debt Service Coverage Ratio
The minimum debt service coverage ratio is one of the three key financial debt ratios the project finance model must consider. It gauges a project or business’s solvency by comparing its cash flow to its debt obligations. Lenders often set a minimum debt service coverage ratio to ensure the project comfortably meets its debt obligations. They typically require a ratio greater than 1.0. A minimum DSCR below 1.0 suggests that the project needs to generate more cash flow to cover its debt service, which raises concerns about its short-term solvency and ability to meet financial commitments. In a project finance model, the minimum debt service coverage ratio (DSCR) is key in debt sizing. It helps lenders determine the maximum loan amount a project can responsibly carry. DSCR is calculated by dividing the net operating income by the total debt service.

Where:
- Net Operating Income (NOI) = Operating Income – Operating Expenses
- Total Debt Service = Principal + Interest payments on the debt
Sample DSCR Calculation
Let’s use the following assumption for a solar power plant:
- Annual Revenue from Power Sales: $2,500,000 (based on energy production and power purchase agreements)
- Annual Operating Expenses: $1,000,000 (maintenance, insurance, and other operational costs)
- Total Debt Service (Principal + Interest): $1,200,000 (total annual debt obligation)
First, we calculate the net operating income (NOI):
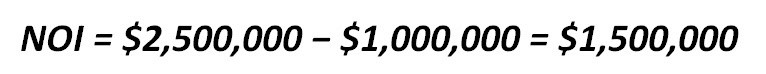
Then, we calculate the DSCR:

In this example, the DSCR is 1.25, which means the solar power plant generates 25% more income than required to cover its debt payments. Lenders would typically consider this a healthy DSCR, as it indicates that the plant is able to meet its debt obligations with some buffer.
Lenders determine the minimum debt service coverage ratio requirement. It can vary based on the type of loan, the borrower’s creditworthiness, and the project’s risk. A common minimum DSCR that lenders typically seek is 1.20. This implies that the borrower must generate 20% more income than the debt service to be deemed financially healthy.



































Loan Life Coverage Ratio (LLCR): Evaluating Mid-Term Debt Repayment Capacity
The loan life coverage ratio (LLCR) is one of the three financial debt ratios used in the project finance model to assess a project’s ability to meet its debt obligations over the loan’s entire life. It essentially measures the project’s long-term debt repayment capacity, providing lenders with insight into the sufficiency of future cash flows to cover debt repayments. A higher LLCR indicates a stronger ability to repay debt, reducing the perceived risk to lenders. The loan life coverage ratio is calculated by dividing the net present value (NPV) of the project’s cash flows available for debt service (CFADS) by the outstanding loan balance.
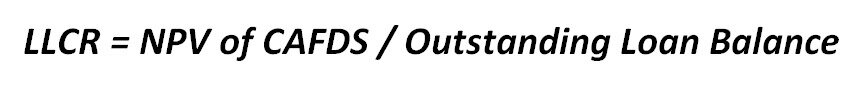
Calculating the net present value (NPV) of cash flow available for debt service (CFADS) in the loan life coverage ratio (LLCR) is essential because it measures the borrower’s ability to service the debt over the entire life of the loan. By discounting future CFADS to its present value, LLCR provides a mid-term view of debt coverage, factoring in the total expected cash inflows over the loan’s duration. It differs from the debt service coverage ratio (DSCR), which focuses on short-term performance by comparing current CFADS to immediate debt obligations. While DSCR evaluates near-term liquidity and risk, LLCR offers insight into overall loan sustainability and long-term financial health.
The cash flow available for debt service (CFADS) is typically the cash flow generated by the project after covering operating expenses before paying debt service. We use a separate formula to discount the CFADS to its NPV:
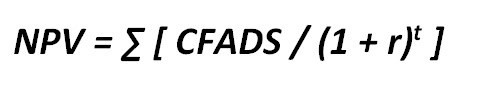
Where:
- The summation symbol ∑ means that you are summing up the discounted cash flows for each period over the life of the loan.
- CFADS is the cash flow available for debt service at time t
- t is the time period
- r is the discount rate (usually the loan interest rate or the weighted average cost of capital)
Sample LLCR Calculation
Here’s a simplified example of a loan life coverage ratio calculation for an Ammonia Power Plant with the following assumptions:
- The Ammonia Power Plant has an outstanding loan balance of $50 million.
- The discount rate is 8% (0.08).
- The projected CFADS over the next five years is $10 million in Year 1, $12 million in Year 2, $15 million in Year 3, $18 million in Year 4, and $20 million in Year 5.
First, we calculate the NPV of CFADS:
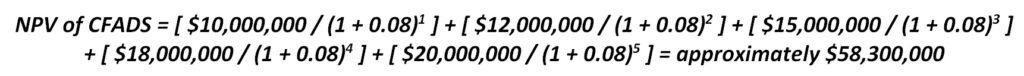
Then, we calculate the loan life coverage ratio:
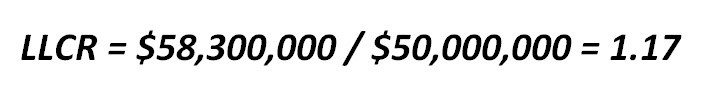
So, the LLCR for this Ammonia Power Plant project is approximately 1.17. It indicates that the project’s cash flows are sufficient to cover 1.17 times the outstanding loan balance over the project’s life.
Project Life Coverage Ratio (PLCR): Key for Restructuring, Refinancing, and Long-Term Cash Flow Management
Various events may impact debt management over a project’s life, such as the need to refund or restructure existing obligations or unexpected delays and interruptions in cash flow. In these situations, the project life coverage ratio (PLCR) comes into play. It assesses the project’s ability to cover its debt by evaluating projected cash flows over the remaining life of the project. This is one of the three financial debt ratios that help stakeholders make informed decisions regarding the project’s long-term financial sustainability and debt management.
The project life coverage ratio (PLCR) is calculated by dividing the net present value (NPV) of the project’s cash flows over its remaining life by the outstanding debt. This ratio indicates how much the project’s future cash flows can support debt repayment beyond the initial loan term. Lenders use the project life coverage ratio (PLCR) as a conservative measure to ensure that even under stress scenarios, the project can still generate adequate cash flow to meet its debt obligations.
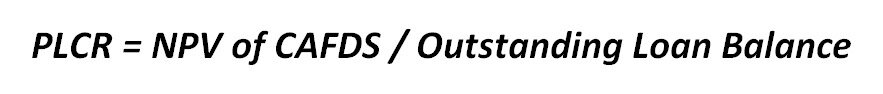
Where:
- NPV of CFADS refers to the sum of the project’s expected future cash flows, discounted back to the present value.
- Outstanding Loan Balance refers to the total amount of debt remaining on the project at a given time.
Sample PLCR Calculation
Let’s have an example project life coverage ratio calculation using some reasonable assumptions for a Carbon Capture and Sequestration (CCS) facility where we assume the project lifetime of ten years to simplify the calculation:
- The projected cash flows (CFADS) for the Carbon Capture and Sequestration (CCS) facility are expected to start at $10 million in Year 1, increase to $12 million in Year 2, and rise to $14 million in Year 3. The peak is reached in Years 4 and 5, with cash flows of $15 million each. In Year 6, the CFADS decreases slightly to $14 million, gradually declining to $13 million in Year 7, $12 million in Year 8, $10 million in Year 9, and finally $8 million in Year 10. This projection reflects the facility’s expected performance over the next ten years.
- The discount rate is 8% (0.08).
- The outstanding debt is $50 million at the start of the calculation.
Based on the assumptions provided, the NPV of the CFADS is approximately $83.49 million. Let us now calculate the project life coverage ratio:
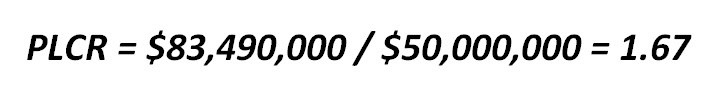
The project life coverage ratio (PLCR) is 1.67. It means the projected cash flows when discounted over the ten years, cover the outstanding debt 1.67 times, indicating reasonable debt coverage for the project.
The project life coverage ratio essentially measures how well the project’s future cash flows can cover the remaining debt, indicating the project’s long-term financial viability. A higher PLCR indicates a stronger ability to service debt. On the other hand, the loan life coverage ratio focuses on the remaining loan term, evaluating the project’s cash flows only over the life of the debt. DSCR is more immediate, looking at the project’s ability to cover debt payments in the short term, typically over a year, by comparing annual cash flows to yearly debt service. In summary, PLCR has a long-term view, LLCR a mid-term view, and DSCR a short-term view of debt coverage.
How to Calculate Debt Sizing in Project Finance?
Debt sizing in project finance is the process of determining the maximum amount of debt a project can support based on key financial debt ratios such as the Debt Service Coverage Ratio (DSCR), Loan Life Coverage Ratio (LLCR), and Project Life Coverage Ratio (PLCR). Together, these ratios help ensure that the project can maintain adequate debt service over time while maintaining financial stability.
Debt Sizing Using the DSCR
The formula for determining the maximum loan amount in project finance using the DSCR is:

Where:
- Forecasted Cash Flow is the expected cash flow of the project.
- Minimum/Target DSCR is the minimum or target ratio of cash flow to debt servicing the principal and interest payments).
- Loan Term is the duration of the loan.
- Interest Rate is the annual interest rate on the loan.
Sample Debt Sizing Calculation Using the DSCR
Let’s use the following assumption for a solar power plant:
- Forecasted Cash Flow: $5,000,000 per year (based on the energy output and revenue from selling electricity)
- Minimum DSCR: 1.4 (typical for a solar power project)
- Loan Term: 15 years (as is often seen in project finance for energy projects)
- Interest Rate: 6% (0.06 in decimal form)
First, we divide the forecasted cash flow by the minimum debt service coverage ratio (DSCR):
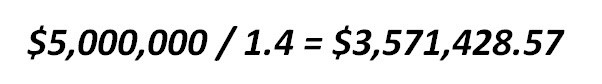
Then, we multiply the above quotient by the loan term:
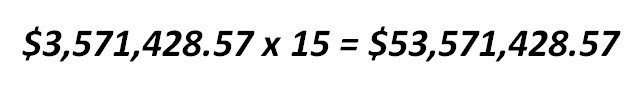
Last, we multiply the above product by the interest rate:
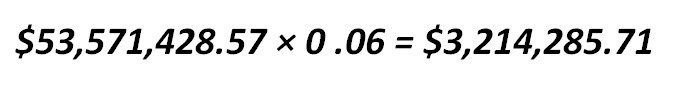
The maximum loan amount for the solar power plant would be approximately $3,214,285.71. This result assumes a basic linear approach to loan calculation without factoring in other complex elements like repayment structure, debt covenants, or amortization schedules that might apply in real-world scenarios.
Debt Sizing Using the LLCR
The formula to calculate the debt size in project finance using the Loan Life Coverage Ratio (LLCR) is:

Where:
- NPV of Cash Flows Available for Debt Service: The net present value of the project’s future cash flows dedicated to repaying the debt.
- Target LLCR: The desired loan life coverage ratio set by the lenders or project participants. It is typically greater than 1 to ensure that cash flows exceed debt service obligations.
Let’s walk through a sample calculation for determining the debt size of an Ammonia Gas Plant using the loan life coverage ratio under the following assumptions:
- NPV of Cash Flows Available for Debt Service = $100,000,000
- Target LLCR = 1.5
- Loan Term = 10 years
- Interest Rate = 5% (0.05 in decimal form)
First, we calculate the ratio of NPV to target loan life coverage ratio (LLCR):
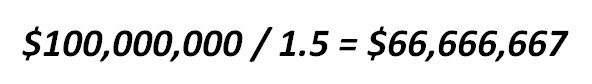
Then, we multiply the loan term:
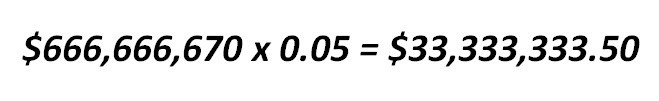
Last, we multiply the interest rate:
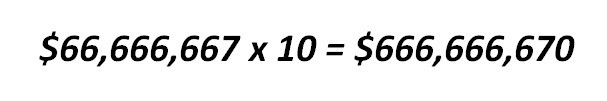
This value represents the amount of debt that can be supported by the project’s cash flows, given the assumed LLCR, loan term, and interest rate. Again, this result assumes a basic linear approach to loan calculation without factoring in other complex elements like repayment structure, debt covenants, or amortization schedules that might apply in real-world scenarios.
Debt Sizing Using the PLCR
The formula for calculating the maximum loan amount using the Project Life Coverage Ratio (PLCR) in project finance is the same as that used for the Loan Life Coverage Ratio (LLCR), as both use the ratio of the project’s cash flow to debt service to determine loan size. However, their main difference lies in the time horizon considered: PLCR is based on the cash flow generated over the entire life of the project. At the same time, LLCR focuses only on the cash flows available during the loan’s tenure. Consequently, PLCR often gives a broader perspective, while LLCR is more conservative, reflecting mid-term risks.
| Disclaimer: Calculating debt sizing in project finance using key financial debt ratios involves complex methodologies. Our sample calculations use a simplified linear approach to loan calculation without accounting for other intricate factors, such as variable interest rates or cash flow constraints. We recommend utilizing professional Project Finance financial models tailored to your specific project requirements for more accurate and comprehensive results. |
Master Debt Sizing for Project Finance: Unleash the Power of Financial Modeling
Debt sizing in project finance revolves around determining the optimal amount of debt a project can sustain while maintaining financial stability. This process involves evaluating key financial debt ratios – DSCR for short-term risks, LLCR for mid-term risks, and PLCR for long-term risks.
By leveraging the power of financial modeling, you can precisely assess a project’s capacity to handle debt while maximizing returns for investors. Great financial models offer a detailed, data-driven approach to calculating the key financial debt ratios, ensuring all stakeholders have confidence in the project’s financial health. With these tools, you can tailor debt structures to match the specific needs of your project, minimize risks, and attract financing on favorable terms. Unleash the full potential of financial modeling to master debt sizing and drive your project toward success.
You might also like:
- Understanding the Debt Service Coverage Ratio: An Essential Metric for Financial Analysis
- 10 Main Elements of a Business Plan
- Understanding What is Yield to Maturity and Why It Matters
- FAQs on Funding and Financing
- Understanding Insurance Policies: A Beginner’s Guide
- How to Build a Capitalization Table
- 10 Tips to Develop a First Class Business Valuation Report
- Mastering Business Finance: The Three-Statement Financial Model
- Financial Ratios Analysis and Its Importance
- How to Secure Seed Financing?
- Commercial Real Estate Valuation Methods: Helping Investors in Taking Informed Decisions
- Financial Model Templates Easy to Use
- How to Valuate a Company: Common Valuation Approaches
- Understanding the Levelized Cost of Energy Formula
- Debt Service Coverage Ratio (DSCR) for Project Finance
- Creating a Business Plan for your Food Truck Business
- How to Make a Startup Financial Plan for Fundraising?
- Financial Modeling for Startups and Small Businesses
- Project Finance
- Fundraising Project Plan Template in Excel