
0 ITEMS

Pest Control Company Acquisition Financial Model
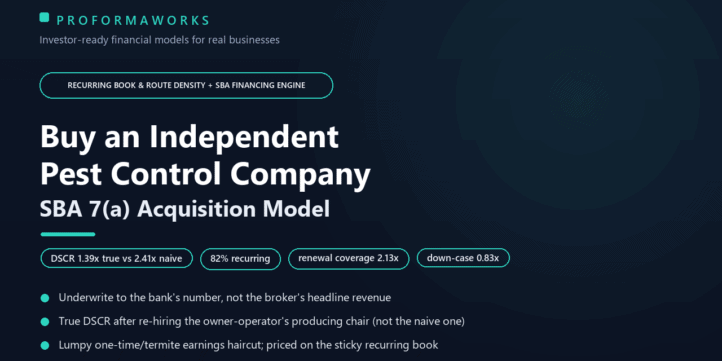
A professional Excel and Google Sheets financial model built for buyers of a pest control company. Underwrite the deal, size the SBA 7(a) loan and present bank-ready numbers to your lender or investor. Includes a route-density and recurring-book engine, SBA 7(a) and DSCR, a 5-year pro forma, three scenarios and a one-page dashboard.
| Financial Model, Service Businesses |
| 5-year Financial Projections, Business Valuation, Cash Flow Projections, Debt Service Coverage, Financial Model, Loans, Mergers and Acquisitions Model, Pro-Forma |


Buy an independent pest control company and underwrite it the way an SBA lender actually will. This is a lender-ready acquisition model for a single-branch pest control business, built around the two things a real underwriter tests and a broker quietly overstates: how much of the revenue is a recurring route book you can bank on, and what it costs to replace an owner who runs a route or sells.
A recurring route book and a route-density engine. Revenue is built bottom-up from recurring accounts (residential and commercial) times their average annual value, plus one-time and termite/WDO work. The route-density block makes the operational margin lever explicit — stops per technician per day and revenue per tech — because in pest control density is what moves gross margin. The base case runs about $1.70M revenue, 82% recurring, roughly 11 stops per tech per day and about $155k revenue per technician.
Honesty part one — recurring vs one-time quality. One-time and termite jobs are real money, but they are lumpy, non-contractual, and do not deserve the multiple a sticky recurring route book earns. The model splits SDE into its recurring and one-time halves, prices each at its own multiple, and shows exactly how much a buyer overpays (about $146,920 on the base case) by applying the full recurring multiple to lumpy one-time earnings.
Honesty part two — the owner-operator replacement. In most single-branch companies the owner runs a route or is the top salesperson. If the buyer will not sit in that seat, they must re-hire it. The model deducts that cost to reach Adjusted EBITDA and shows the true DSCR (1.39x on the base case) next to the naive broker-style DSCR (2.41x). The gap is the owner’s own production — what separates a financeable route business from one that looks great on the CIM and gets declined.
What you get: a Recurring Book & Route Density engine; an SDE & valuation sheet with the recurring-vs-one-time quality panel and the owner-operator replacement; a 3-part SBA 7(a) capital stack with a full-standby vs amortizing seller-note toggle; a DSCR & Debt gate with true DSCR, naive DSCR, debt yield, recurring-earnings coverage (2.13x) and a customer-churn down-case DSCR of 0.83x; a 5-year P&L, Returns & Exit and a Dashboard sensitivity grid; a 3-way profile toggle; a 23-page PDF user guide; and a Benchmarks & Sources tab. Machine-verified across three engines (67 automated checks, zero errors). Works in Excel and Google Sheets — no macros. Educational planning tool, not financial or investment advice; verify the seller’s route revenue, retention history and your SBA term sheet before relying on any number.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.