
0 ITEMS

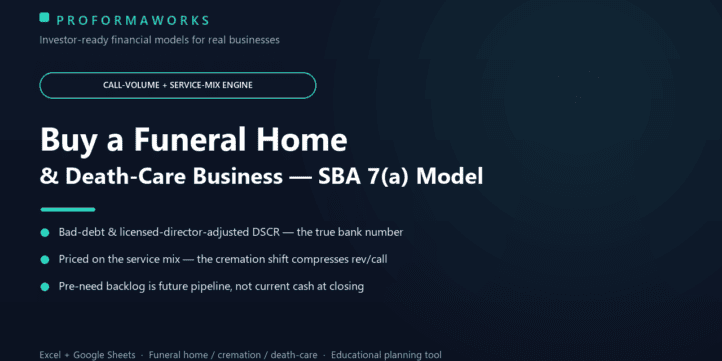
Funeral Home Acquisition & SBA Financial Model
A professional Excel and Google Sheets financial model built for funeral home and death-care buyers. Underwrite the deal, size the SBA 7(a) loan and present bank-ready numbers to your lender or investor. Includes a call-volume and service-mix engine, pre-need backlog, SBA and DSCR, a 5-year pro forma, three scenarios and a one-page dashboard.
| Financial Model, Real Estate, Service Businesses |
| Break-Even, Business Valuation, Cash Flow Projections, Debt Service Coverage, Financial Model, Loans, Mergers and Acquisitions Model, Pro-Forma |


Most funeral-home templates are startup or operating forecasts, and most brokers headline a call count. But a funeral home’s earnings hinge on its revenue per call — and the service mix is shifting. The US cremation rate is ~63% and rising toward ~82% by the mid-2040s (NFDA); direct cremation is ~25% of the calls but only ~10% of the revenue. A firm can look busy while its revenue per call quietly erodes. This 5-year, SBA-lender-ready model reads the firm the way a disciplined buyer and a bank do — on the blended revenue per call, normalized SDE, and the trend.
What it does
- Call-Volume + Service-Mix engine — at-need calls times a blended revenue per call from three service types (a traditional burial, a cremation with a service, a low-cost direct cremation), each at its own price. The ~$6,082 blended revenue per call and the ~63% cremation rate, not the raw call count, decide the deal.
- The honesty a broker’s sheet skips. It recognizes bad debt / uncollectibles as an explicit line, hires a licensed funeral director to replace the owner who works the calls and sells the pre-need, and prices on SDE after those — so the true DSCR (1.36x) sits next to the naive broker DSCR (1.89x). The gap is the director and the bad debt.
- Pre-need as future pipeline, not cash. The pre-need backlog is funded into a trust or insurance and recognized at-need, over years — a lender won’t treat it as today’s cash flow, and you shouldn’t pay a current-earnings multiple on it. The model prices the at-need business and shows the backlog separately.
- Real estate own vs lease. A toggle for a leasehold base case (rent in overhead, 10-year SBA term) versus a fee-simple purchase of the building and any crematory (25-year term).
- The down-case that matters. The sector’s #1 structural risk is the accelerating cremation shift. An 8-point mix move toward direct cremation and a 4% call slip drops DSCR to 0.88x — below the 1.25x floor, because overhead (staff, facility, fleet) is fixed.
- SBA 7(a) capital stack — buyer equity, a seller note (full-standby vs amortizing toggle as the DSCR lever), and the SBA loan that fills the rest, with the lender’s DSCR gate and a 5-year cash-on-cash and equity-multiple exit. No IRR is printed (deliberately — on one small deal it is hostage to the exit multiple).
Base case (Balanced Community, editable): ~350 at-need calls, cremation rate 63%, revenue $2.13M at a 62% gross margin, SDE $532,660 (25%), Adjusted EBITDA $437,660, price 3.75x SDE = $1.997M, SBA loan $1.76M at 80.8% leverage, true DSCR 1.36x vs naive 1.89x, cremation-shift down-case 0.88x, full-service coverage 4.20x, MOIC 4.58x.
Inside: a 10-sheet Excel model (every calc a formula, Google-Sheets-safe, no macros), a 23-page PDF user guide, and a benchmarks sheet with sourced ranges. Three firm profiles (Burial-Traditional / Balanced Community / Cremation-Forward) reload the multiple, working-capital peg, capex and bad-debt rate. Educational planning tool, not financial, legal, tax or investment advice.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.