
0 ITEMS

Co-Located Solar + BESS Model | Shared-POI Constraint & ITC Qualification Test
Price a hybrid solar-plus-storage project twice: as the developer presents it, and as it survives a shared point of interconnection and an annual tax-credit qualification test.
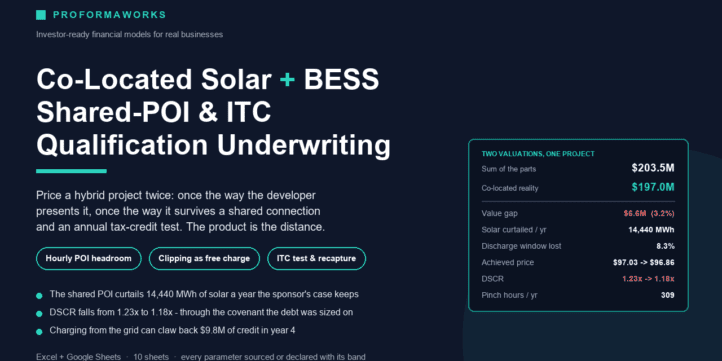


A hybrid solar-plus-storage project is not the solar project plus the battery project. Both assets sit behind one point of interconnection, so they compete for export capacity hour by hour. The battery’s investment tax credit depends on where its charging energy comes from, and that is tested every year, not once at closing. A valuation built by adding two standalone forecasts together misses both constraints by construction.
This model prices the same project twice and reports the distance between the two numbers.
Sum of the parts is what a developer deck shows: the solar farm at its own yield plus the battery at its own revenue stacking, added together as if they were two projects on two separate grid connections. Co-located reality is what survives underwriting: a single export limit capping combined output hour by hour, a battery that must charge mostly from the array to keep its credit, and inverter clipping as free charging energy but only in the hours when clipping actually exists.
The engine is a 12-month by 24-hour dispatch grid. For every month-hour combination the model computes how much export capacity is left after the solar array has taken its share, and that residual headroom is what the battery has to work with. The constraint bites in two distinct ways. The array itself is curtailed whenever its AC output exceeds the export limit. And the battery loses discharge hours precisely when it wants them most, because on a summer-peaking price curve some of the expensive hours arrive while the sun is still up. The model counts those hours explicitly.
The tax credit is treated as an annual test with a recapture ladder rather than a lump sum at closing. Storage co-located with a renewable generator has historically qualified only when a minimum share of charging energy came from the generator rather than the grid, pro-rata above the threshold and zero below it, with credit already claimed clawed back if a disqualifying change happens during the vesting period. Switch grid charging on and the model shows the arbitrage gained, the credit at risk, the year the recapture lands, and how many years of extra arbitrage would be needed to repay it. That trade-off is what makes charging policy a financeable variable instead of a footnote.
Debt is then sized on each cash flow case using the same lender test, and the model answers the question a credit committee actually asks: if the sponsor’s debt is drawn, what coverage does the real project deliver?
What you get: ten sheets, every input editable and highlighted; every parameter either traced to a public source or flagged as a declared input with the band it should sit in; a five-page guide that walks a real deal through it in order. No macros, no external links, no structured tables – it opens in Excel, LibreOffice and Google Sheets.
A free 8-page PDF preview shows the sheets, the base case solved and the method, so you can judge the model before paying for it.
The threshold selector is not a legal statement and the price shape is not a forecast. The model tells you the consequence of a rule and a market you specify. Confirm the tax rule that applies to your project with counsel; nothing here is tax advice.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.