
0 ITEMS

Private Debt & Credit Fund Financial Model – 10-Year Forecast, NAV, LP/GP Waterfall & Stress Tests
An editable 10-year private credit fund model with 40 quarterly periods, 50 prepared loan slots, 15 fictional sample loans, credit cash flows, PIK, defaults and recoveries, revolving fund leverage, NAV, a European-style LP/GP waterfall, investor IRR/DPI/RVPI/TVPI, four integrated scenarios and directional stress analysis. Includes 23 worksheets, eight native dashboard charts and a 33-page English PDF guide.
PRIVATE DEBT & CREDIT FUND FINANCIAL MODEL – 10-YEAR SIGNATURE EDITION
Model loan-level credit performance, fund financing, liquidity and LP/GP investor economics in one connected Excel framework.
The Private Debt & Credit Fund Financial Model by SheetworksStudio is a comprehensive, editable 10-year private credit forecasting system.
Model origination, floating and fixed-rate coupons, payment-in-kind (PIK) income, amortization, prepayments, expected defaults, recoveries and refinancing through to fund-level capital calls, distributions, NAV and investor returns.
Built for private credit analysts, direct-lending teams, fund sponsors, asset managers, financial consultants and advanced finance professionals.
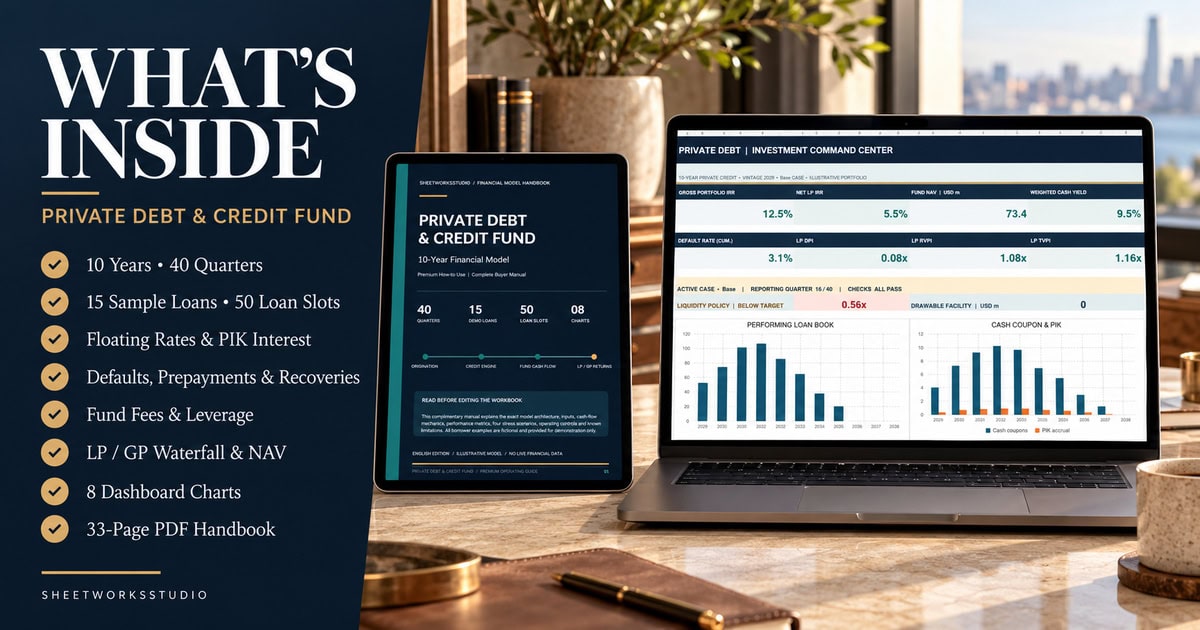
The package contains 23 interconnected worksheets, 40 quarterly periods, 15 fictional sample loans, 50 prepared loan slots, four selectable credit scenarios, eight native Excel dashboard charts and a detailed 33-page English PDF handbook.
📊 1. EXECUTIVE DASHBOARD & INVESTOR REPORTING
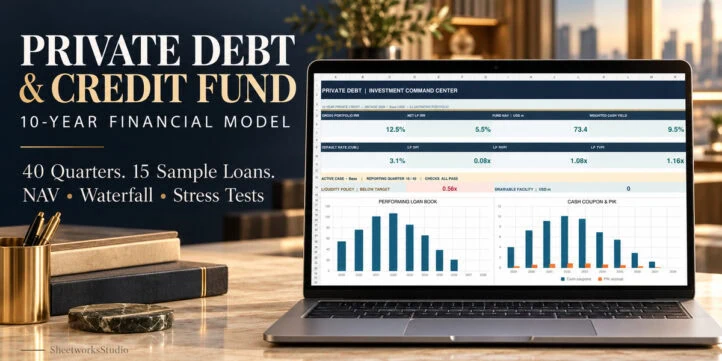
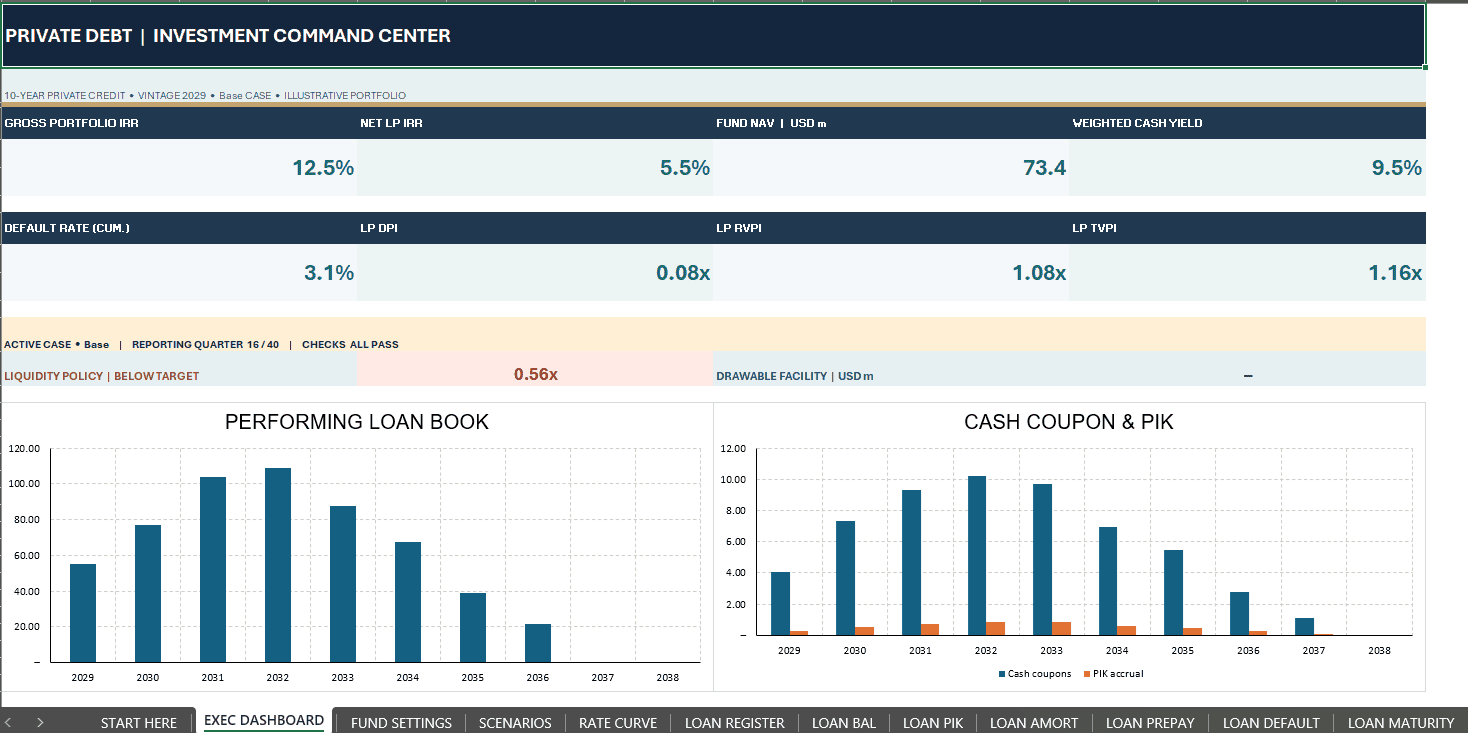
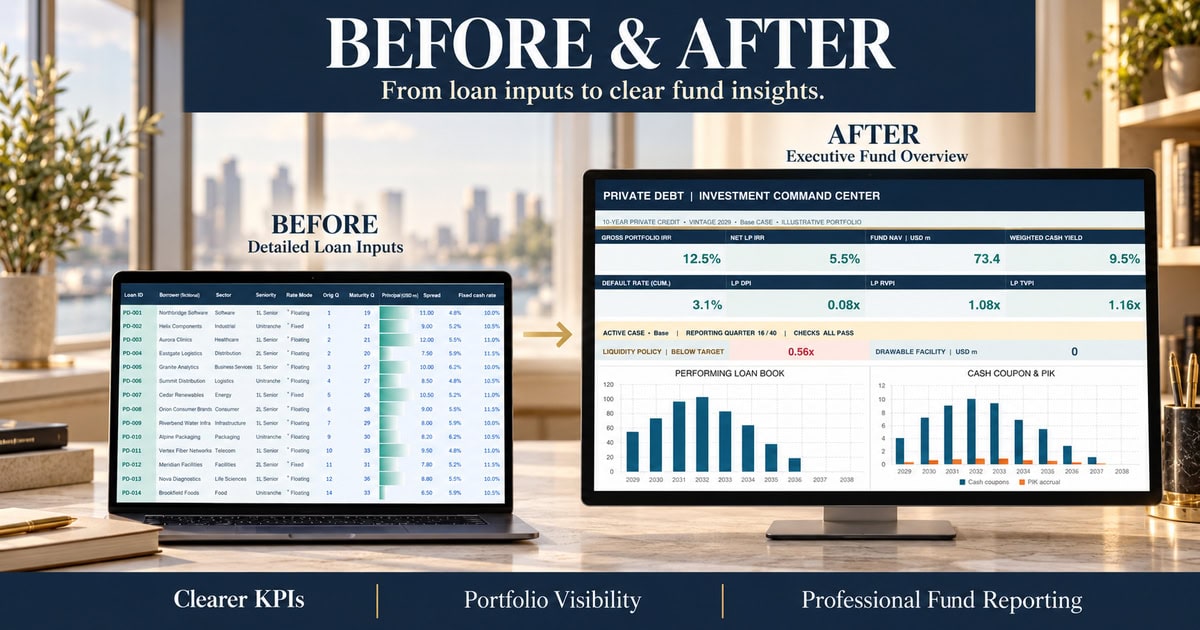
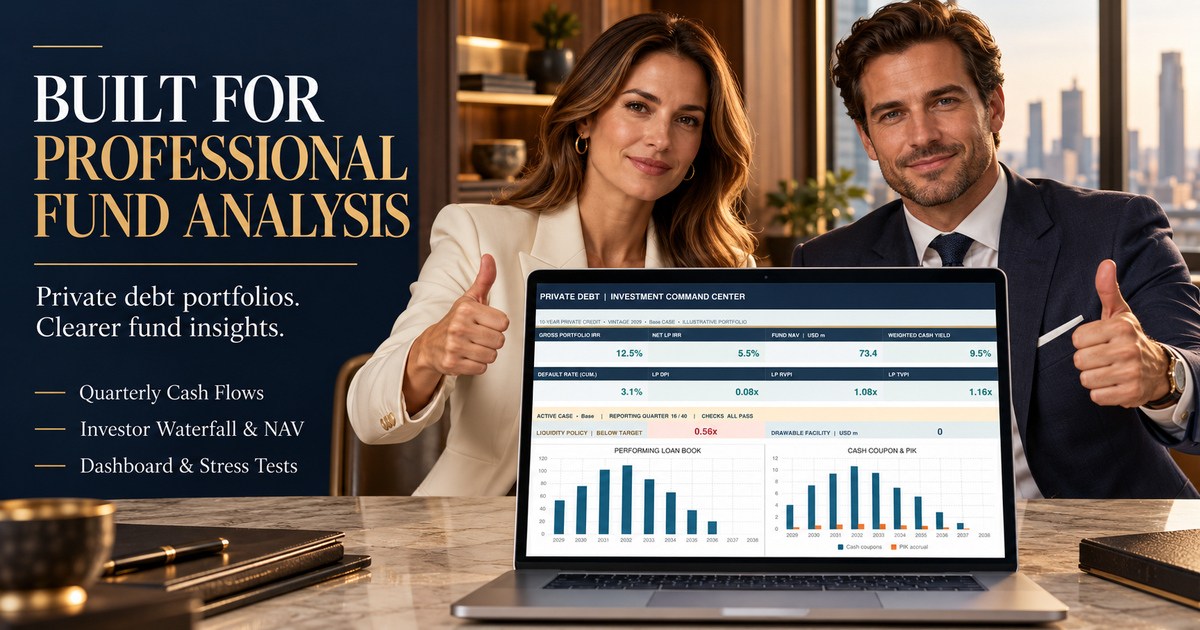
The Executive Dashboard consolidates gross portfolio IRR, net LP IRR, fund NAV, weighted cash yield, cumulative default rate and LP investor multiples (DPI, RVPI and TVPI).
Additional indicators display current liquidity coverage, active scenario, selected reporting quarter and drawable facility headroom.
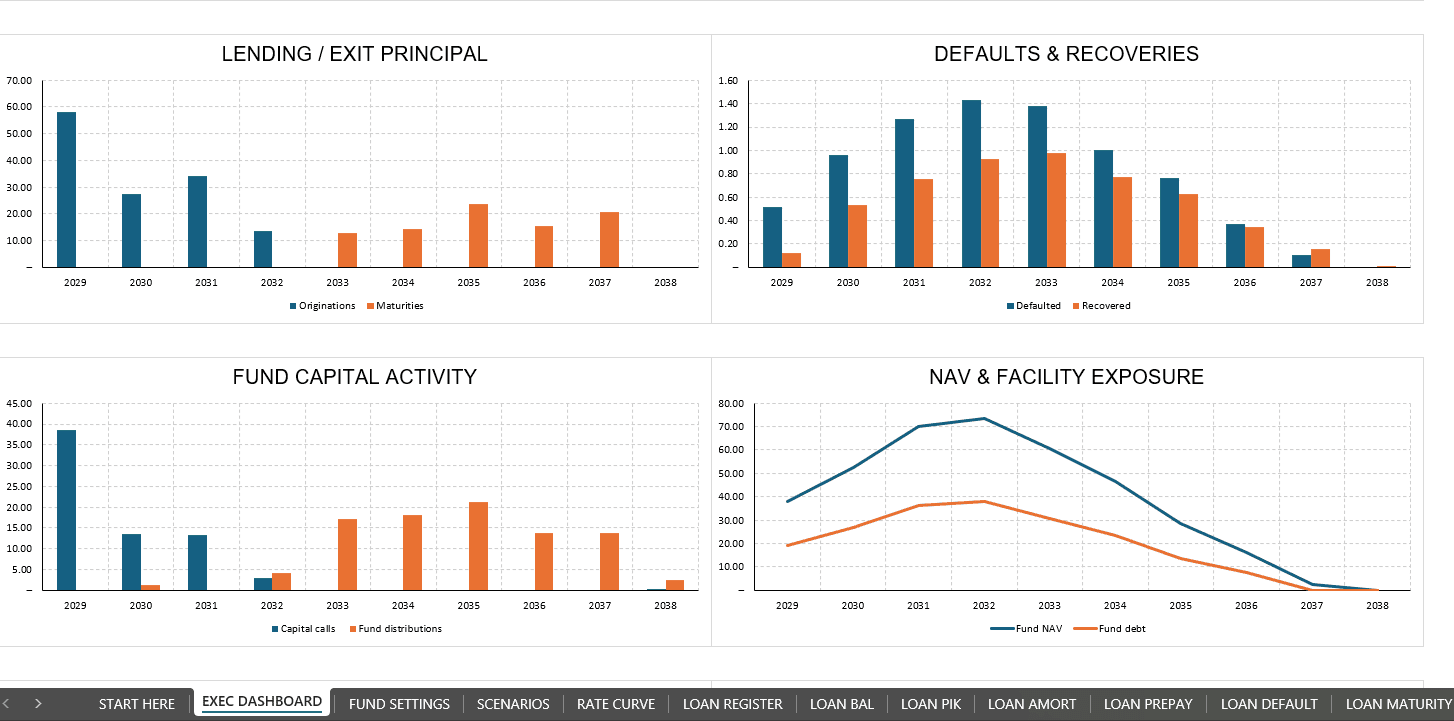
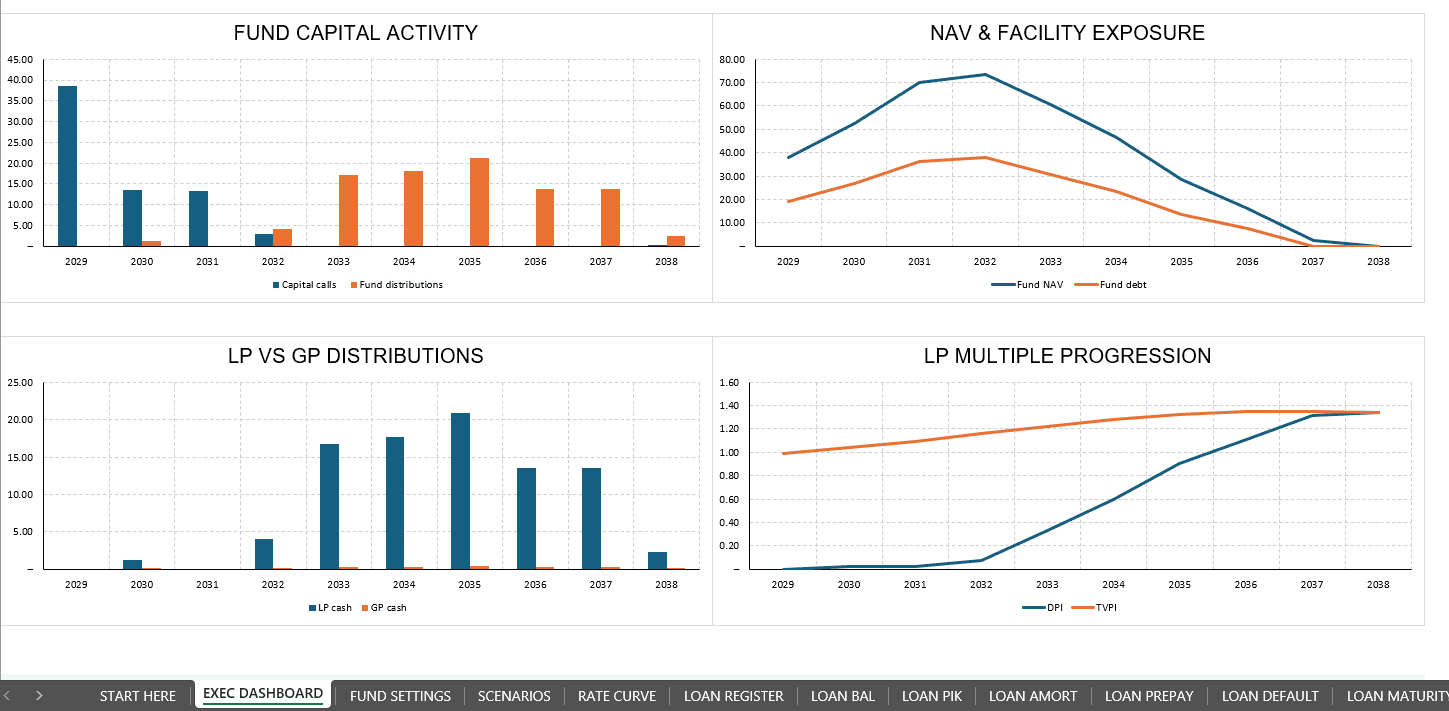
Eight data-linked native charts present:
✓ Performing Loan Book
✓ Cash Coupon & PIK
✓ Lending / Exit Principal
✓ Defaults & Recoveries
✓ Fund Capital Activity
✓ NAV & Facility Exposure
✓ LP vs GP Distributions
✓ LP Multiple Progression
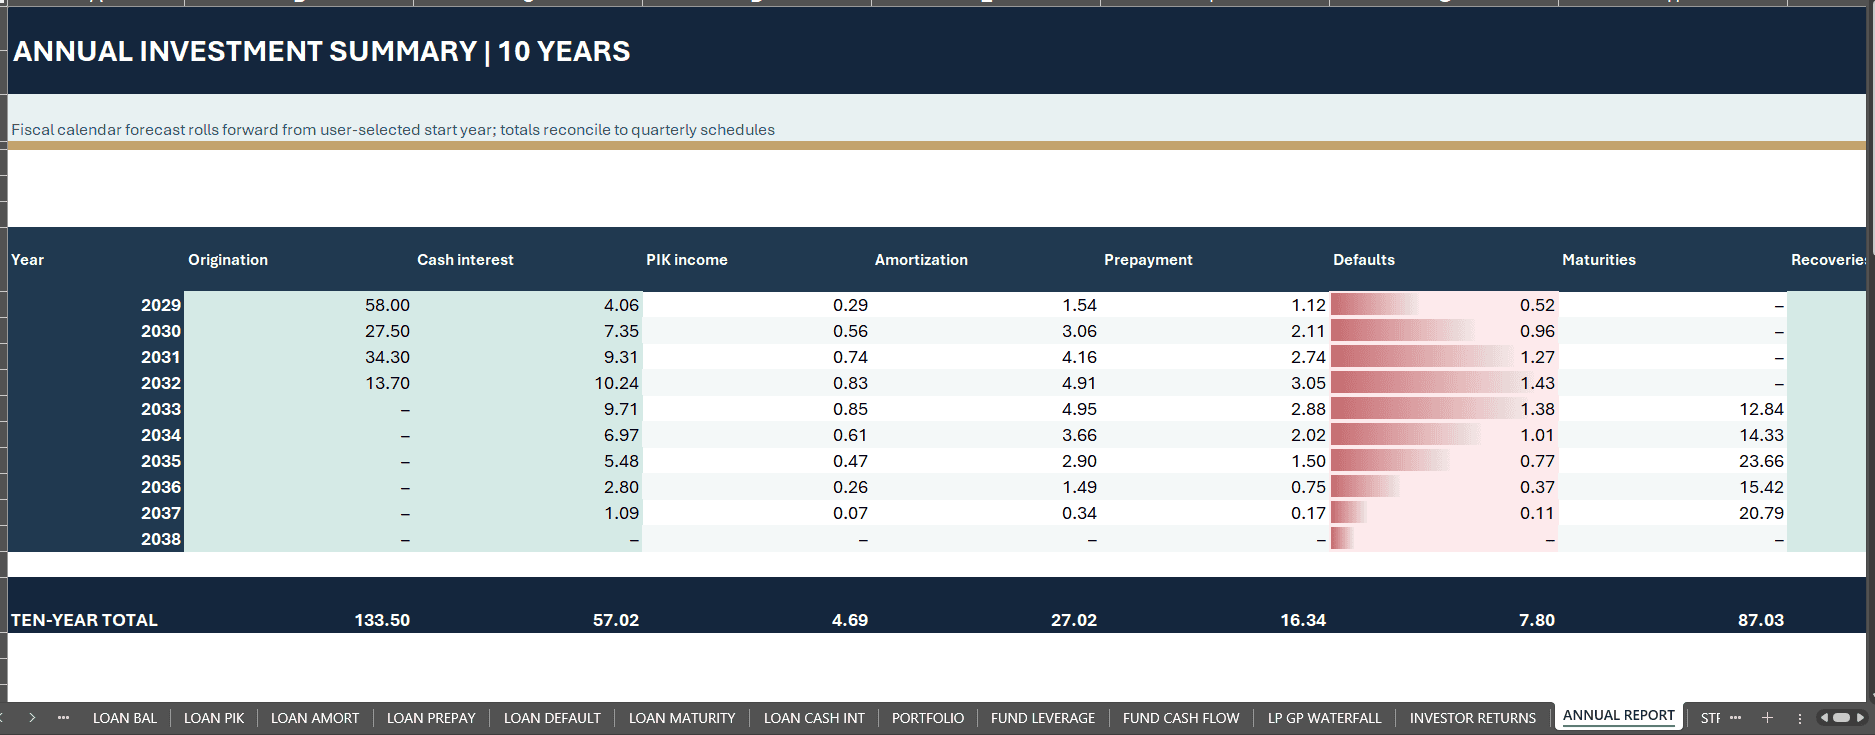
The ten-year ANNUAL REPORT summarizes the underlying quarterly data. Full-horizon IRR measures and selected-quarter NAV/LP multiples are clearly distinguished.
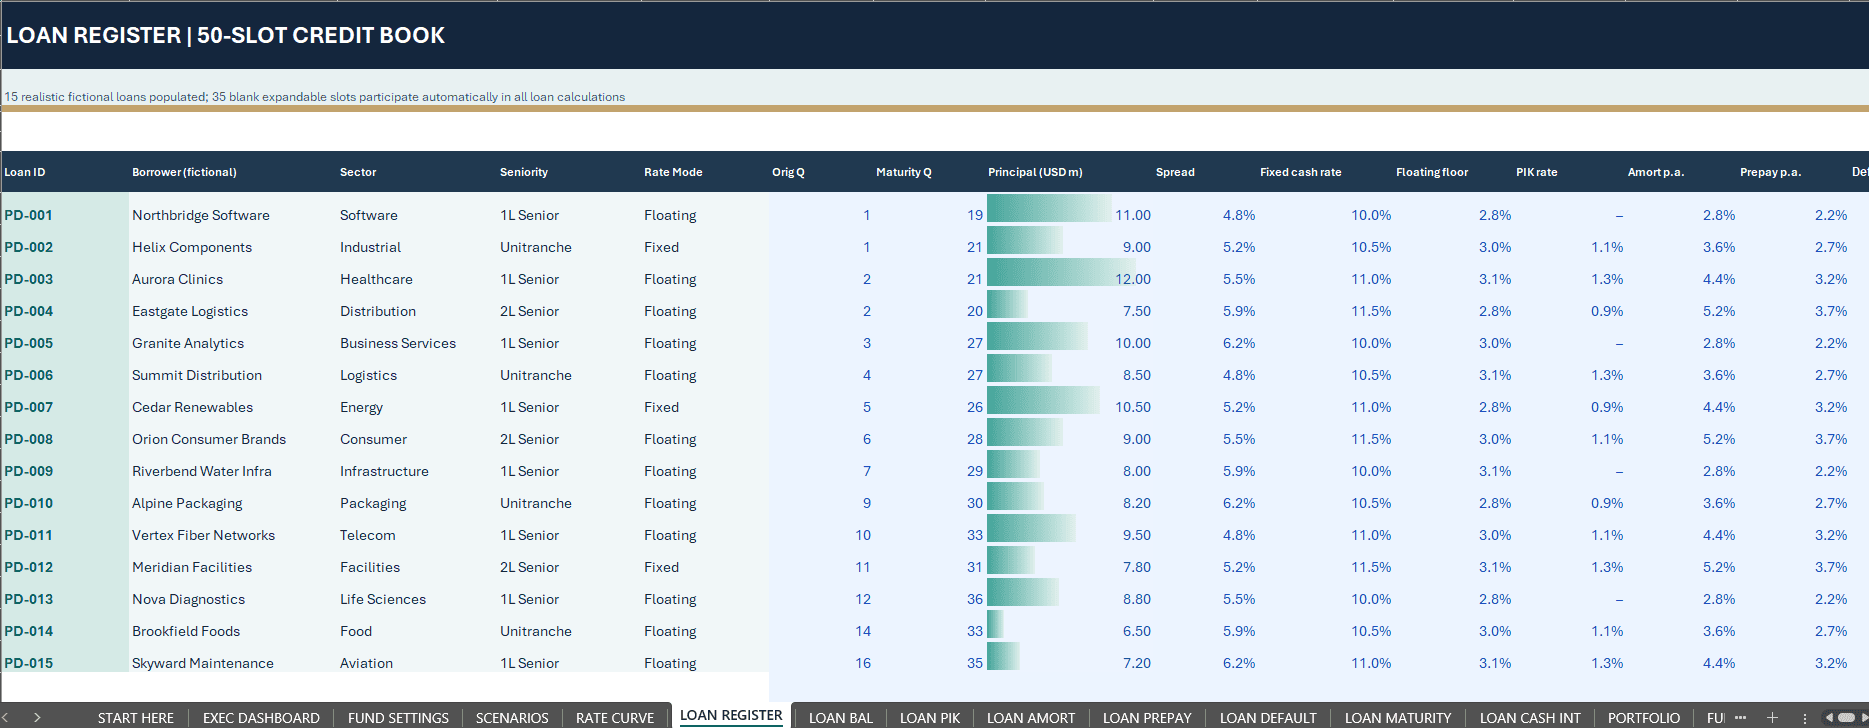
▦ 2. LOAN REGISTER & CREDIT CASH FLOW ENGINE
Model 15 fictional demonstration loans and use 35 additional prepared slots for a maximum of 50 loan records.
Editable loan assumptions cover borrower/sector identification, seniority, origination and maturity quarters, initial principal, fixed/floating loan terms, credit spread, rate floors, cash interest, PIK rates, scheduled amortization, voluntary prepayments, expected defaults, loss severity, delayed recoveries and relevant origination/exit fees.
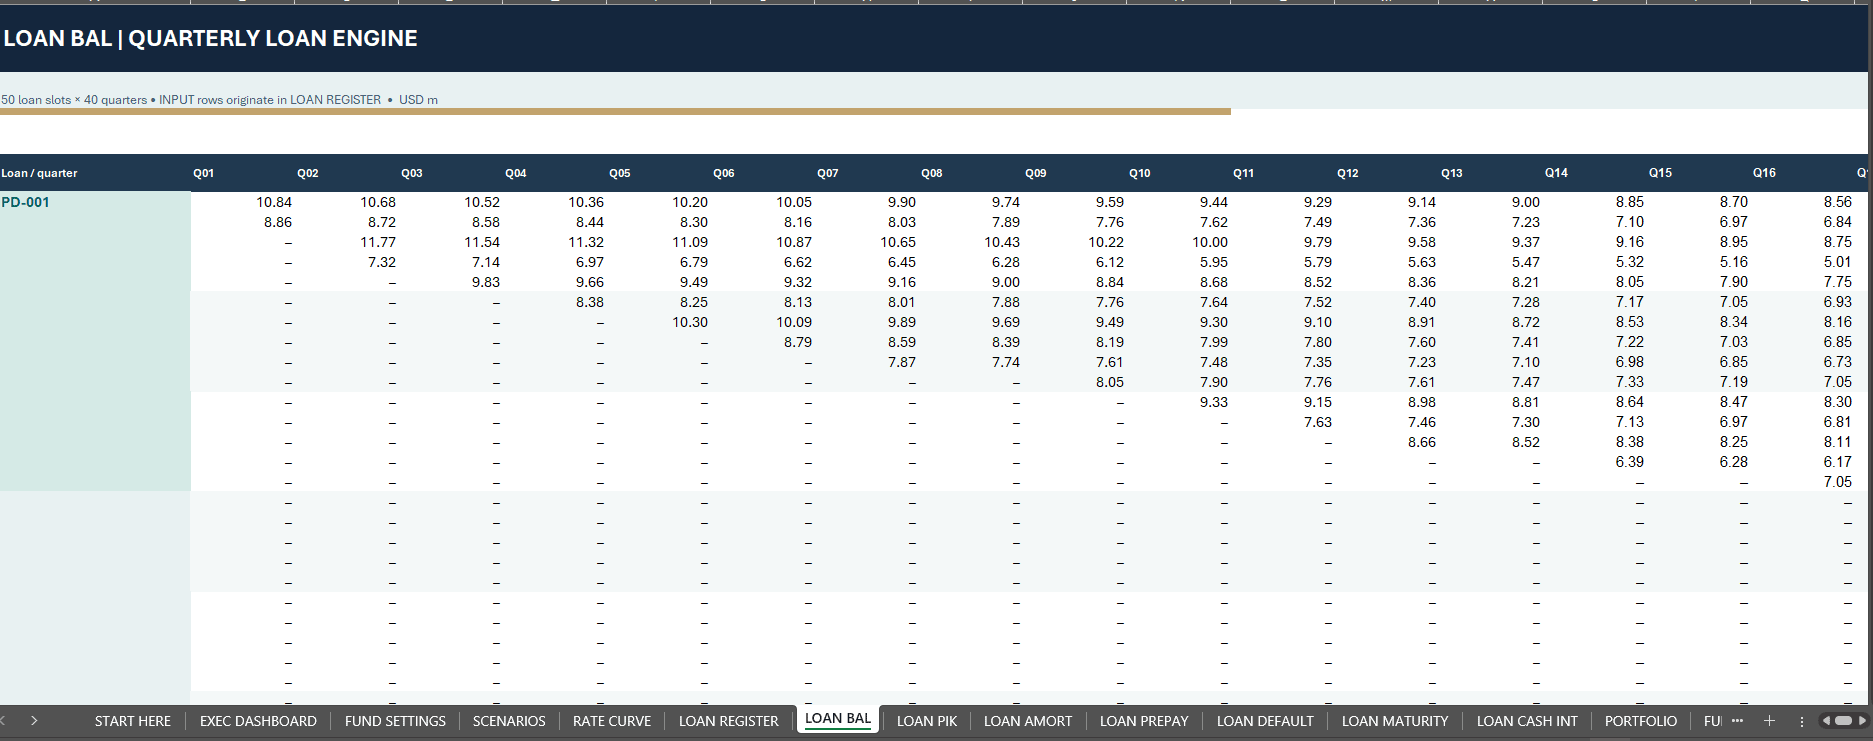
Seven connected credit calculation schedules calculate:
✓ Performing Principal Balances
✓ Quarterly PIK Accrual
✓ Scheduled Amortization
✓ Principal Prepayments
✓ Expected Credit Defaults
✓ Maturity Repayments
✓ Cash Coupon Interest
An editable quarterly reference-rate curve supports floating-rate analysis.
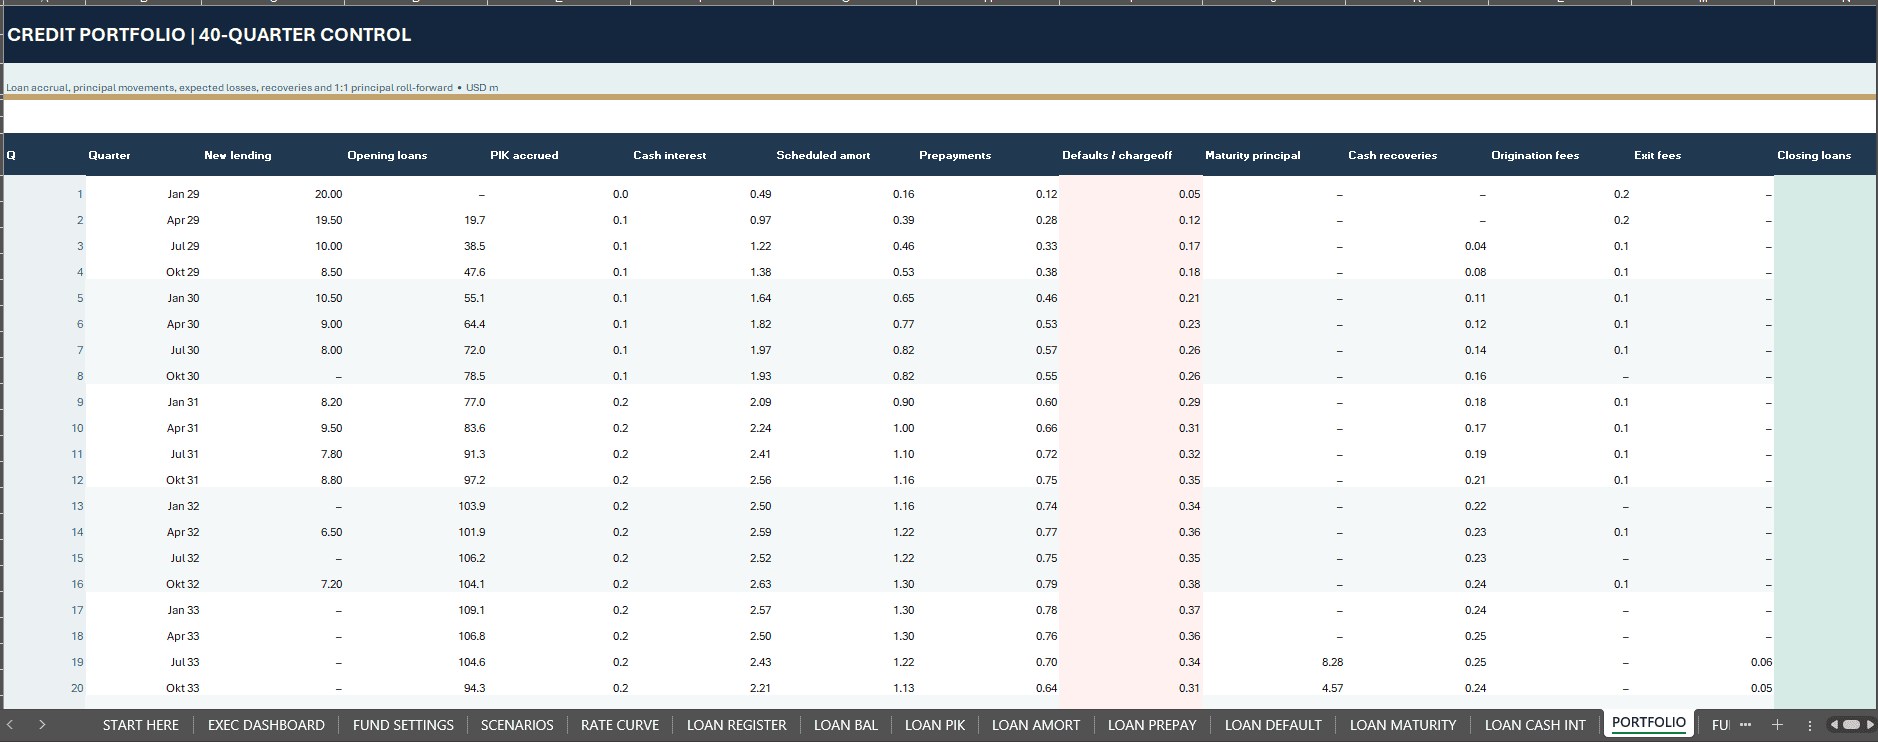
Defaults are expected-value credit events rather than stochastic borrower-by-borrower simulations. Cash recoveries are modeled separately from estimated credit losses and uncollected recovery receivables.
🏦 3. FUND FINANCING & LIQUIDITY CONTROL
A revolving credit facility connects loan deployment, borrowing-base constraints and available liquidity.
Configure the committed facility ceiling, borrowing-base advance rate, benchmark interest assumptions, credit spread, draw fees and minimum cash requirements.
The funding schedules calculate revolver draws, repayments, financing costs, outstanding balances and drawable credit.
The FUND CASH FLOW schedule integrates credit income, lending and principal collections, management fees, administration, servicing costs, facility debt movements, capital calls and distributions.
Liquidity coverage and warning indicators are displayed alongside accounting checks to distinguish funding risk from mathematical consistency.
🤝 4. LP / GP EUROPEAN WHOLE-FUND WATERFALL
Explore a simplified European-style LP/GP distribution methodology.
The waterfall includes:
✓ Proportional LP and GP Capital Contributions
✓ Return of Contributed Capital
✓ Preferred Return Accrual and Distribution
✓ Sponsor GP Catch-Up
✓ Residual Carried-Interest Participation
✓ Separately Tracked GP Co-Investment Economics
✓ Quarterly Distribution Reconciliation
Editable preferred return, GP investment share, carry rate and catch-up terms support transparent comparison of investor outcomes.
INVESTOR RETURNS displays LP called capital, distributions, hypothetical NAV interests, annualized net LP IRR, DPI, RVPI and TVPI.
NAV distributions remain hypothetical until realized.
The simplified waterfall is not a substitute for a negotiated limited partnership agreement and does not implement investor-specific side letters, multiple classes, deal-level carry, GP escrow or clawbacks.
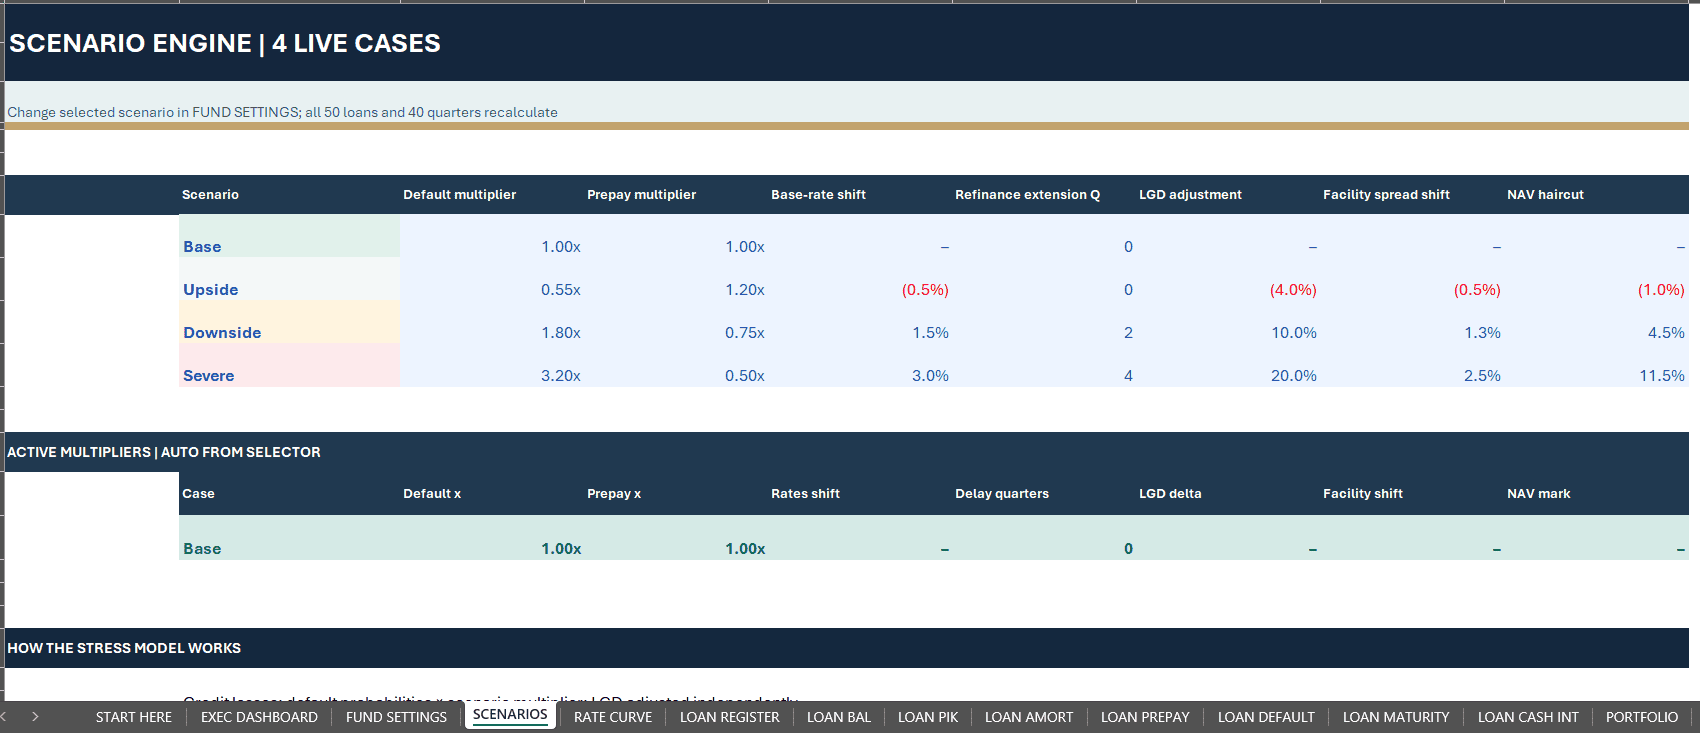
🔄 5. FOUR INTEGRATED SCENARIOS & CREDIT STRESS TESTING
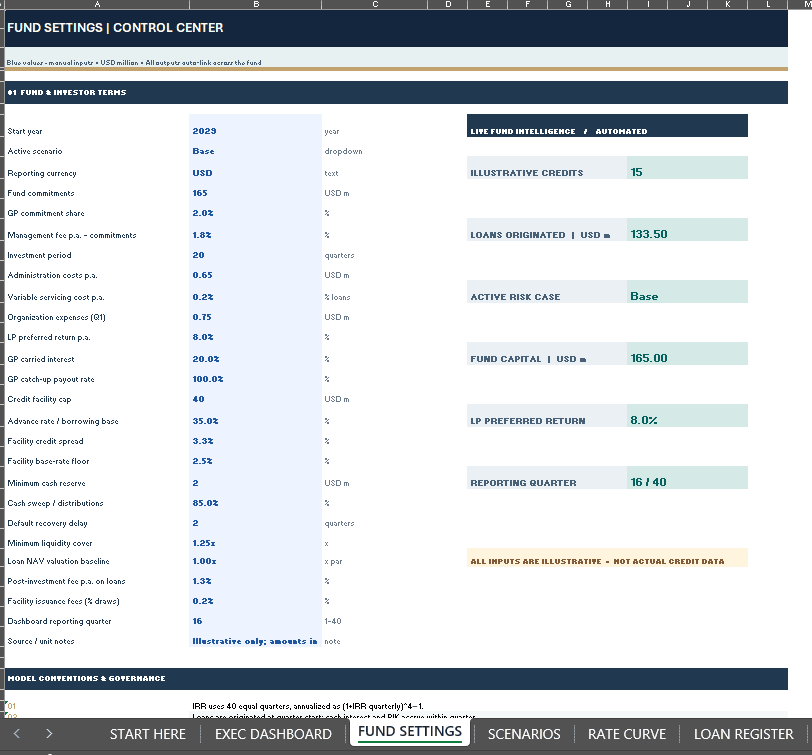
Select BASE, UPSIDE, DOWNSIDE or SEVERE in FUND SETTINGS.
Integrated scenario assumptions affect expected default intensity, prepayments, benchmark interest, maturity extensions, loss severity, facility financing spread and NAV marks.
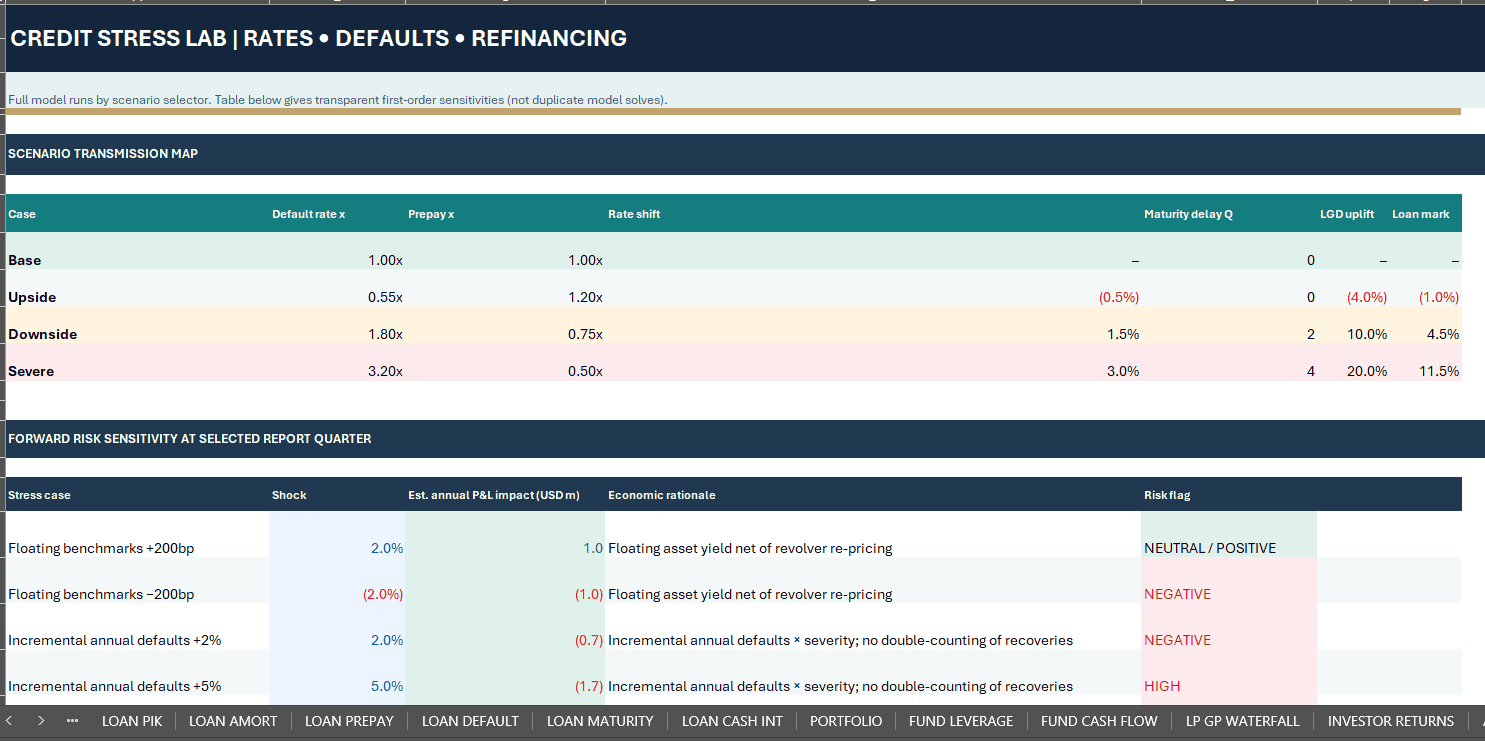
The STRESS TESTS sheet provides additional first-order estimates for:
✓ Floating Reference Rate Changes
✓ Incremental Defaults
✓ Refinancing Delays
✓ Facility Margin Increases
✓ Loss-Given-Default Shocks
The main scenario selector recalculates the connected model.
Standalone stress calculations are directional sensitivities, not independent full-fund simulations.
✅ 6. MODEL CHECKS & FINANCIAL CONTROLS
Forty quarterly status checks support review of:
✓ Principal Roll-Forwards
✓ Fund Cash Reconciliation
✓ Revolving Credit Continuity
✓ LP/GP Distribution Conservation
✓ Capital Commitment Ceilings
✓ Facility Commitment and Borrowing-Base Limits
✓ NAV Attribution
✓ Negative Credit Balances
✓ Distribution Constraints
✓ Loan Origination Input Validity
The supplied fictional Base case passes the programmed quarterly numerical controls. Liquidity warnings must still be examined independently.
Example: the Base case’s selected Q16 liquidity coverage is approximately 0.56x versus a 1.25x policy threshold; it also has no drawable facility headroom at that reporting date.
These are important underwriting warnings, not spreadsheet errors.
📦 7. WHAT YOU RECEIVE
FILE 1 — PRIVATE DEBT & CREDIT FUND FINANCIAL MODEL (.XLSX)
✓ 23 Connected Worksheets
✓ 10-Year / 40-Quarter Model
✓ 50 Prepared Loan Positions
✓ 15 Fictional Demonstration Loans
✓ Seven Credit Calculation Schedules
✓ Fixed and Floating Credit Pricing
✓ Fund Revolving Credit and Cash Flows
✓ LP / GP Whole-Fund Waterfall
✓ NAV and Investor Performance Analysis
✓ Four Selectable Credit Scenarios
✓ Directional Stress Test Worksheet
✓ 10-Year Annual Report
✓ Eight Native Dashboard Charts
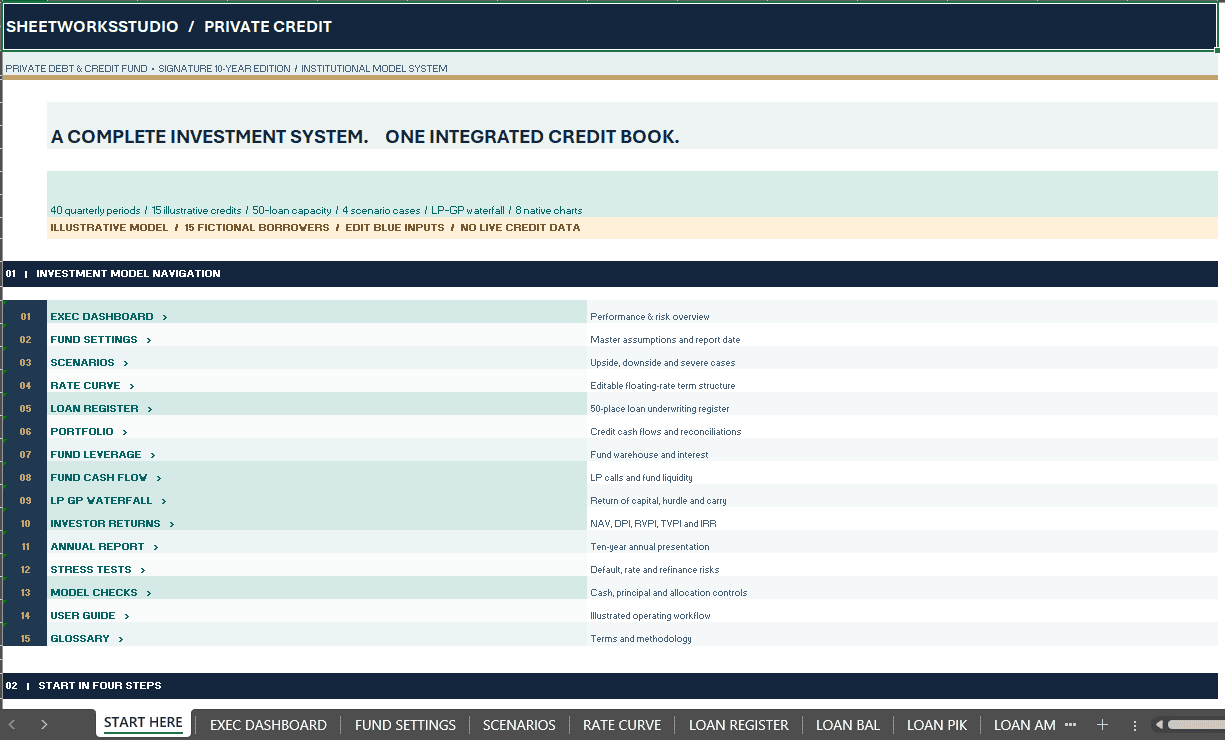
✓ Model Checks, User Guide and Glossary
FILE 2 — COMPLETE HOW-TO-USE HANDBOOK (.PDF)
✓ 33 English-Language Pages
✓ Clickable Table of Contents
✓ Workbook Setup and Input References
✓ Loan Register and Credit Mechanics
✓ Borrowing-Base / Revolver Explanation
✓ Fund Cash Flows and LP/GP Waterfall
✓ NAV, IRR and Investor Metrics
✓ Scenario and Stress Workflows
✓ Practical Examples and Troubleshooting
✓ Model Limitations and Conventions
Both purchased files are included in one digital ZIP download.
The full guide may be provided separately as a free documentation reference; the free guide does not include the paid functional Excel model.
🧭 8. HOW TO USE
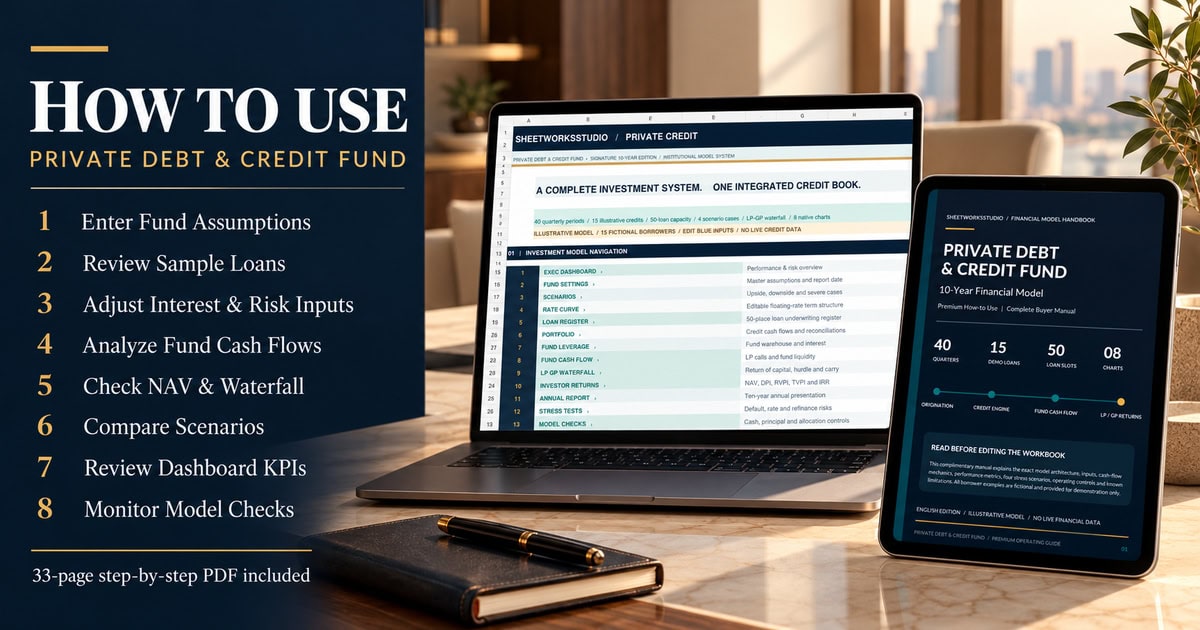
STEP 1 — Save a working copy and read START HERE.
STEP 2 — Set fund commitments, start year, fee assumptions, credit terms, minimum liquidity and partnership waterfall terms.
STEP 3 — Replace the 15 fictional loans or fill prepared additional loan slots.
STEP 4 — Review the reference-rate curve and select the relevant scenario.
STEP 5 — Analyze quarterly loan balances, credit cash flows, debt financing, fund cash and the LP/GP waterfall.
STEP 6 — Review reporting metrics, all model checks and financial liquidity warnings before using outputs.
👥 9. WHO IS THIS MODEL FOR?
Private credit analysts, direct-lending teams, credit investment managers, private debt fund sponsors, investment committees, fund-finance consultants, portfolio analysts, advanced finance students and professionals evaluating simplified private lending fund structures.
⚙ 10. TECHNICAL SPECIFICATIONS
Forecast: 10 years / 40 quarters
Worksheets: 23
Loan capacity: 50 prepared slots
Illustrative loans: 15
Operating scenarios: Base / Upside / Downside / Severe
Native Excel charts: 8
Financial controls: Quarterly reconciliations
Example start year: 2029
Units: Selected currency in millions
Formats: XLSX + PDF
Guide: 33 English pages
Preferred application: Microsoft Excel Desktop
Macros / VBA: Not required
External APIs / data connections: Not required
Delivery: Digital download
Google Sheets import has not been independently validated. Currency settings change reporting labels, not monetary FX conversion.
🛡 11. IMPORTANT LIMITATIONS & DISCLAIMER
All loans, borrowers and financial results are fictional illustrative examples.
This model uses quarterly expected-value credit assumptions, simplified NAV estimation, cash interest and funding conventions.
It is not a stochastic default engine or a full statutory IFRS/US-GAAP fund accounting package.
Exact-day accrual, tax schedules, multi-currency conversion and bespoke investor legal terms are outside its scope.
Model checks demonstrate numerical consistency within programmed tests; they do not establish adequate liquidity, suitability, investment performance or lender approval.
Scenario results and fund valuations require independent professional review and project-specific source evidence.
This is an independent, unofficial SheetworksStudio template. It is not affiliated with any financial institution, fund manager, regulator or software provider and does not constitute investment, legal, accounting, tax, regulatory or underwriting advice.
UNDERWRITE LOANS. MONITOR LIQUIDITY. ANALYZE NAV. EXPLAIN INVESTOR RETURNS.
SheetworksStudio | Premium Financial Modeling Templates
Similar ProductsOther customers were also interested in...



 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more

Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more

Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more

 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.