
0 ITEMS

Multifamily Real Estate Development Analyzer (Basic) – Excel Template
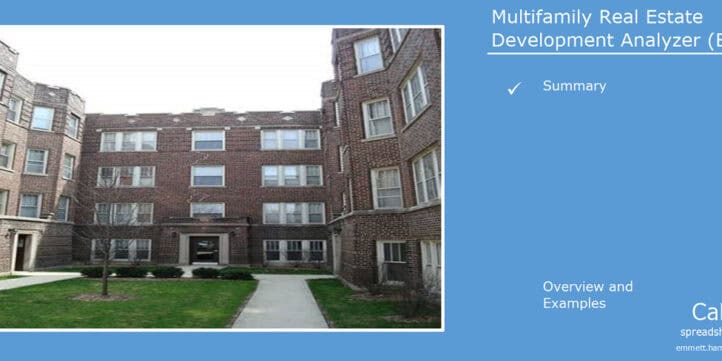
The Multifamily Development Analyzer (Basic Version) provides a high-level, back-of-the-envelope estimate of your multifamily real estate development project’s potential return. It allows you, as an investor or developer, to input key financial assumptions and receive a rough first-pass evaluation of a project’s feasibility.


Overview
The Multifamily Development Analyzer (Basic Version) provides a high-level, back-of-the-envelope estimate of your multifamily real estate development project’s potential return. It allows you, as an investor or developer, to input key financial assumptions and receive a rough first-pass evaluation of a project’s feasibility.
The summary sheet serves as both the input and output view, displaying critical investment metrics without requiring navigation to multiple sheets.
Key Definitions
- Untrended vs. Trended
- “Untrended results provide a conservative estimate of a property’s performance that doesn’t include any anticipated trends in market growth or other factors.
- Trended results do include expectations of market growth and other factors in estimating a property’s performance.”
- Development Yield
- Development Yield (Yield on Cost) is the ratio of Net Operating Income (NOI) to Total Project Cost. It provides a measurement of a project’s performance based solely on the cost of development.
- Development Spread
- Development Spread is the difference between the Development Yield and the Market Cap Rate. It provides an indication of the potential profit of a project.
- IRR (Internal Rate of Return)
- IRR represents the compounded annual rate of growth of capital for a project. It accounts for cash inflows and outflows and the time value of money.
- Equity Multiple
- Equity Multiple is a return metric that shows how much investors earned on the capital invested. It is calculated as the sum of cash distributions received from a project, divided by the total cash invested (Equity Required).
- Gross Sales Price
- The Gross Sales Price is the expected value of the project asset at the time of exit from the investment. It is derived from the trended annual NOI at the time of exit, divided by the expected cap rate at the time of exit.
- Economic Occupancy
- Economic Occupancy is the ratio of actual income generated by a property compared to its potential income if all units were rented at market rates.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.