
0 ITEMS

Small Business Acquisition Underwriting Model (SBA 7(a)-Style)
Underwrite a small-business acquisition the way a lender will: SBA 7(a)-style deal structure, a 10-year monthly amortization schedule, DSCR, and buyer and lender returns. Fully unlocked, 1,751 live formulas, worked example tied out to the dollar.
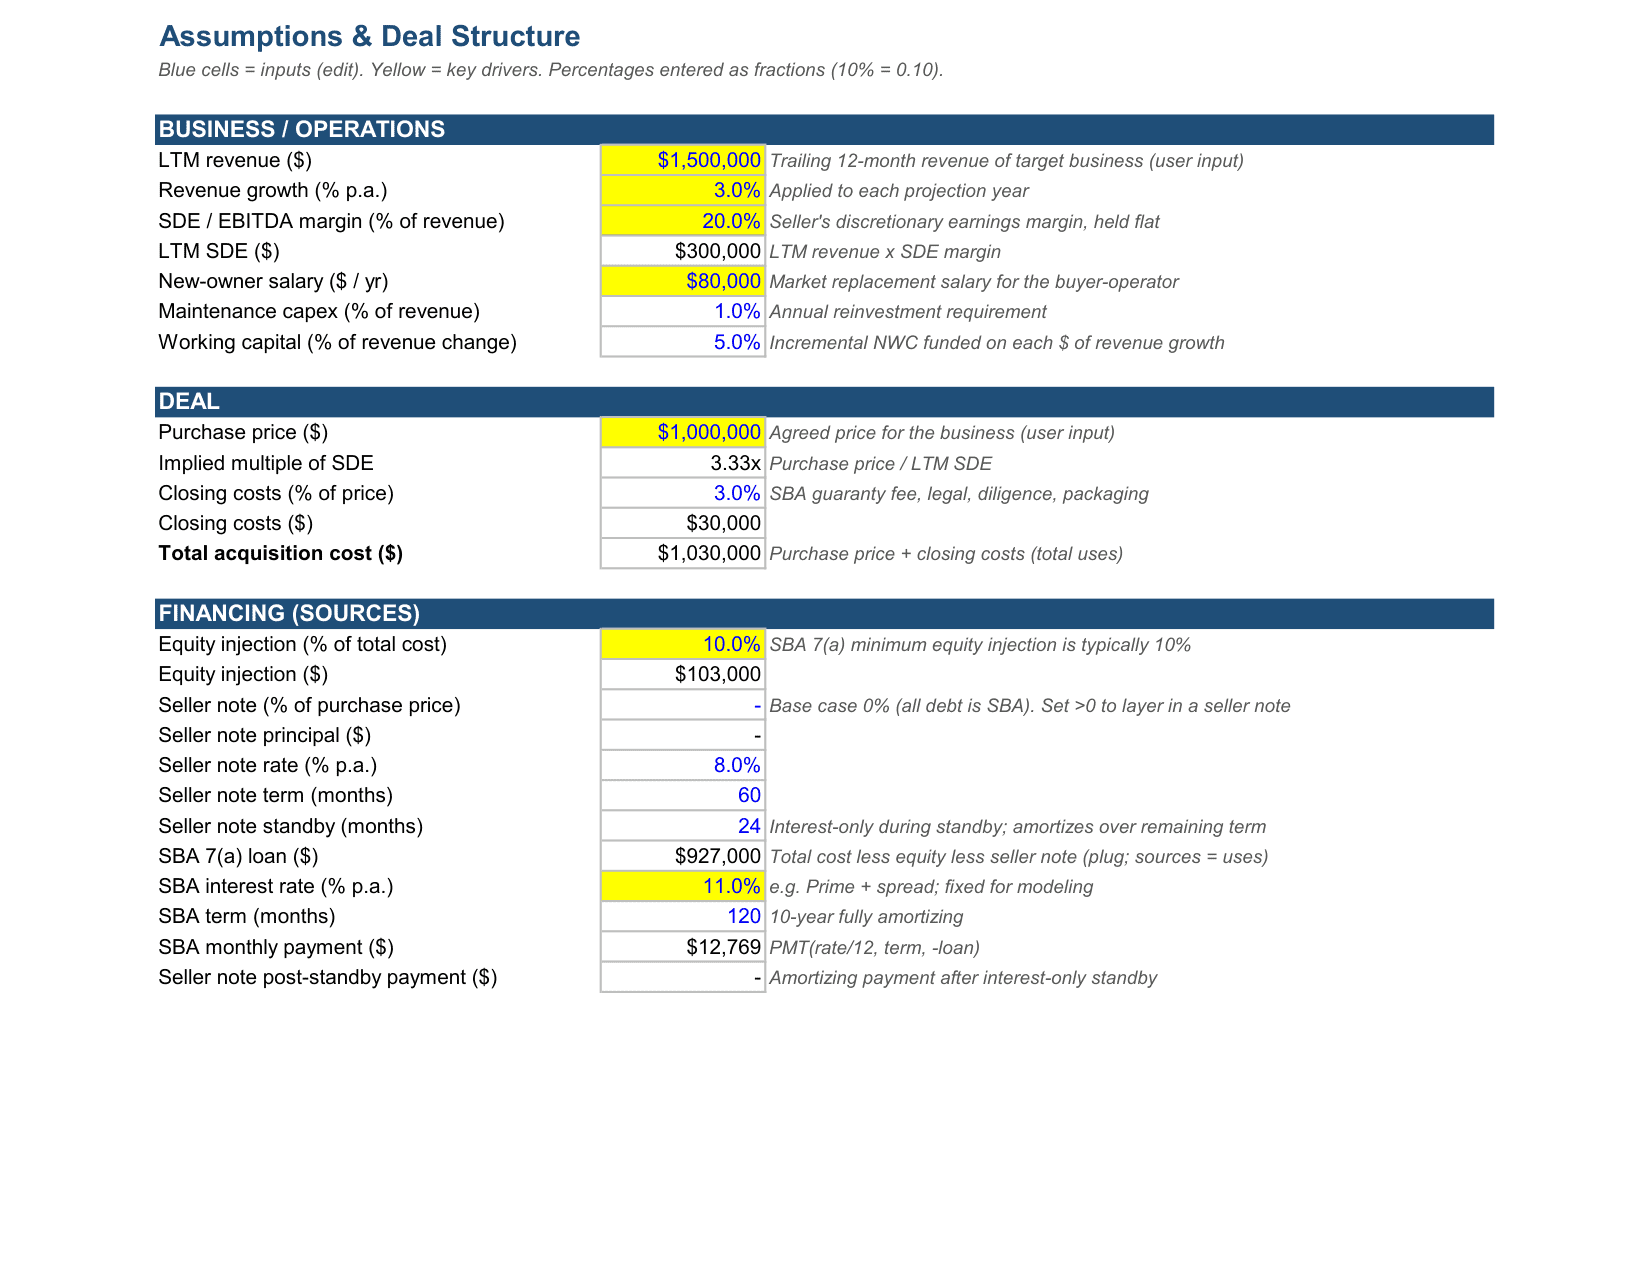
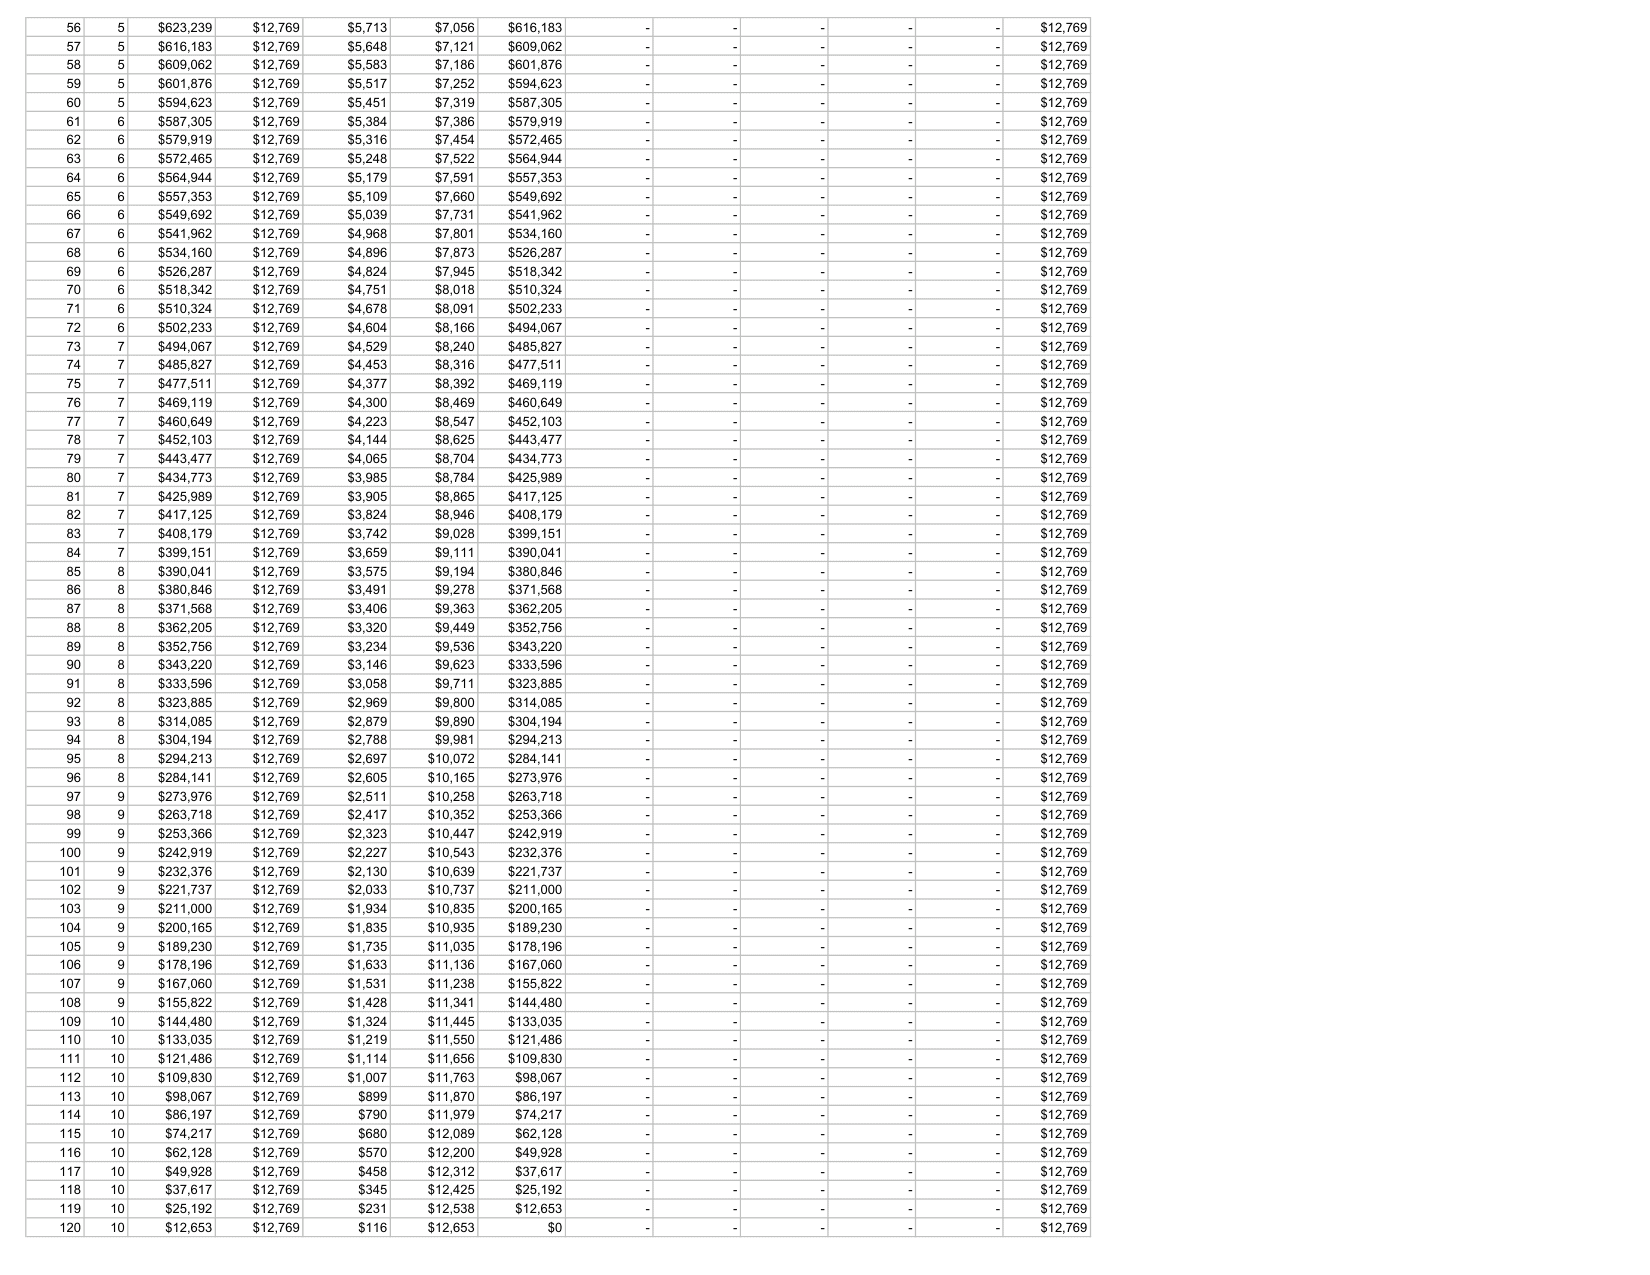
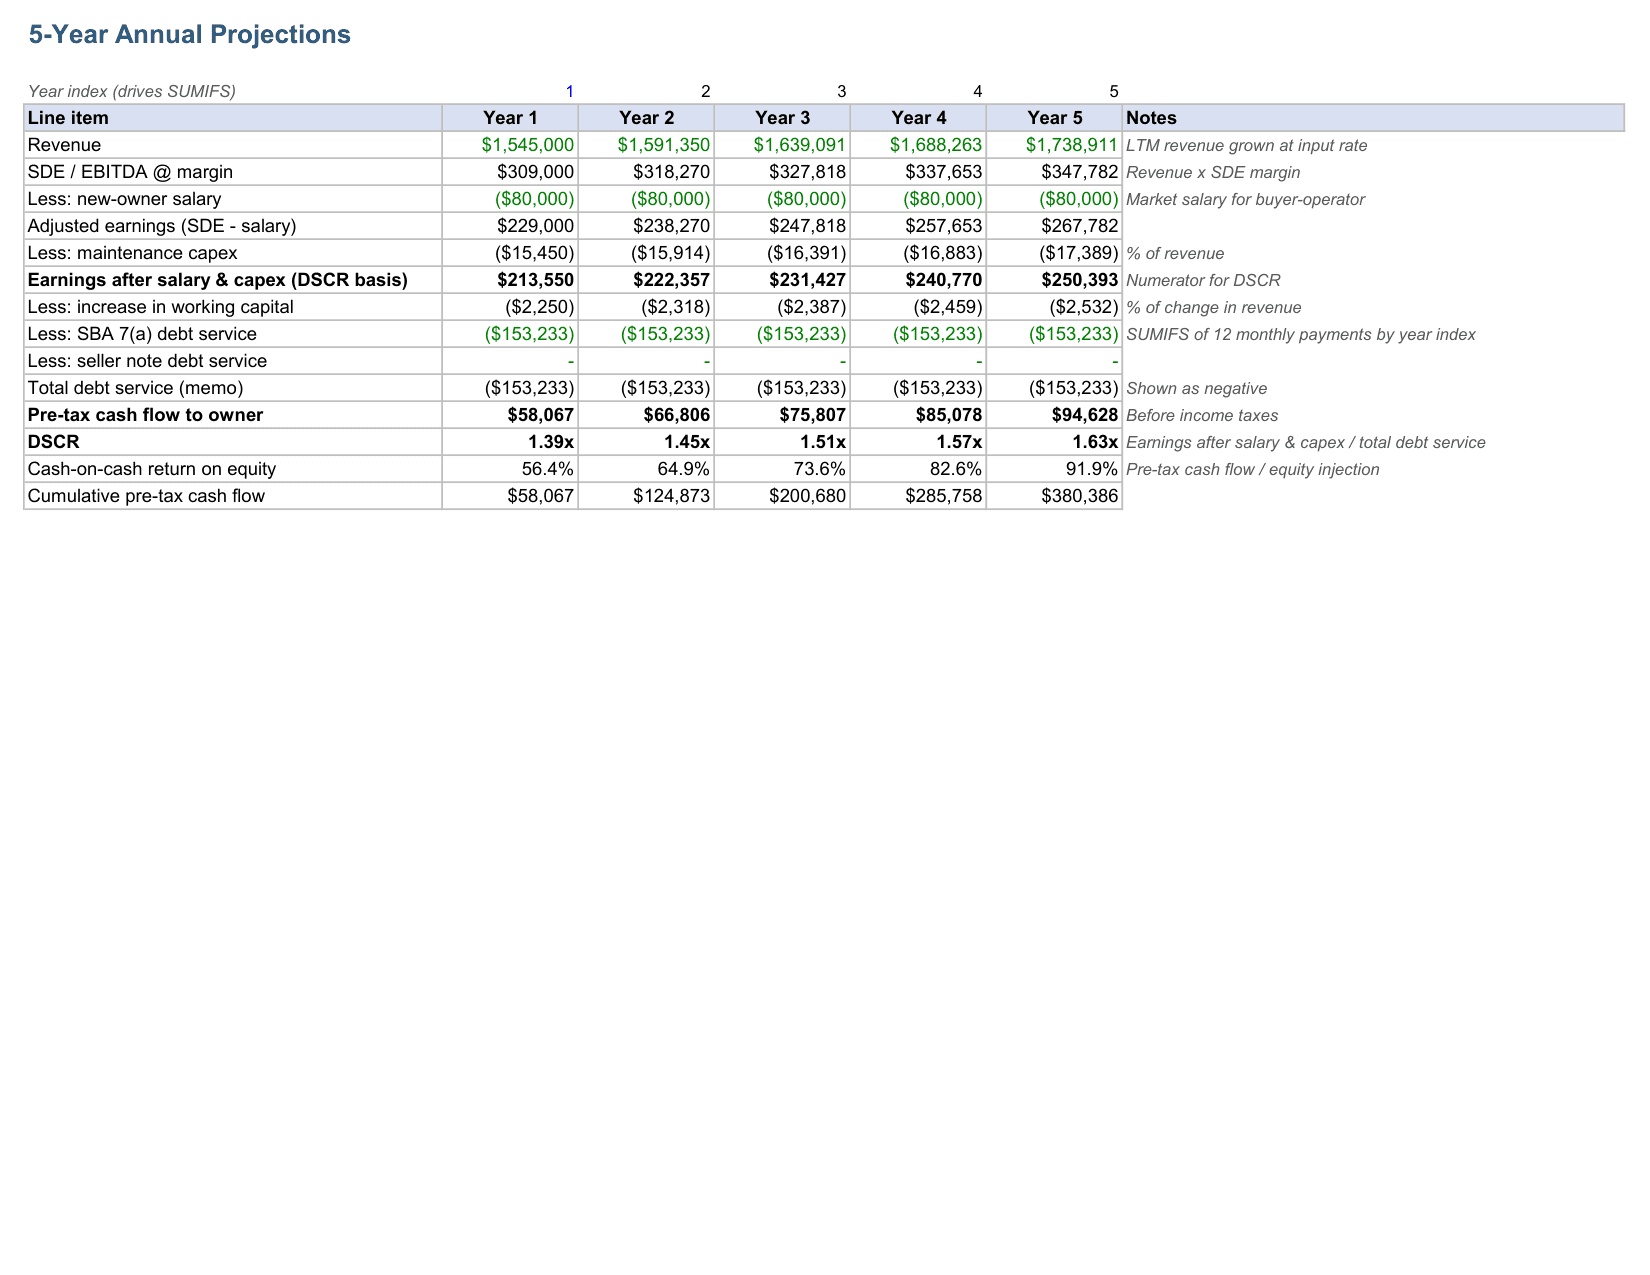

The Small Business Acquisition Underwriting Model lets you underwrite a search-fund or owner-operator acquisition the way the lender financing it will. Enter the target’s last-twelve-months revenue, SDE margin, growth and a market new-owner salary, then set the deal: purchase price, closing costs, equity injection, an optional seller note, and the SBA 7(a) rate and term. Everything downstream calculates itself.
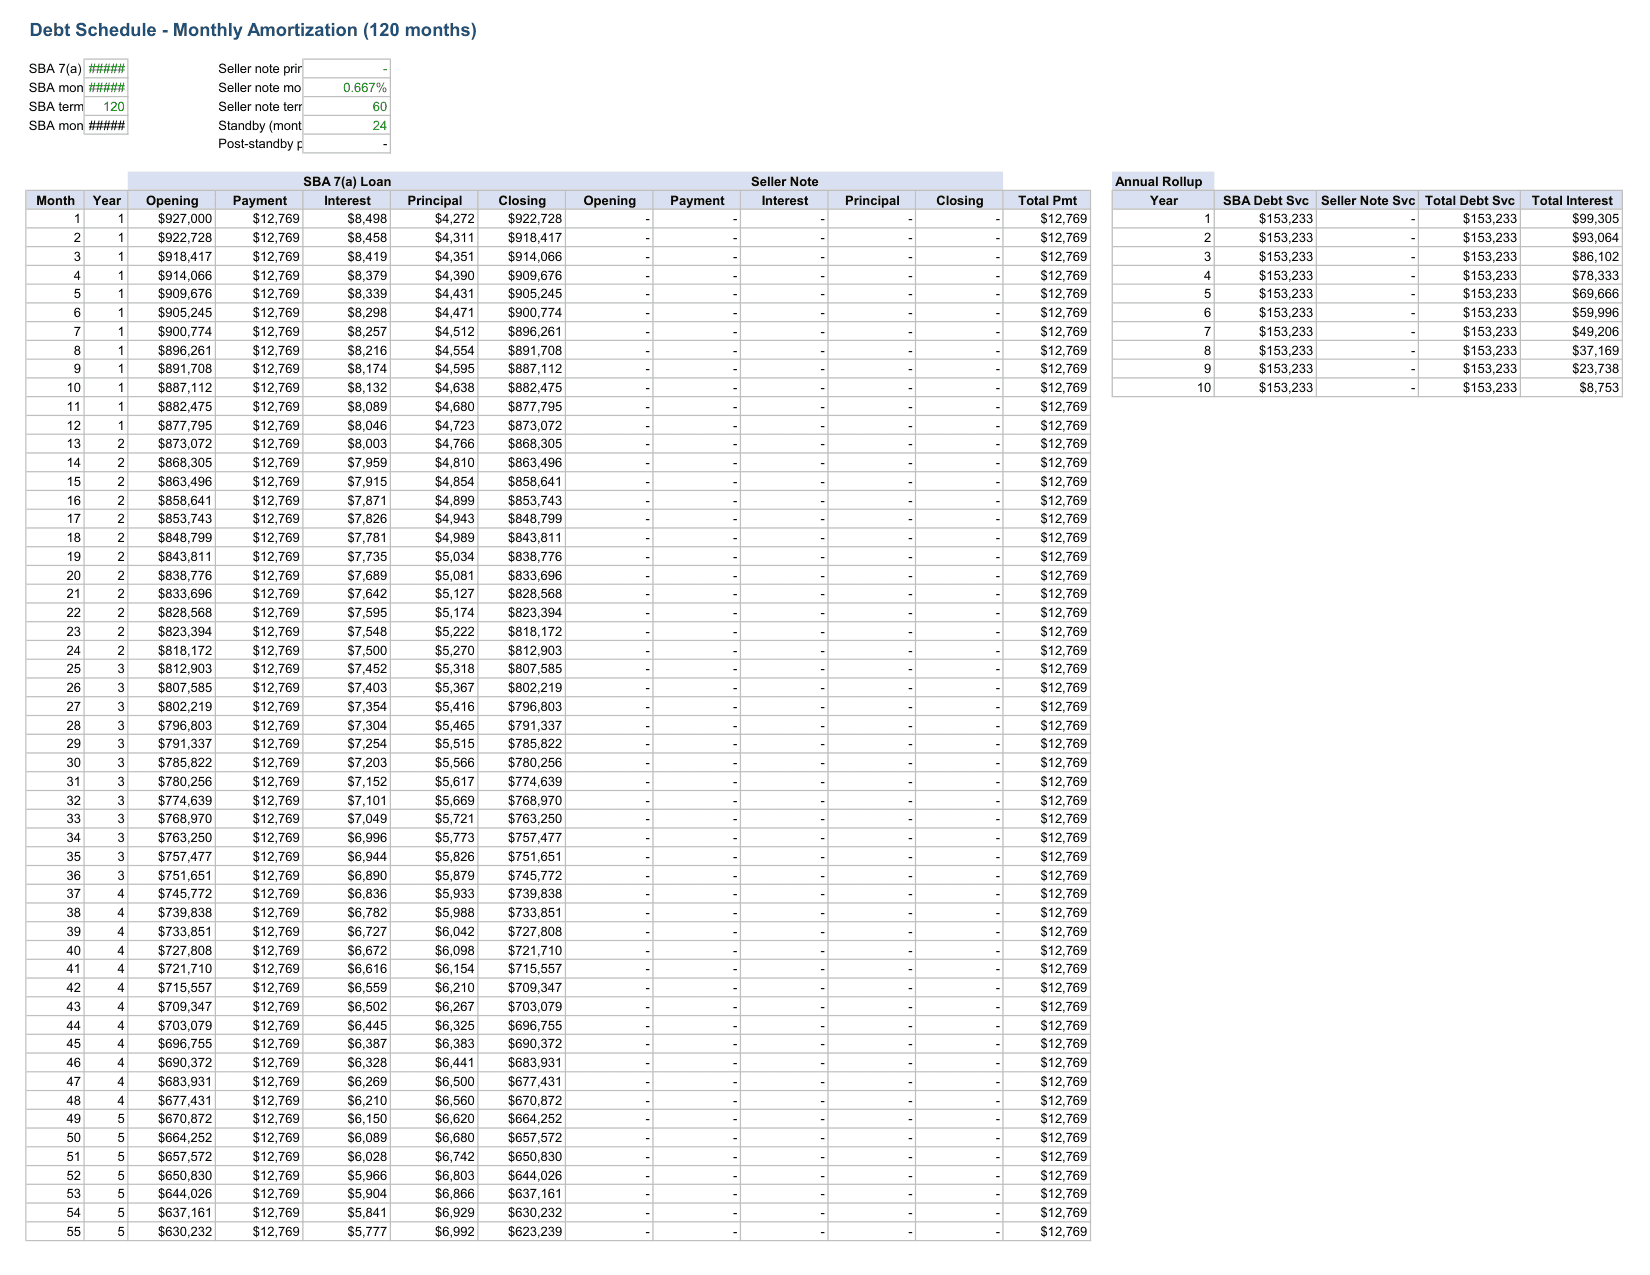
What you get is a complete, transparent underwriting workbook. A full 10-year monthly amortization schedule handles the SBA loan and the optional seller note, including an interest-only standby period. Five years of projections flow through to the debt-service coverage ratio (DSCR) the lender uses to decide whether the deal funds at all, with a clear PASS or REVIEW flag against a 1.25x threshold. A sources-and-uses block proves the deal balances to the cent, and the Returns sheet summarises both lender metrics (DSCR by year) and buyer metrics (cash-on-cash, equity multiple, IRR).
The main highlights: an SBA-style structure with a seller-note lever; a proper monthly amortization engine rather than an annual approximation; DSCR and returns computed side by side; and a two-way sensitivity grid showing Year-1 DSCR across purchase multiples and interest rates, so you can see how much room the deal has before it breaks.
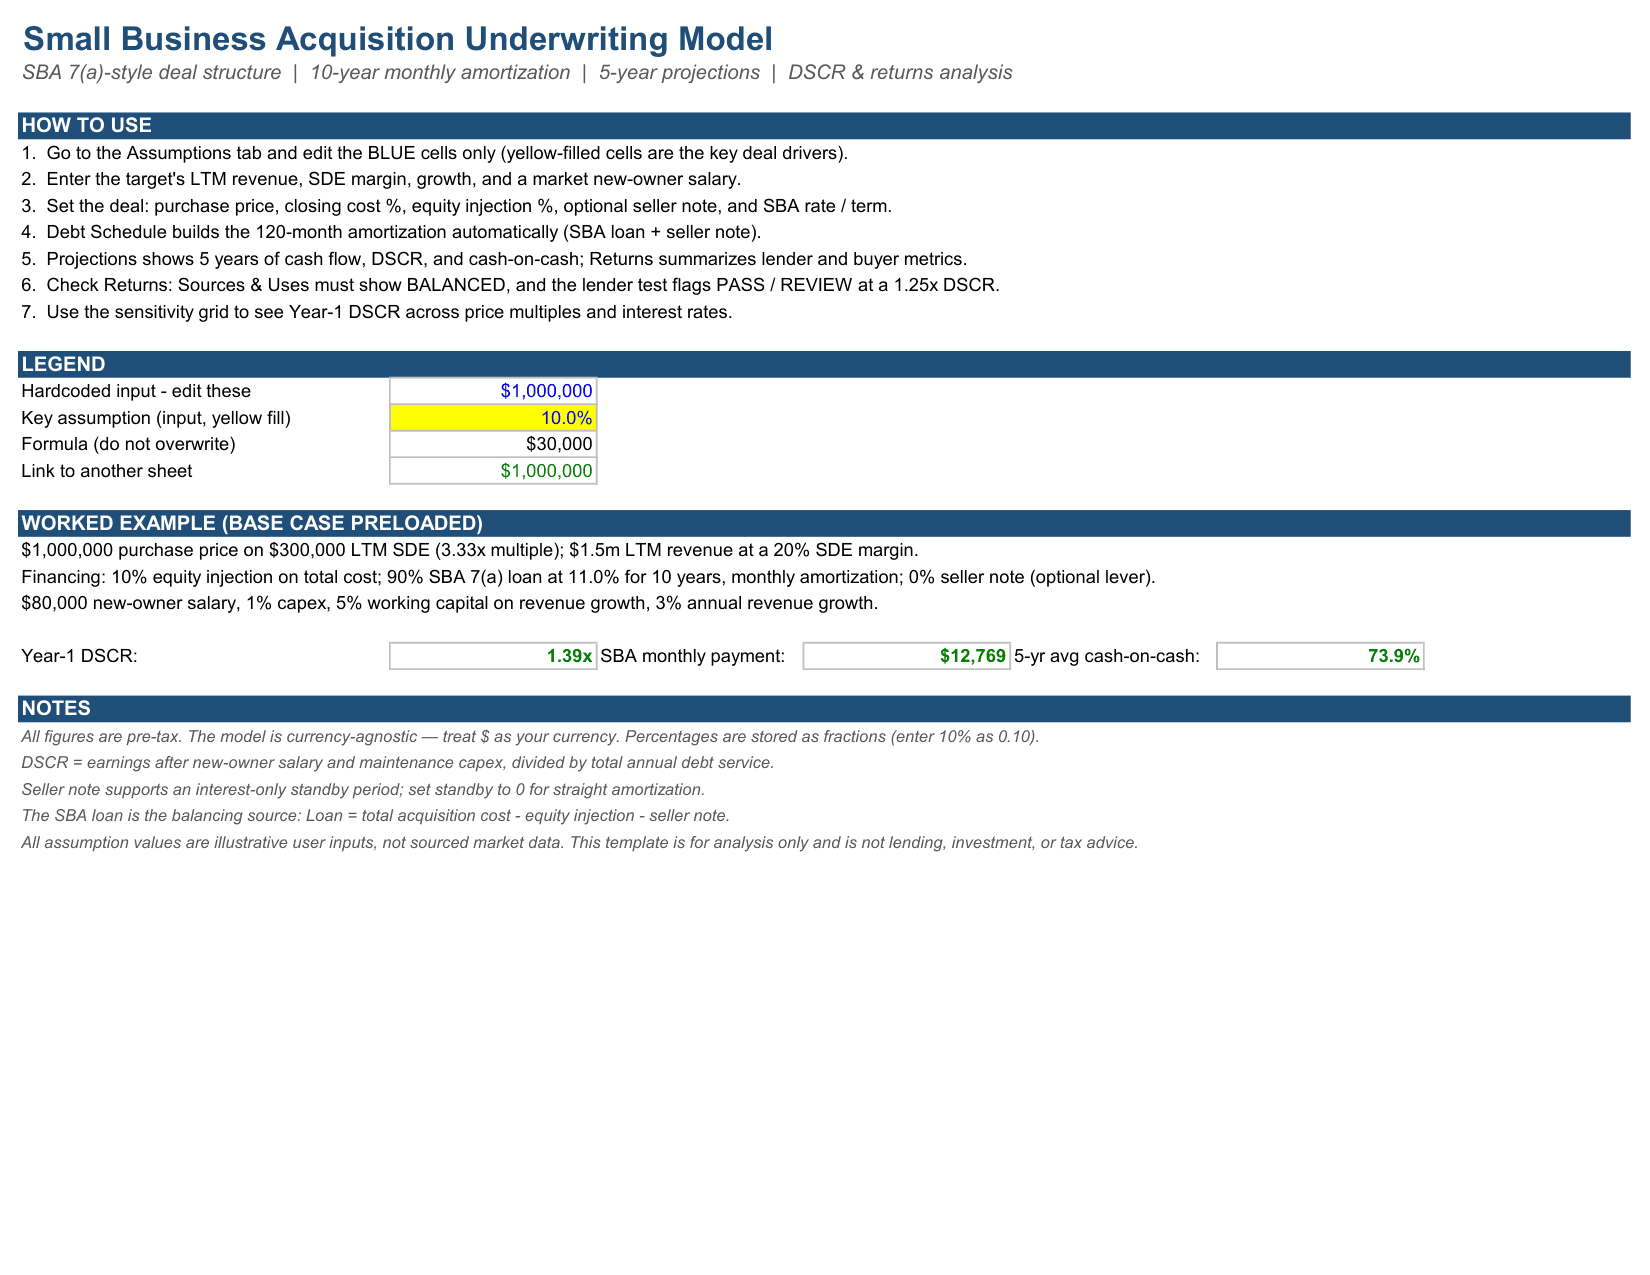
How to work with it: only the blue input cells are yours to change, and the yellow-filled cells are the key deal drivers. Black and green cells are formulas. A realistic worked example is preloaded (a 1.0m purchase on 300k SDE), and the profit ties to the equity cash flow exactly, so you can trace the logic before trusting it.
Why you need it: business acquisitions live or die on debt serviceability, and a locked black-box template will not let you check the number that matters. This one ships fully unlocked with every formula visible, built-in integrity checks, and an honest cover sheet that discloses each assumption. Currency-agnostic. For analysis only, not lending or investment advice.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.