
0 ITEMS

IFRS 18 Transition Kit (Excel + Google Sheets) | 5-Category P&L · Category Mapping Engine · Main Business Activity Matrix · MPM Reconciliations
12-tab Excel and Google Sheets IFRS 18 transition kit: five-category P&L with both required subtotals, IAS 1 to IFRS 18 mapping engine, 20×7 main-business-activity matrix, worked bank statement, 3 MPM reconciliations, 55-point disclosure checklist.
| All Industries, Financial Model, General Excel Financial Models |
| Business Template, Calculator, CFO, Chart, Excel |
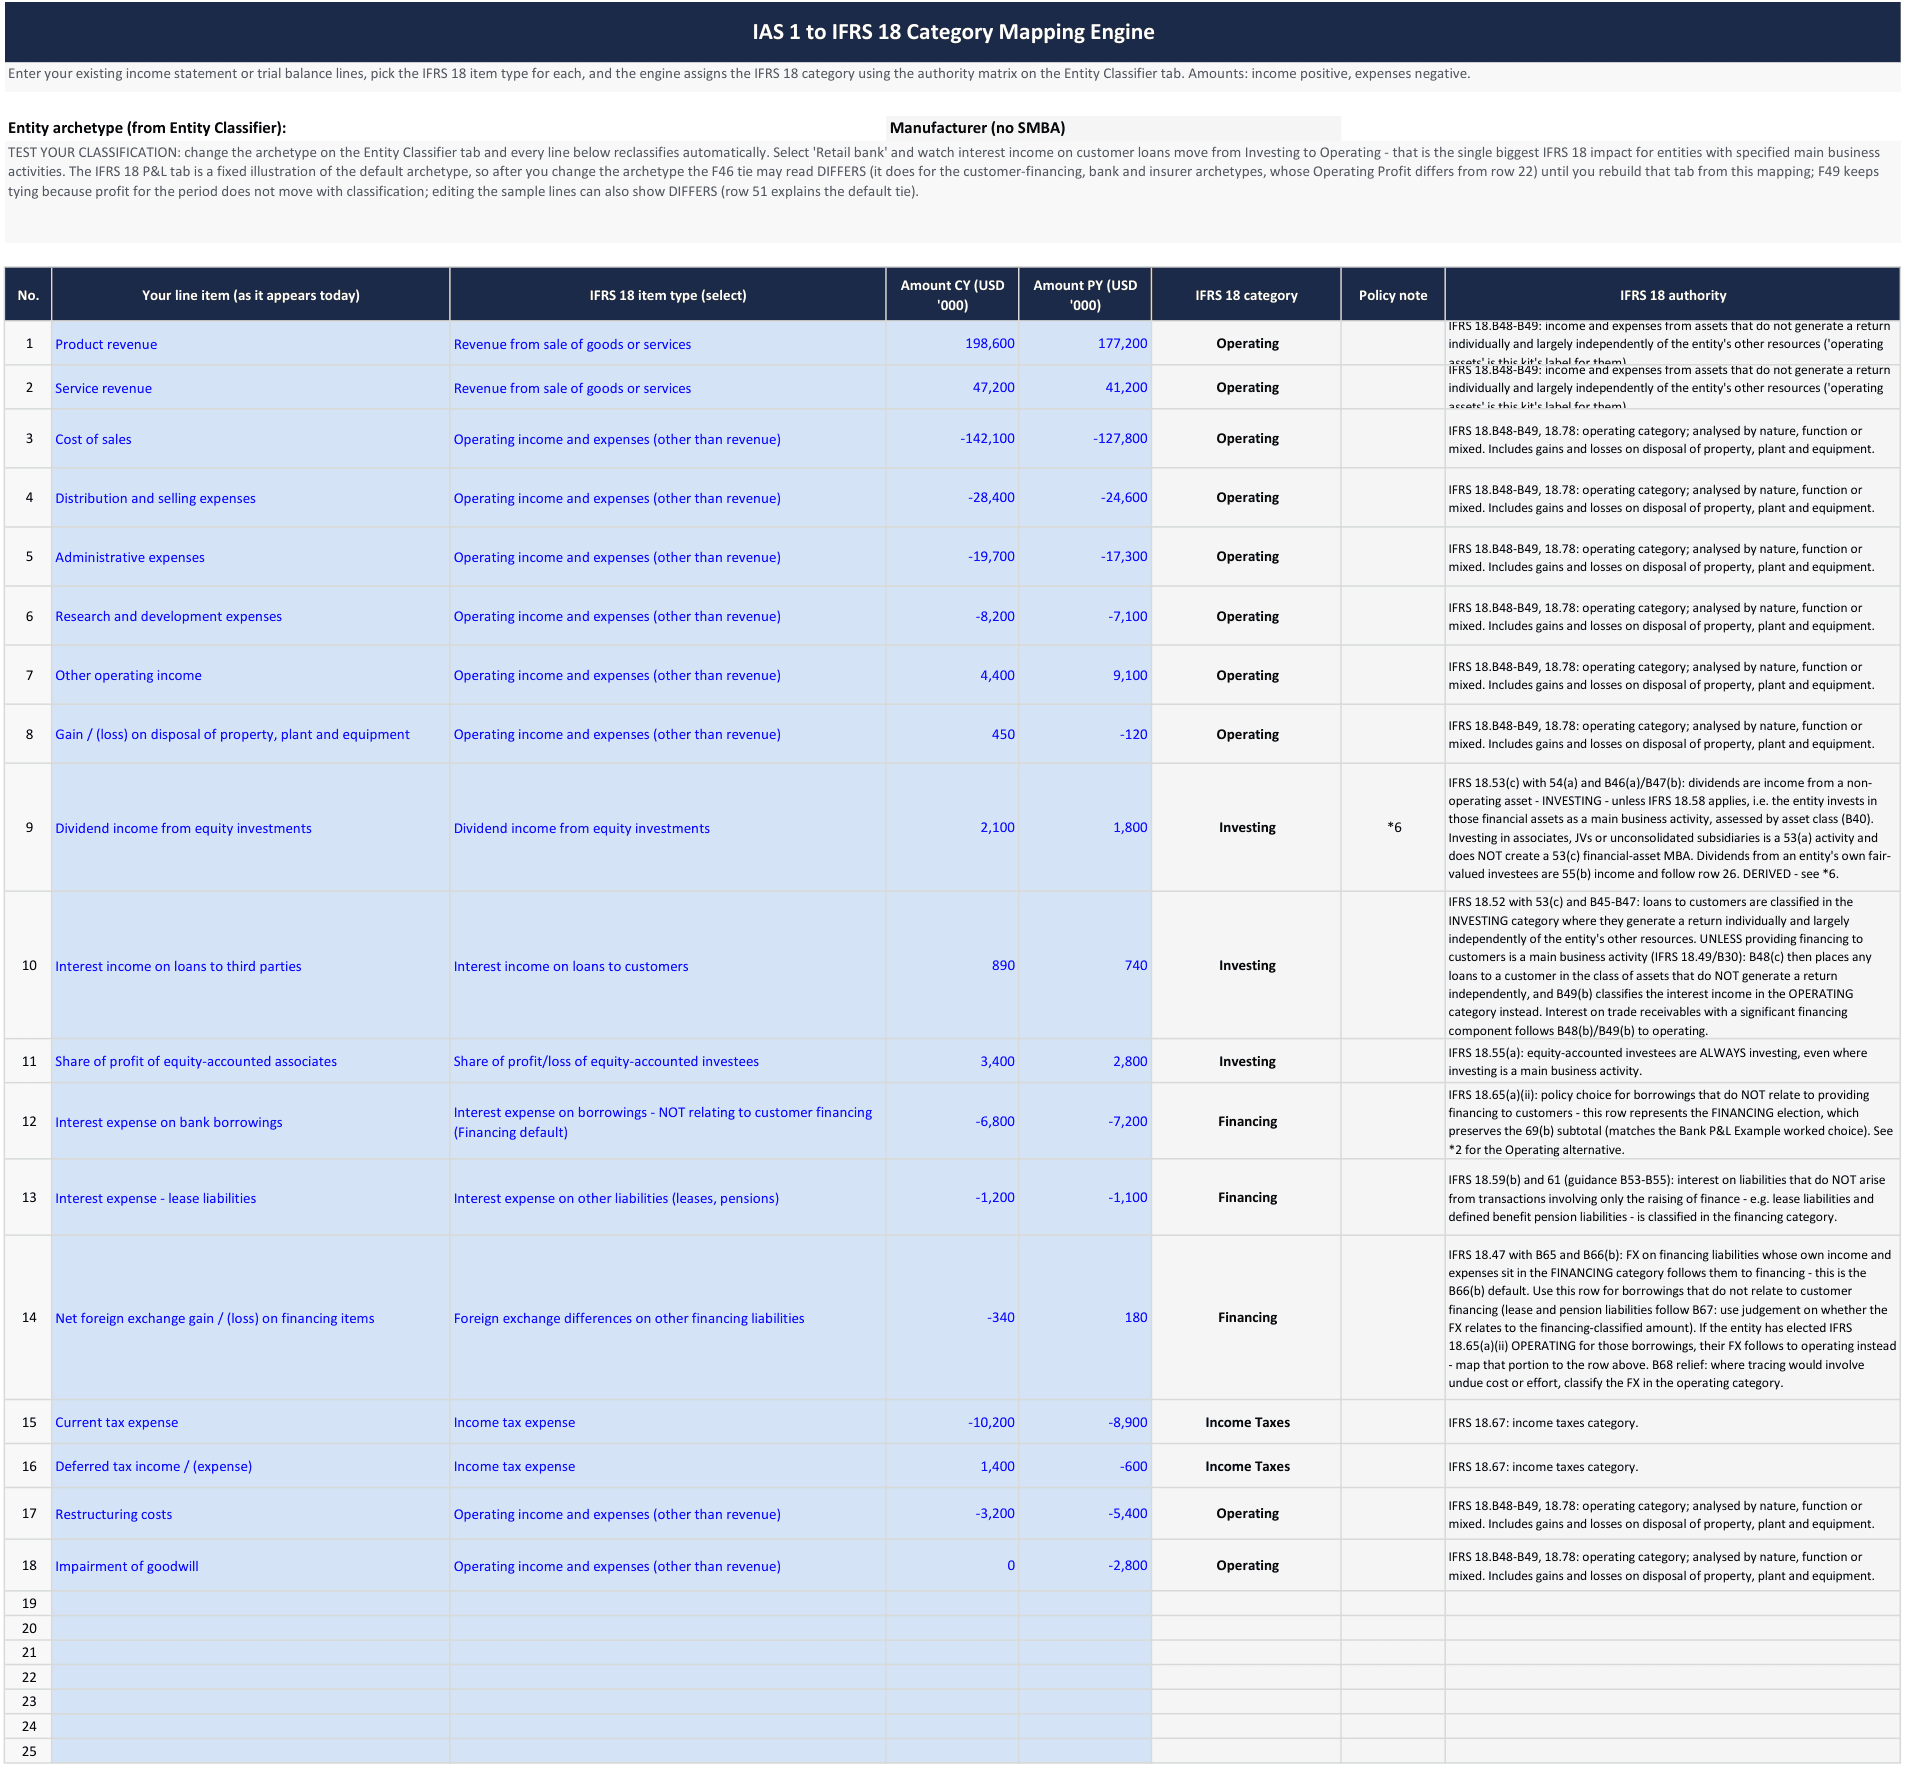
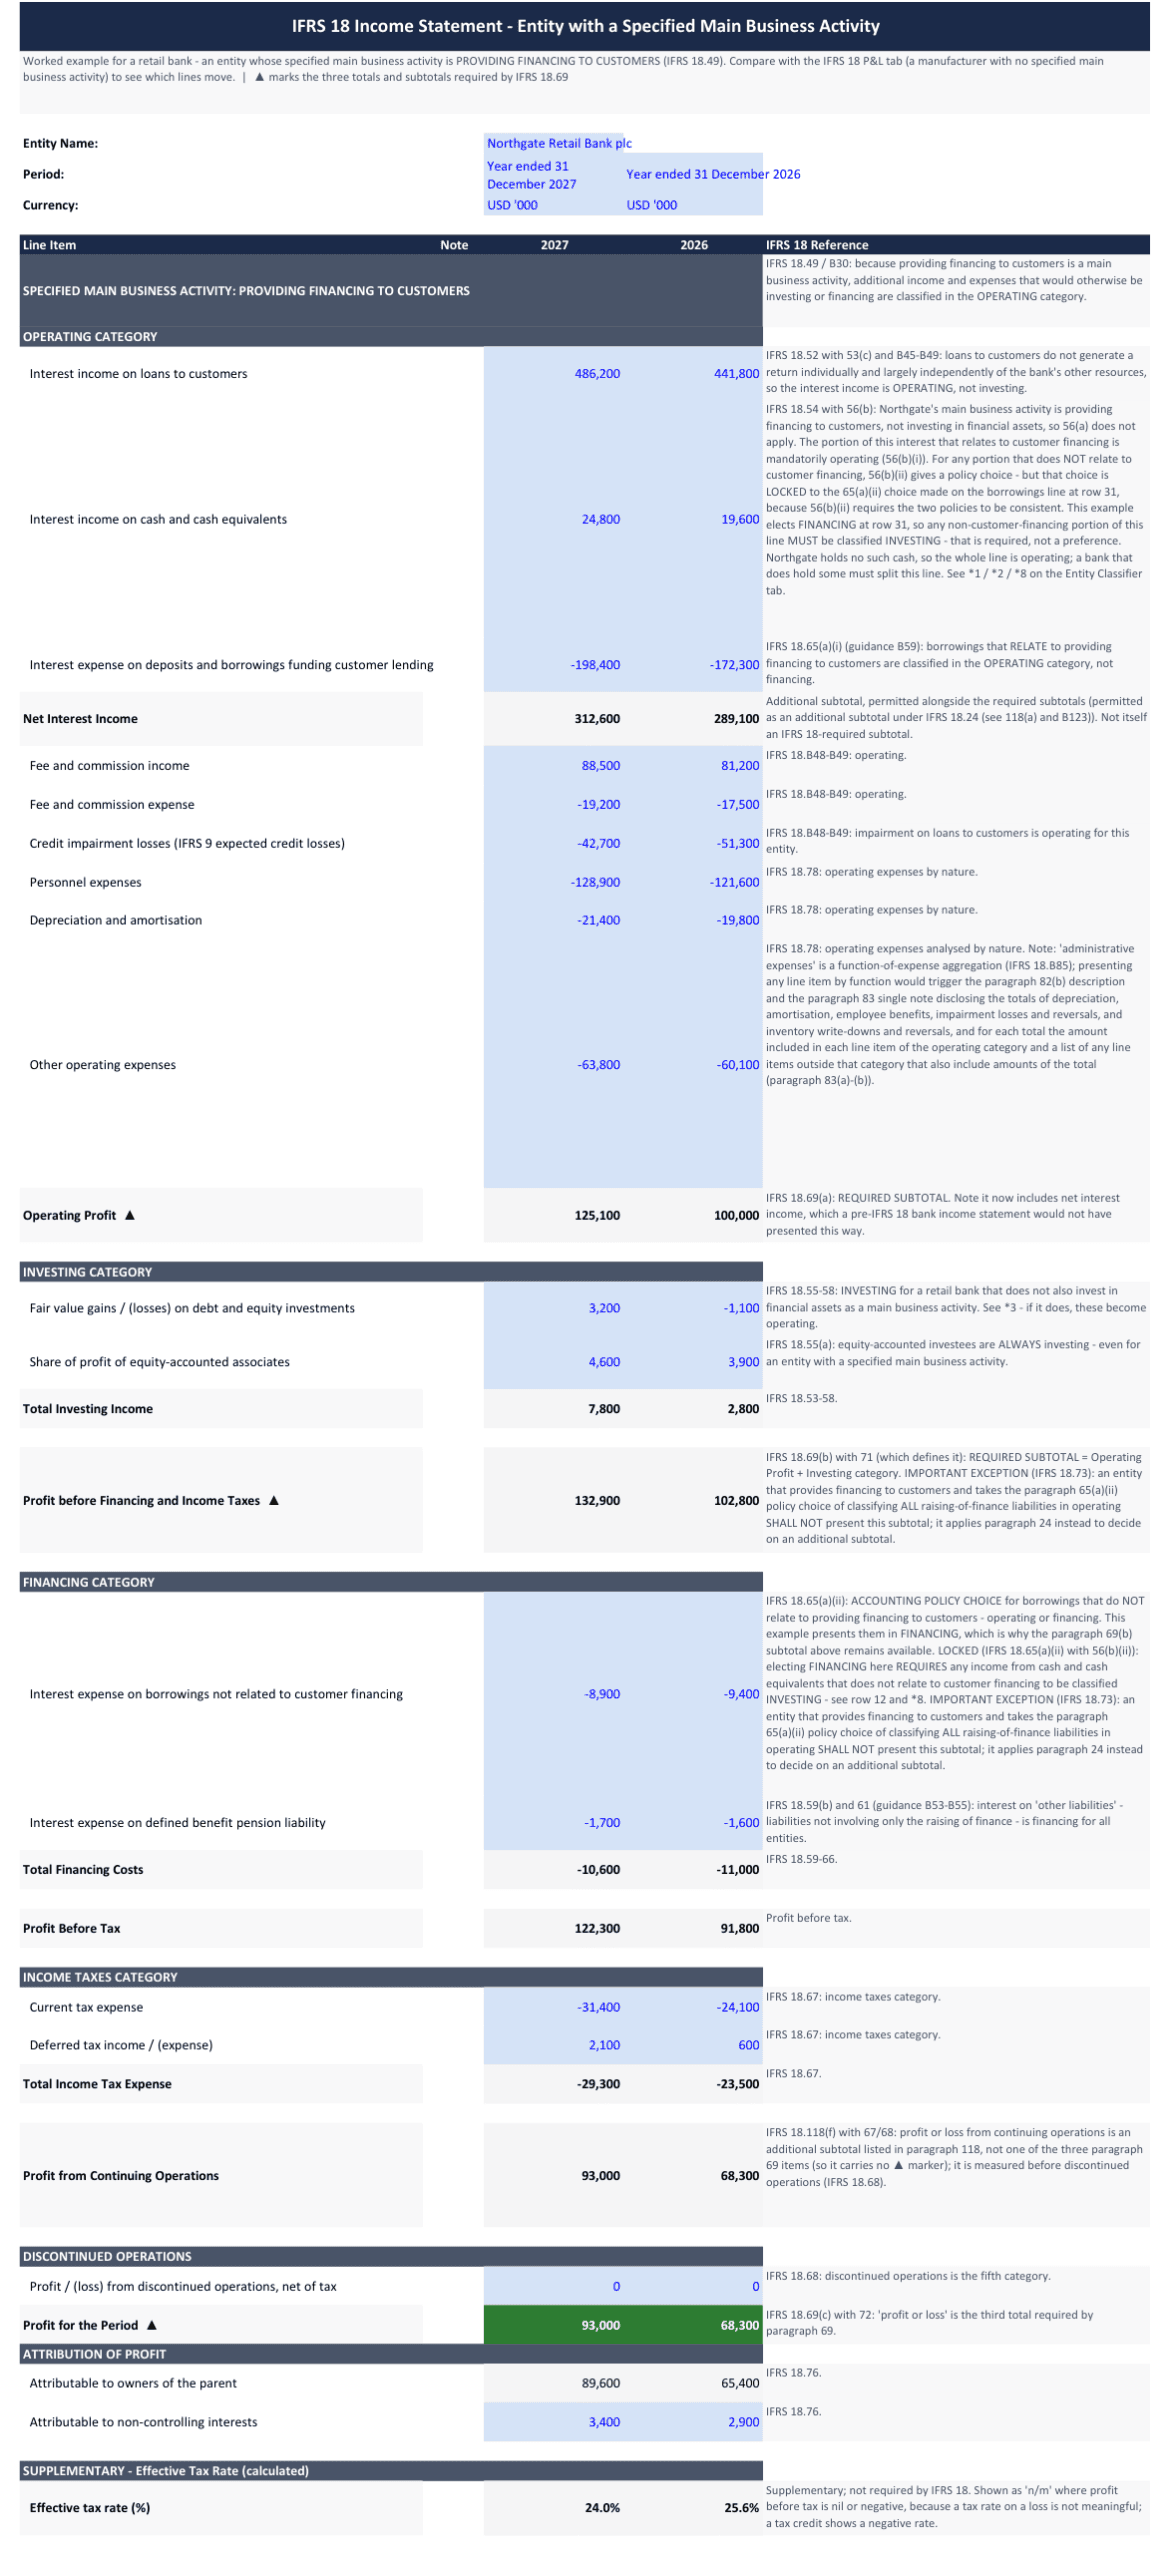
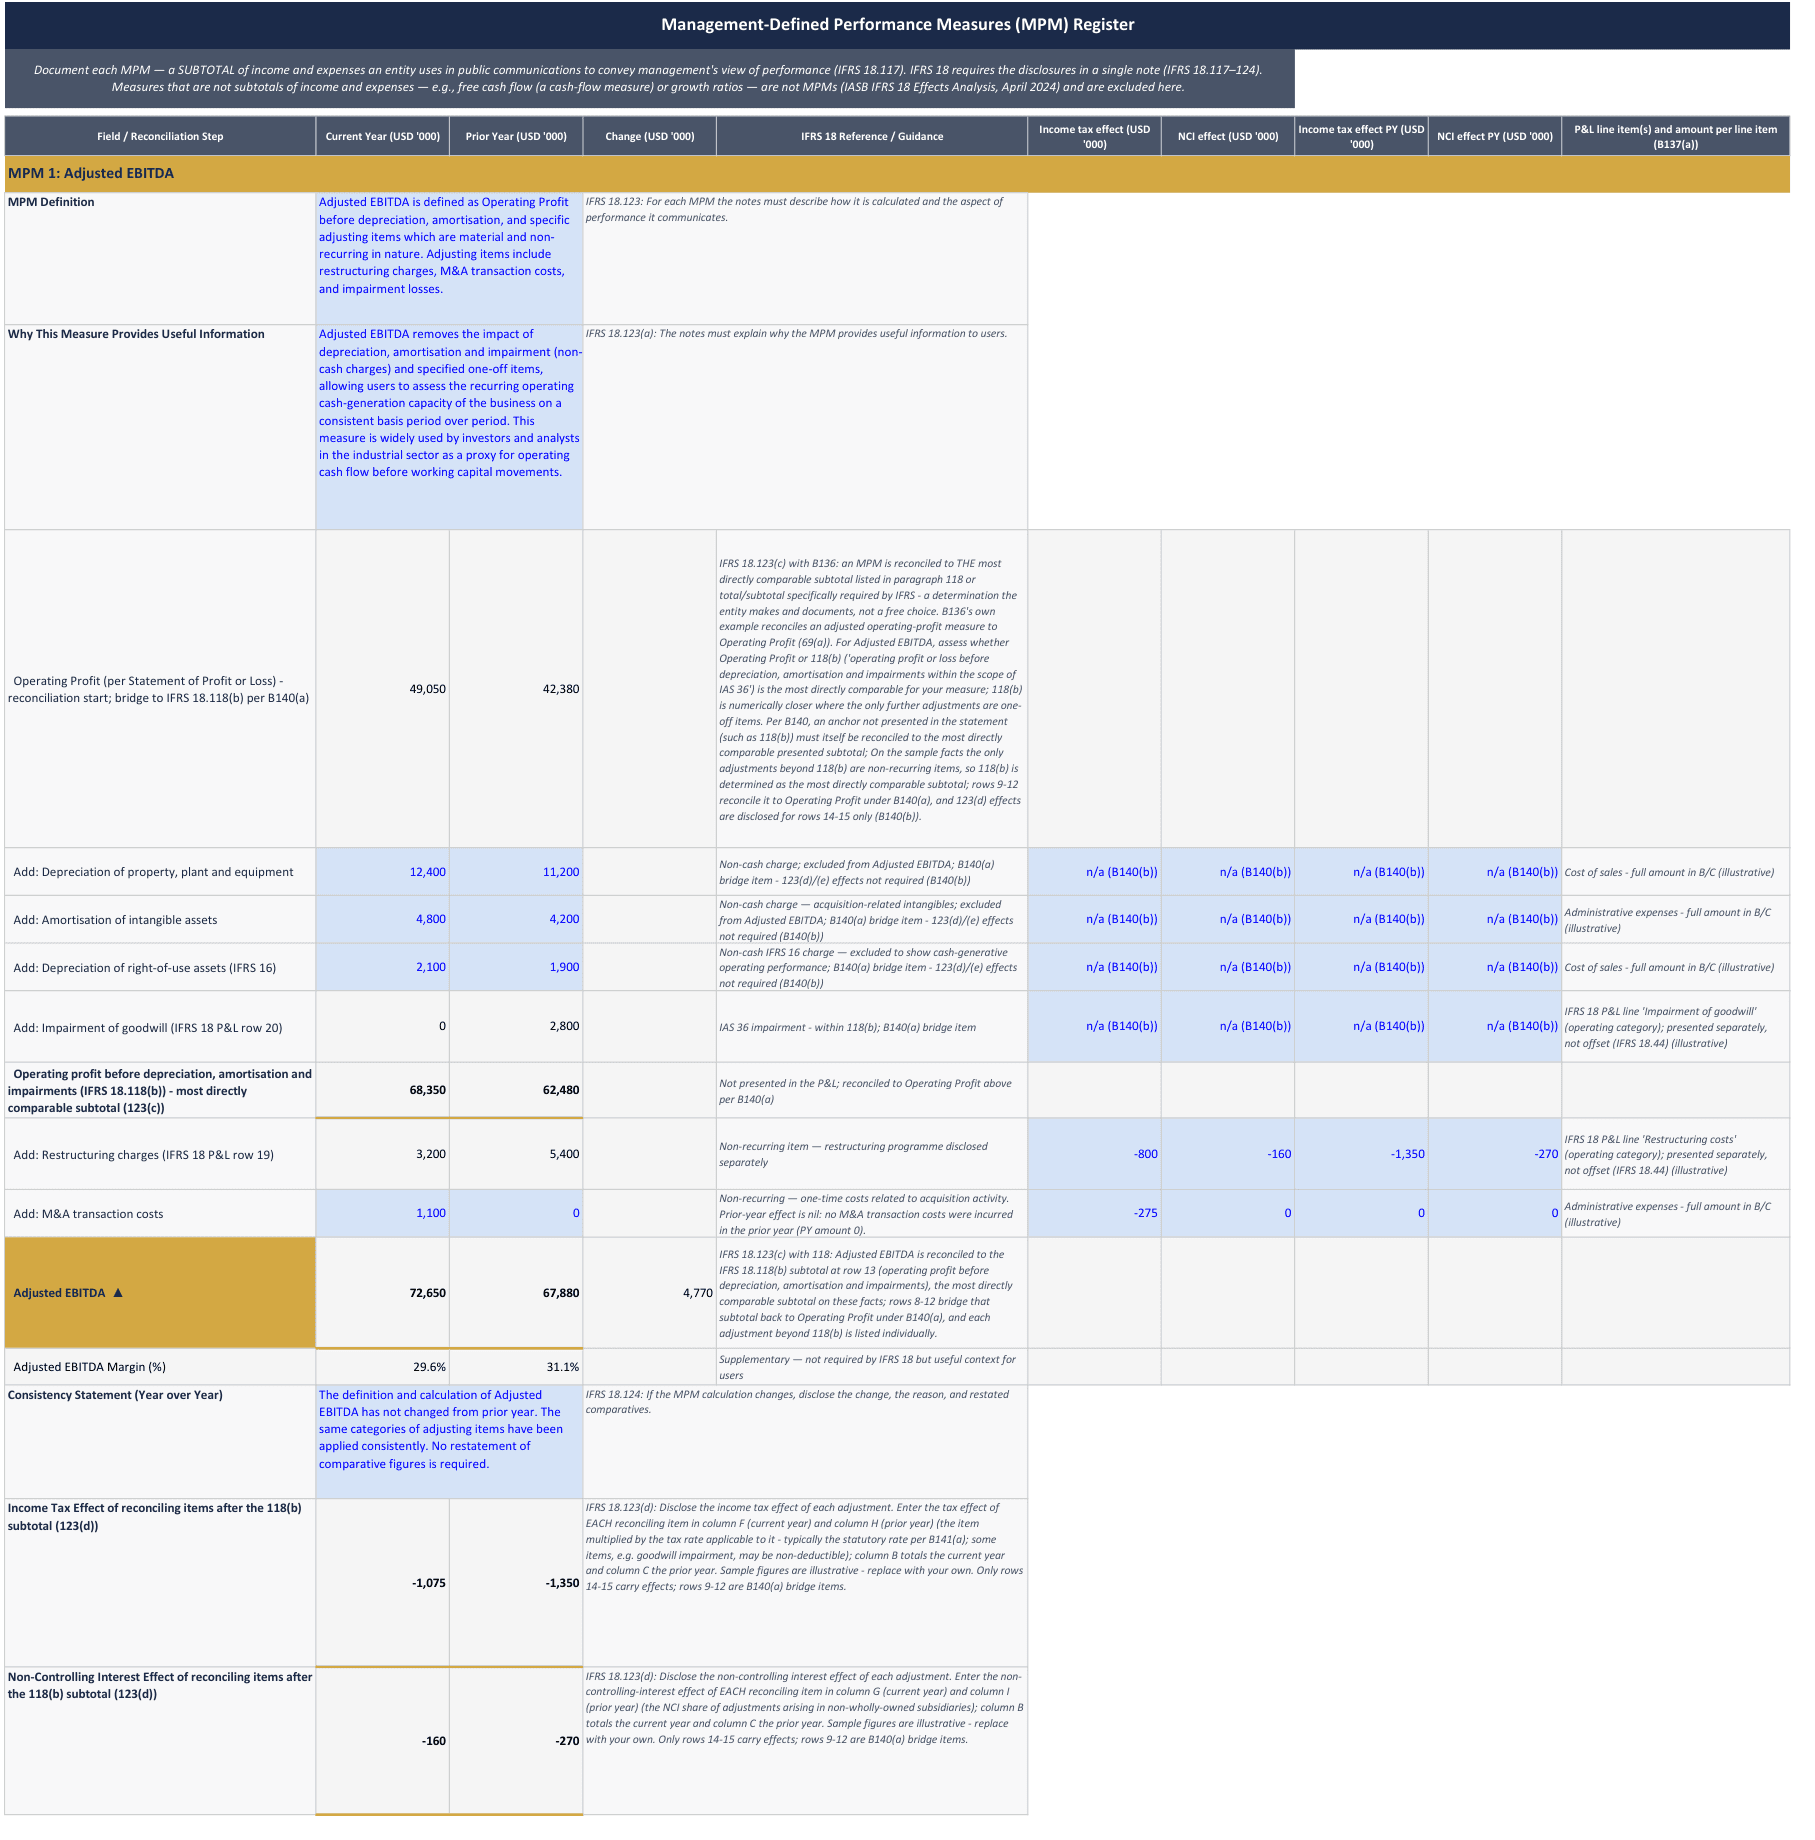
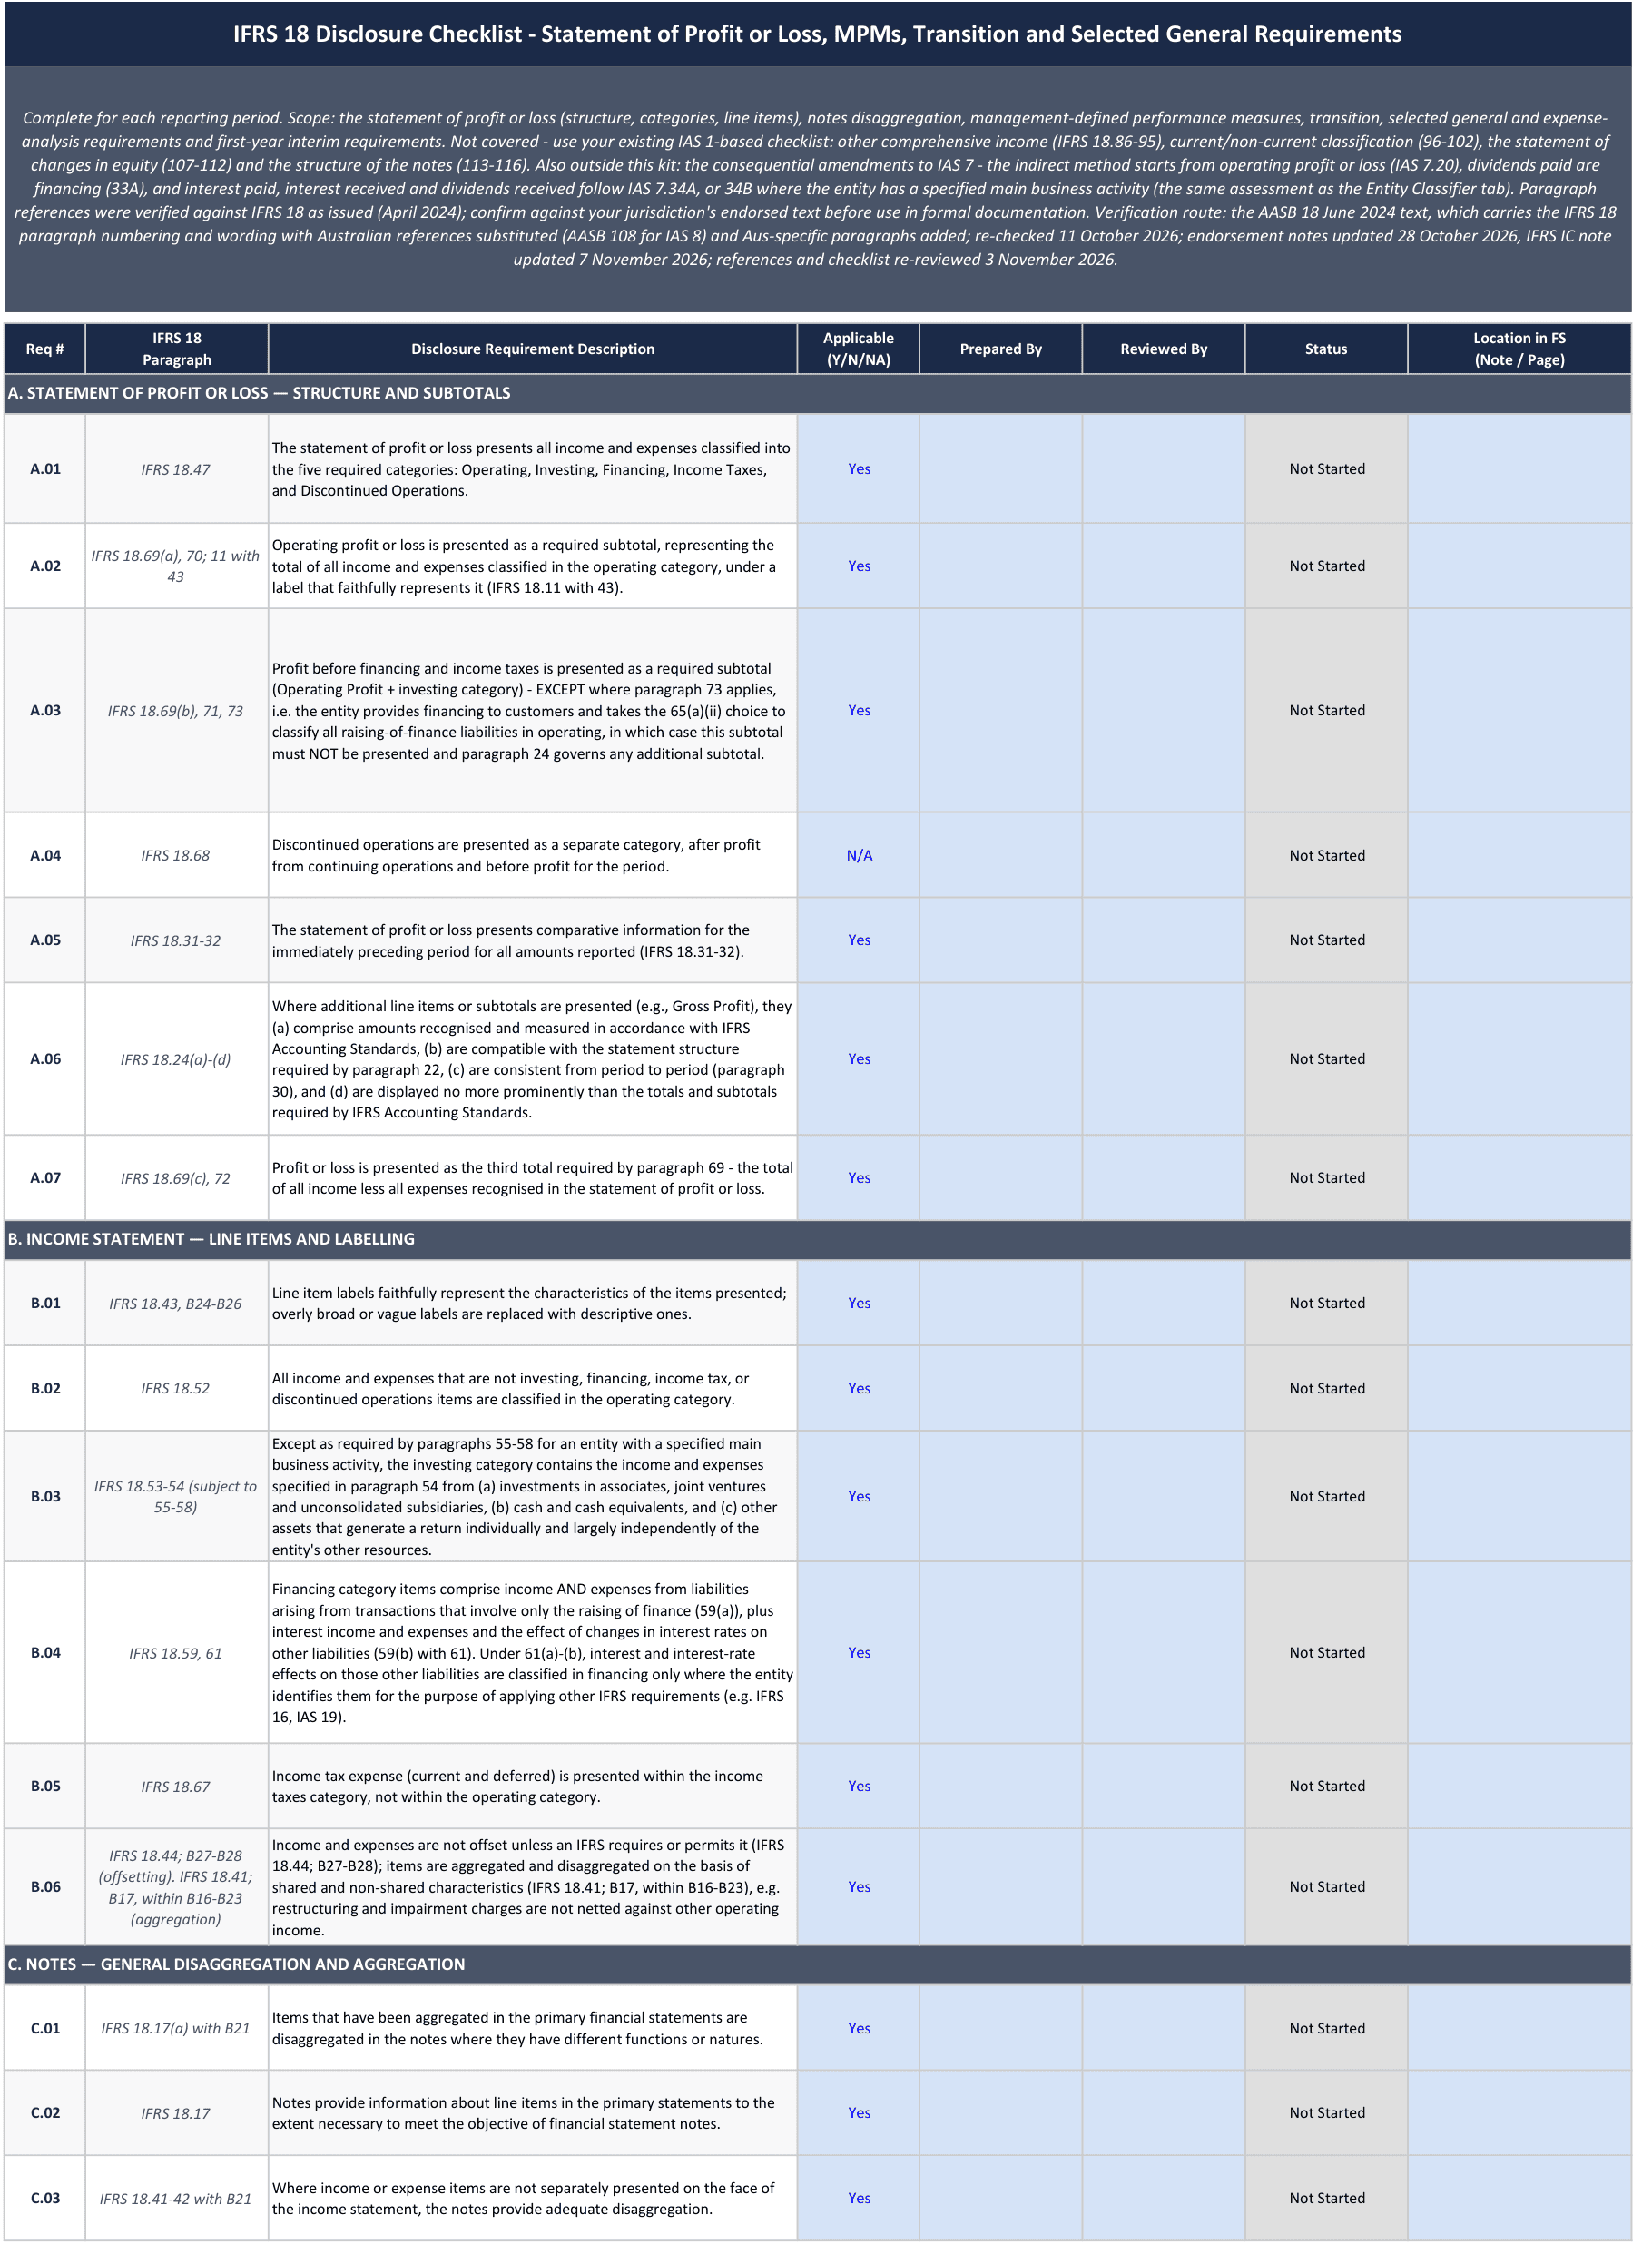
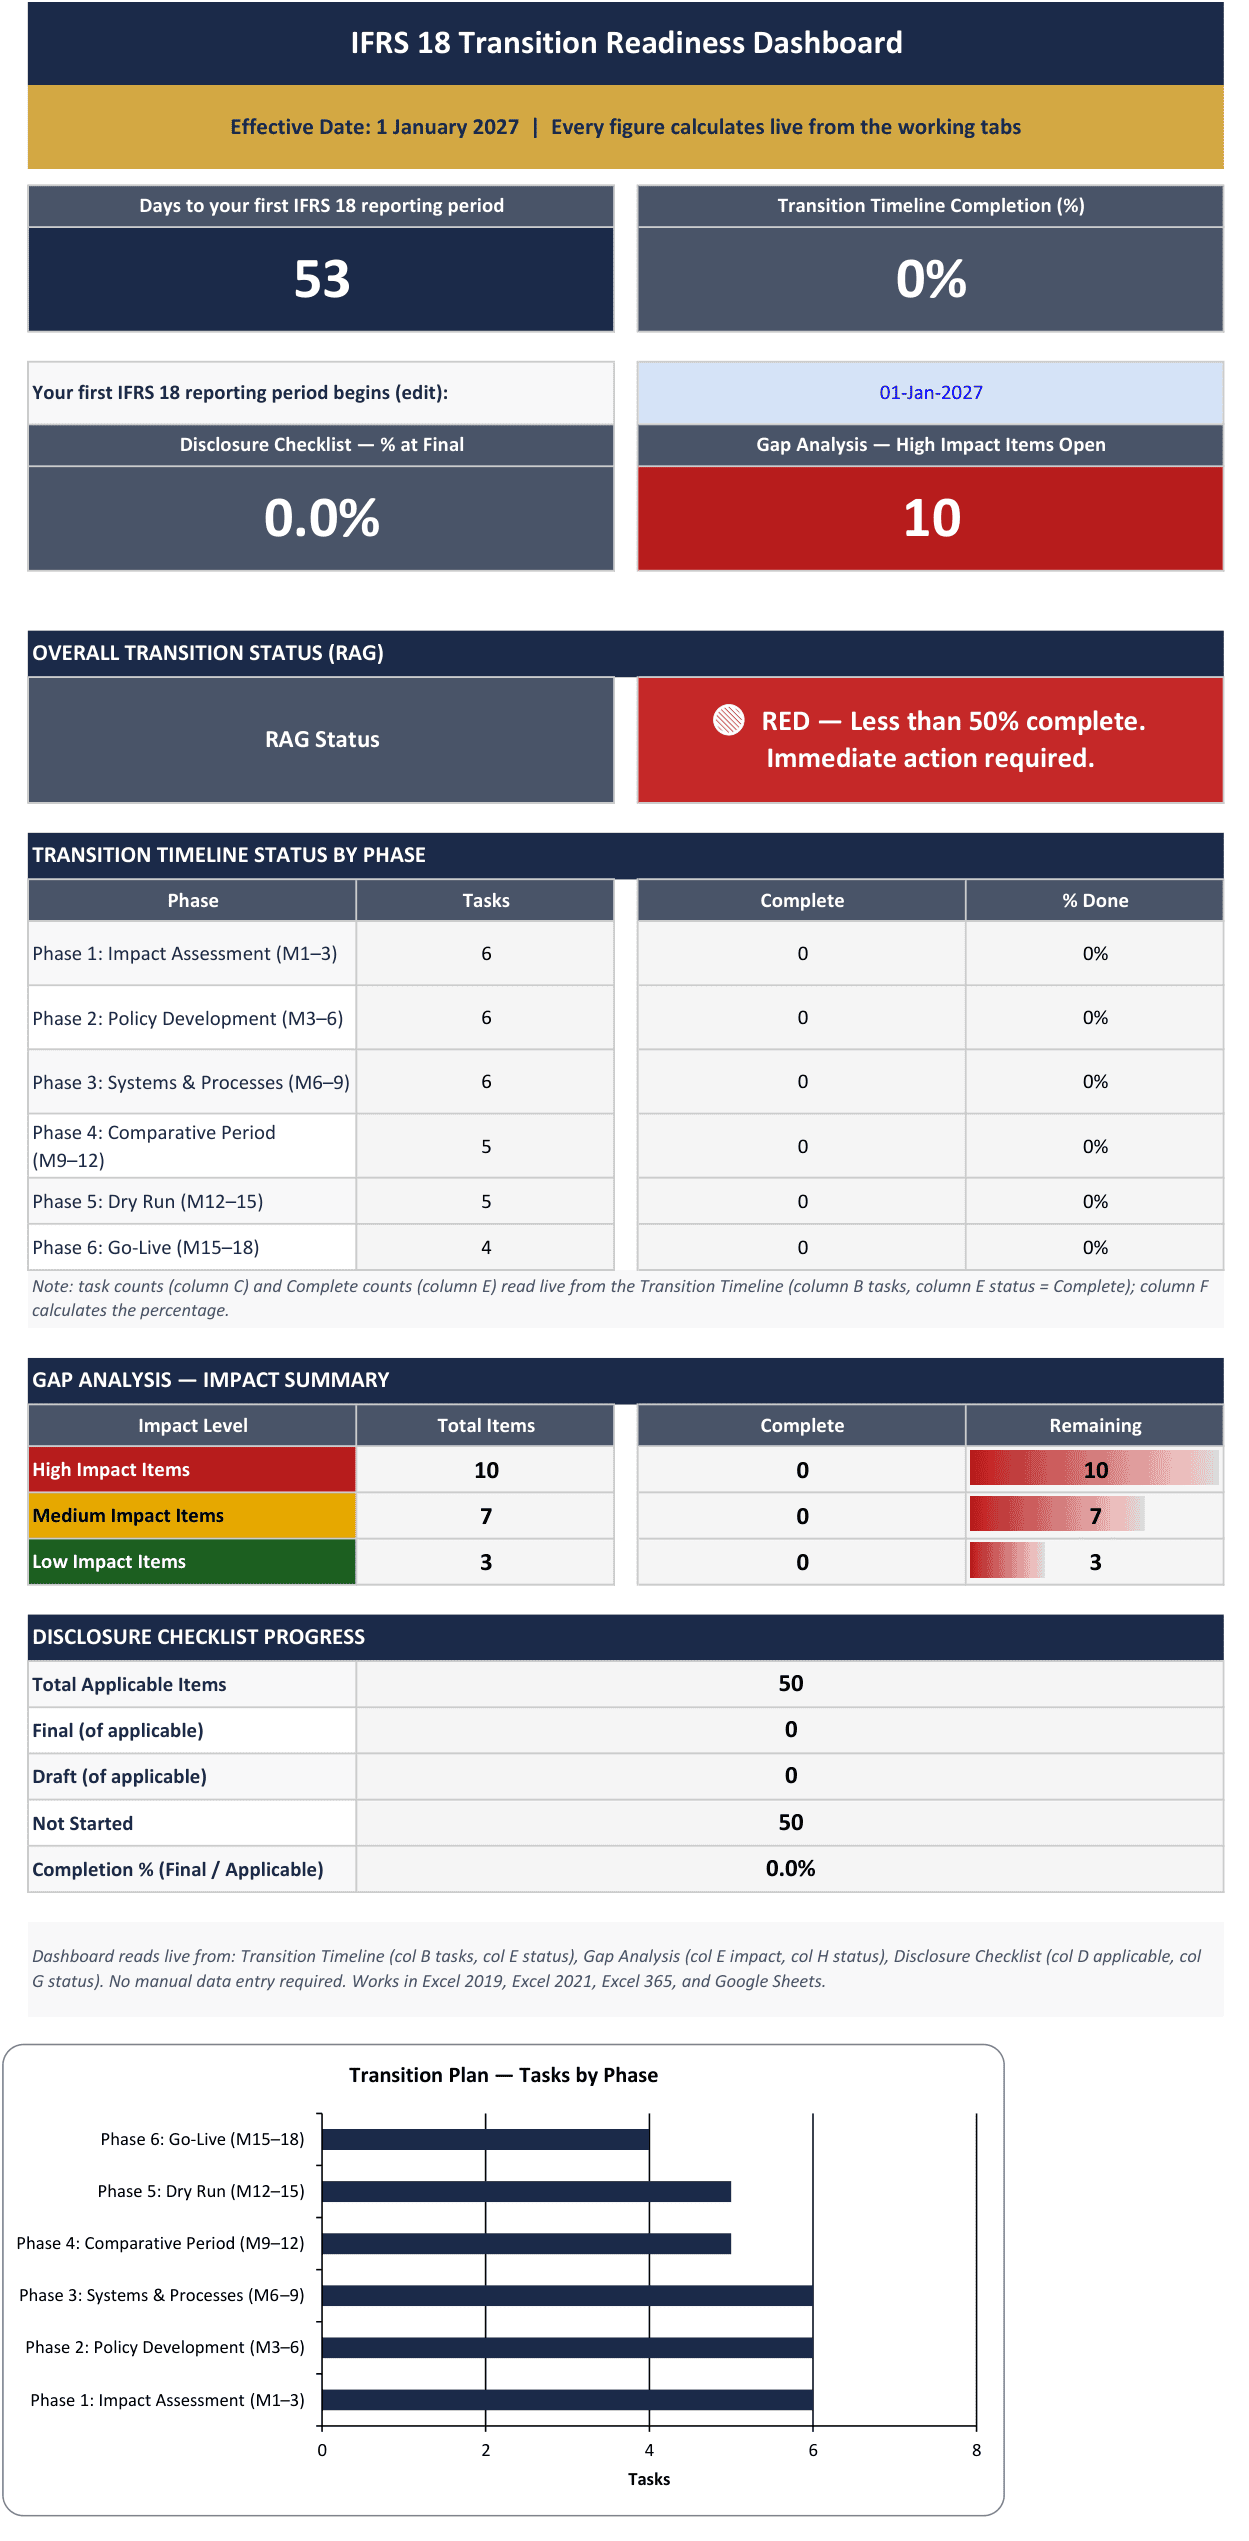
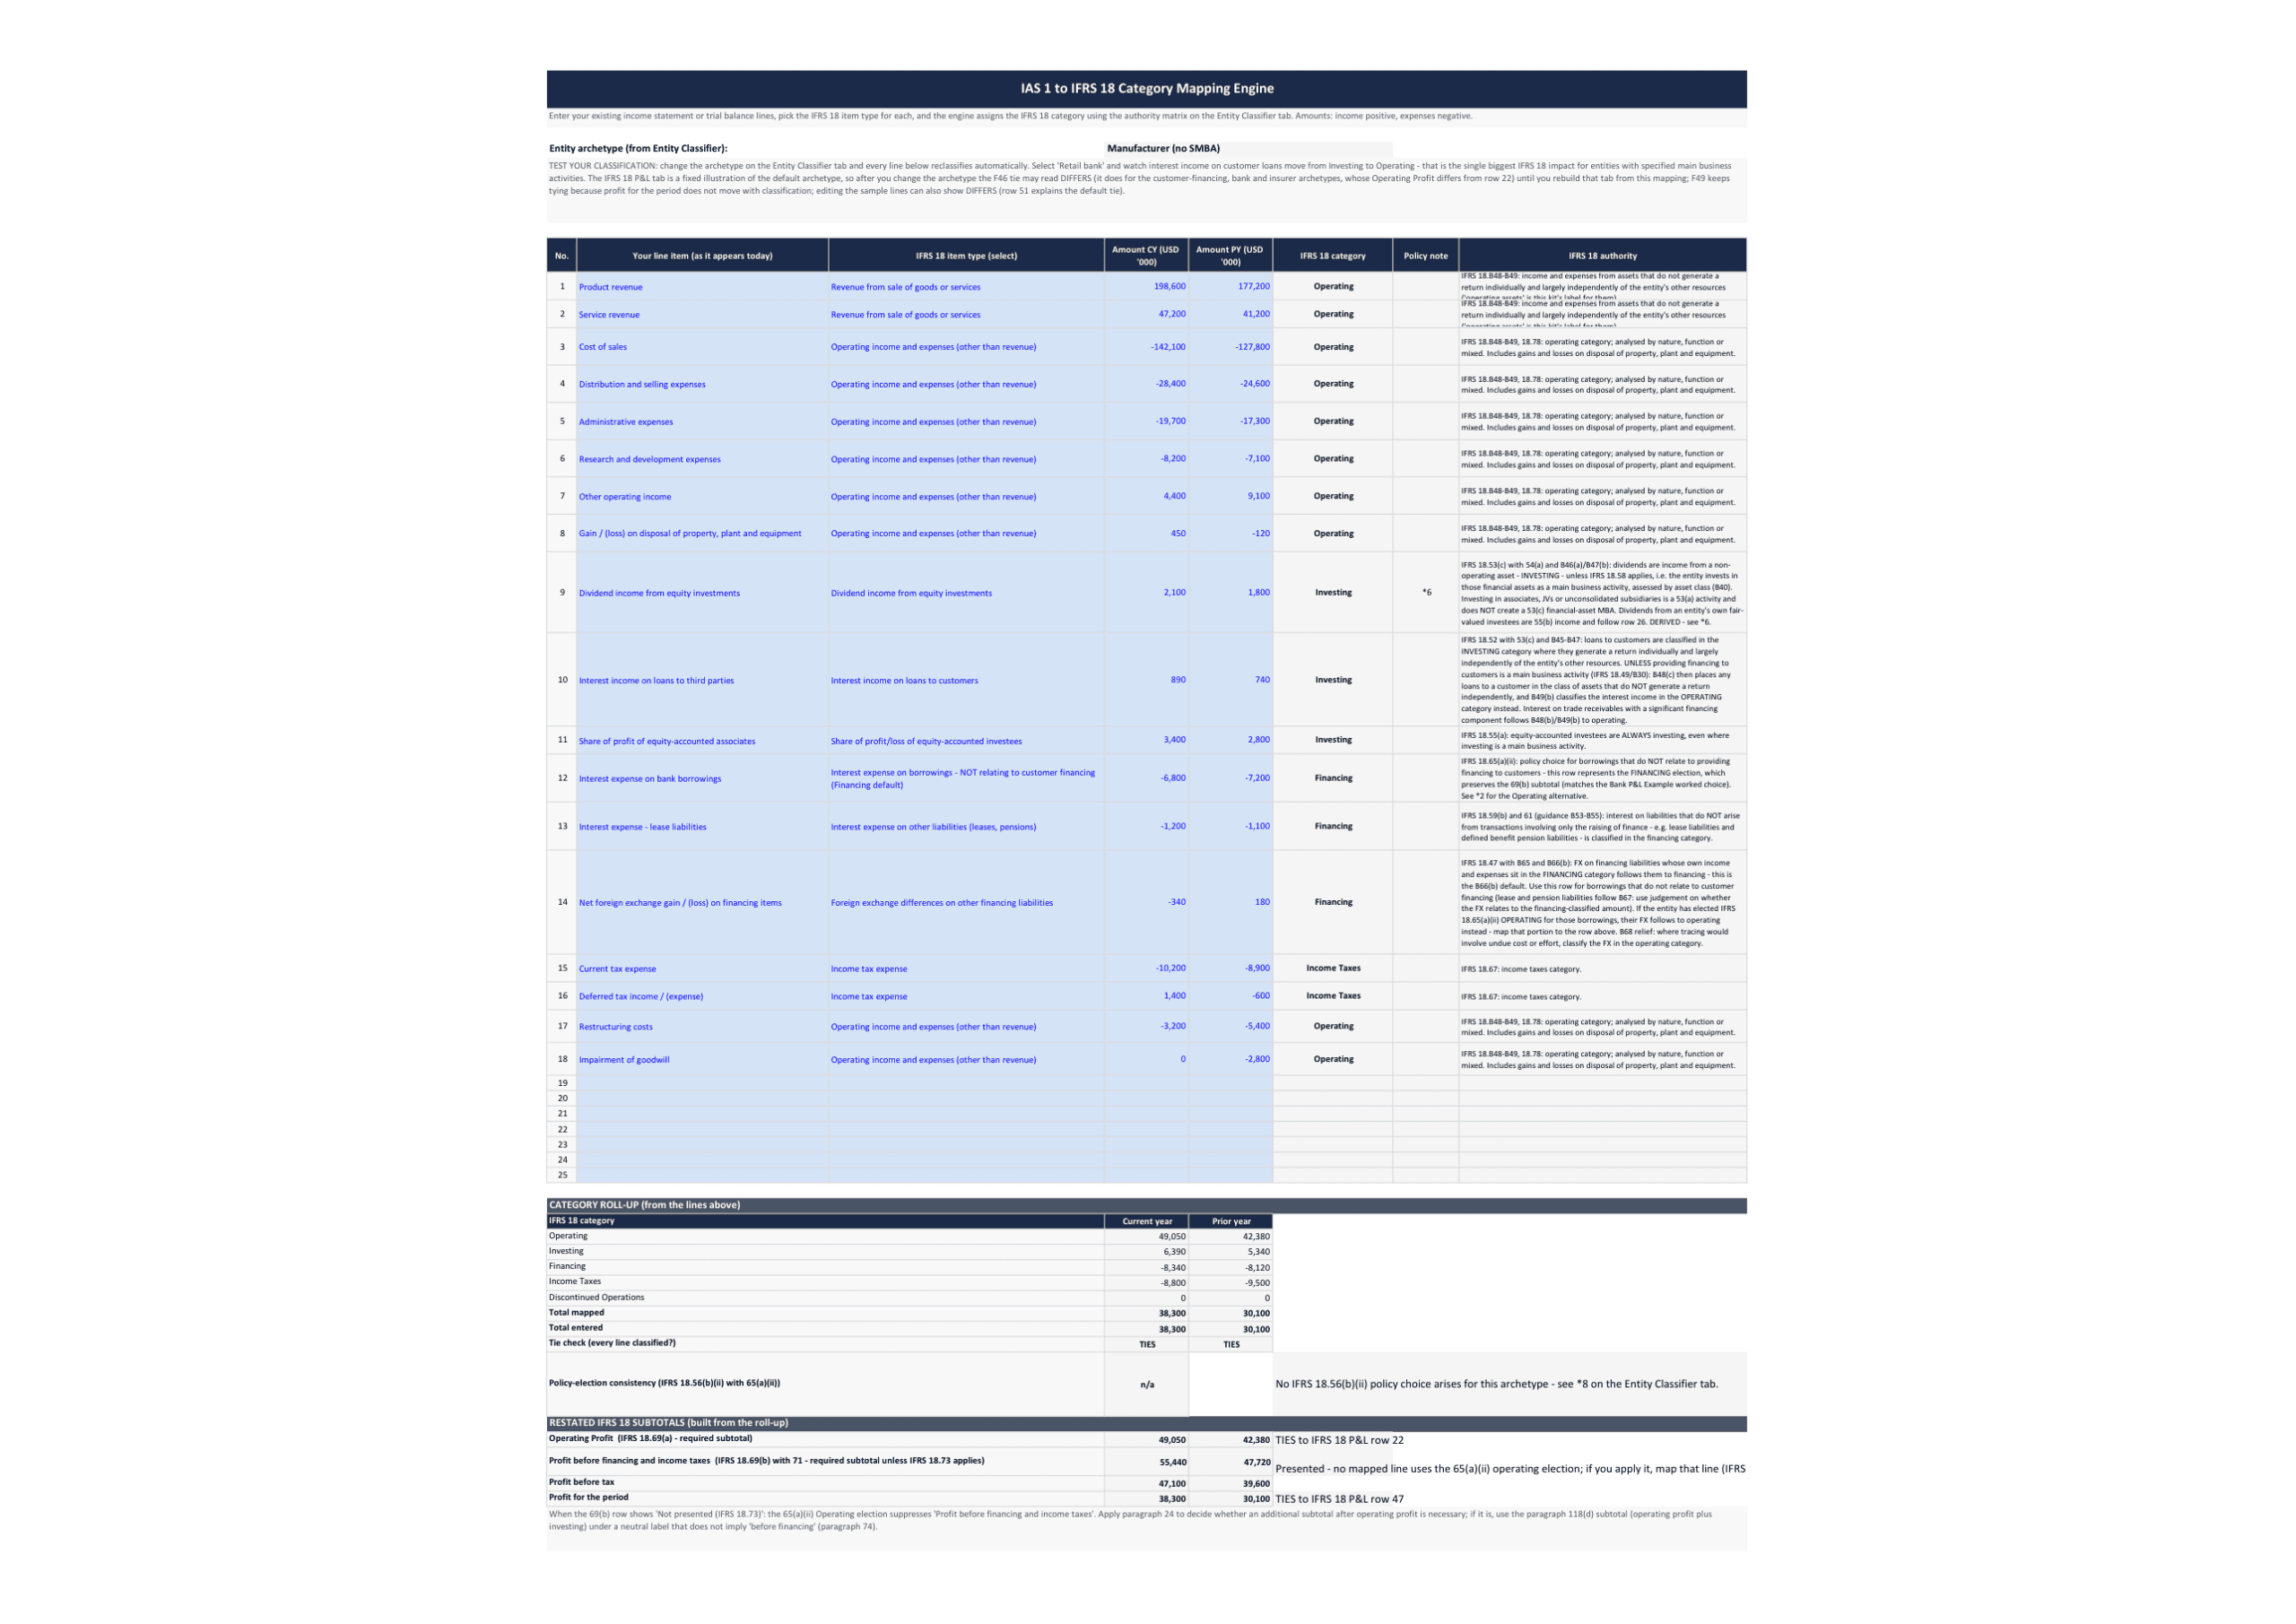
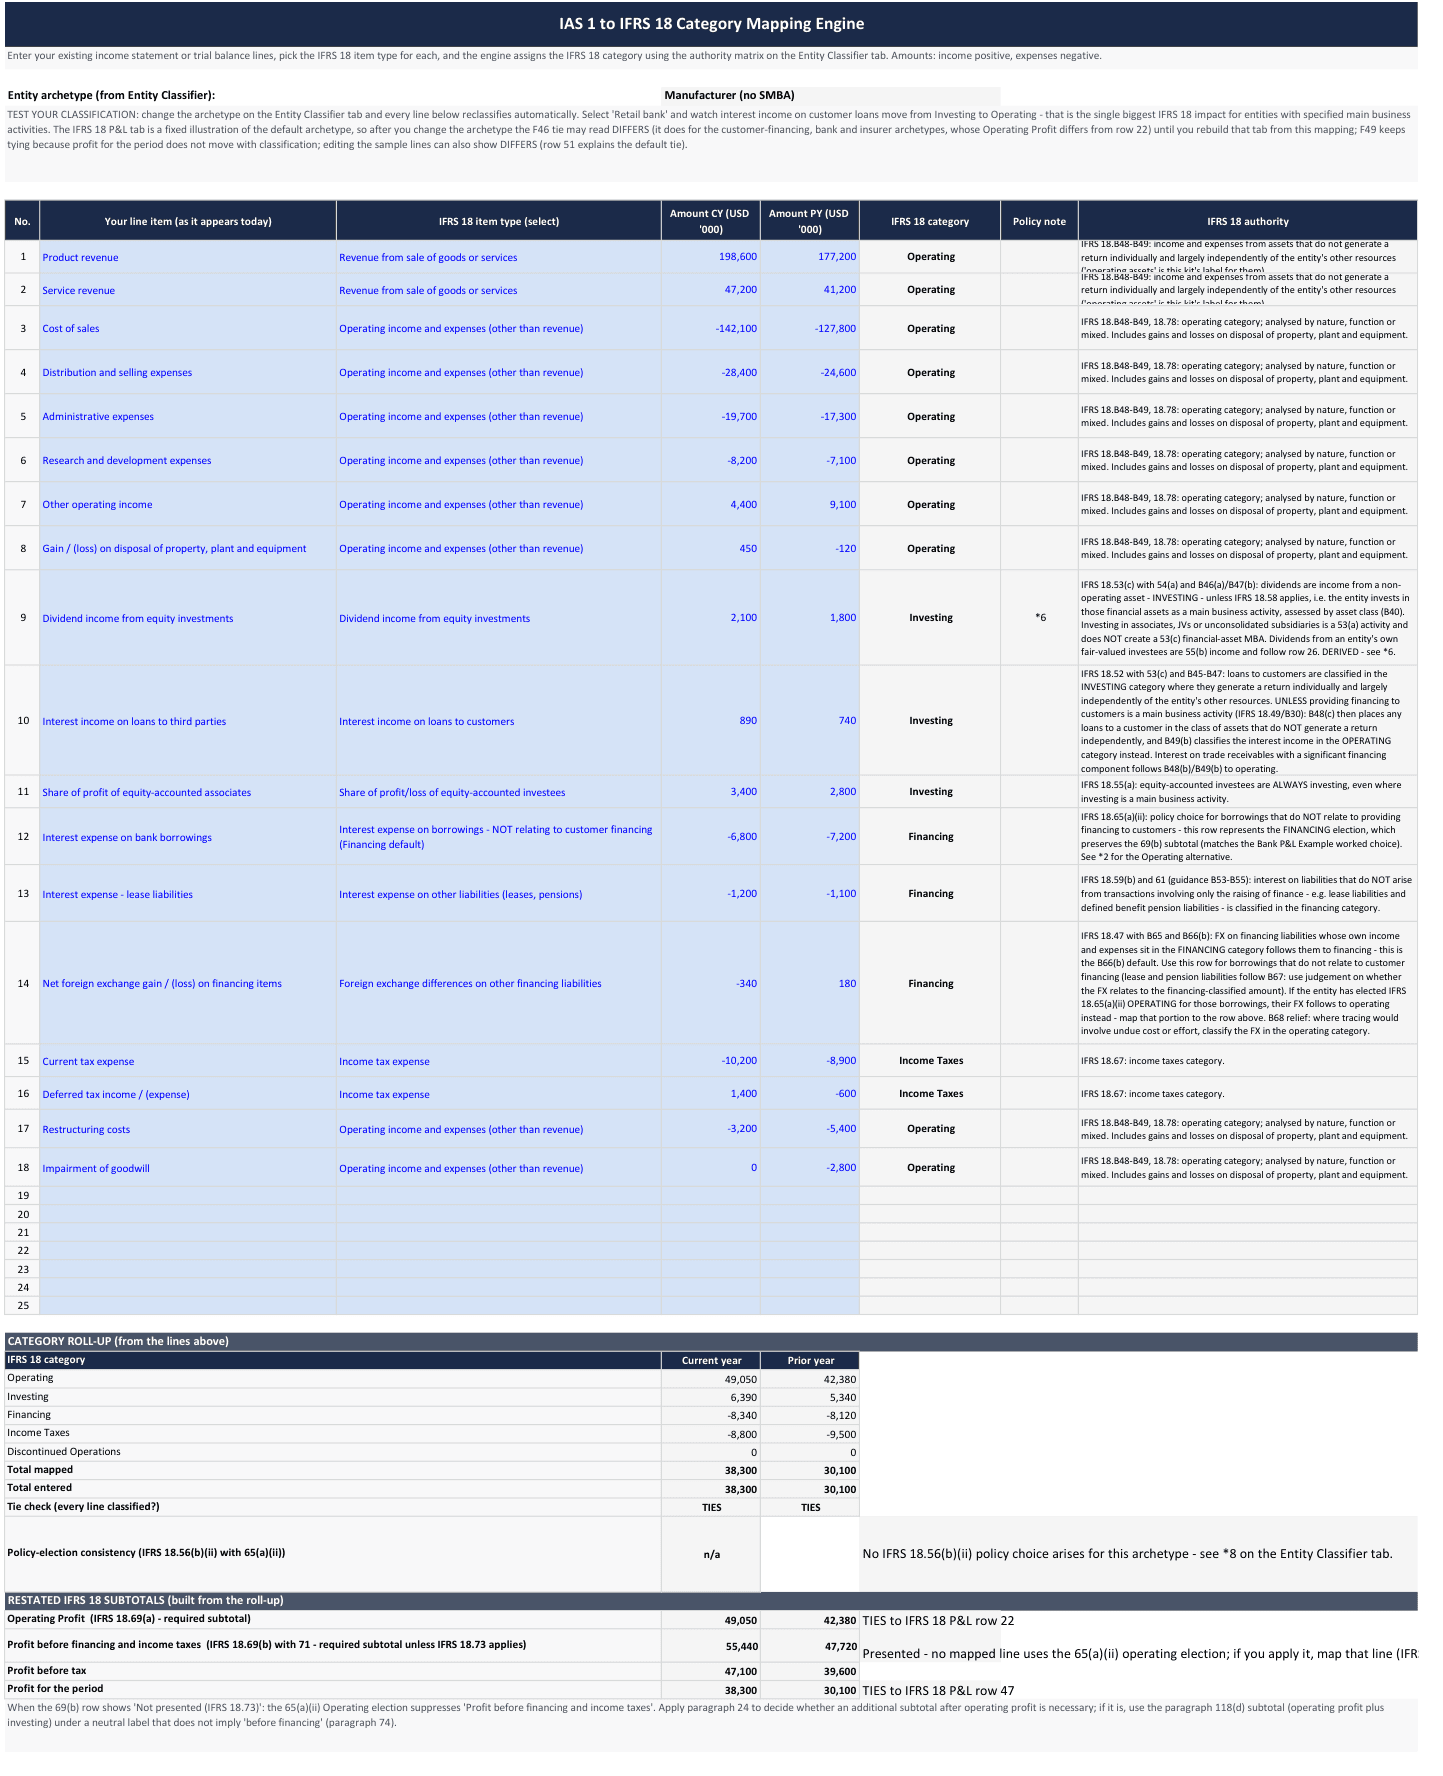
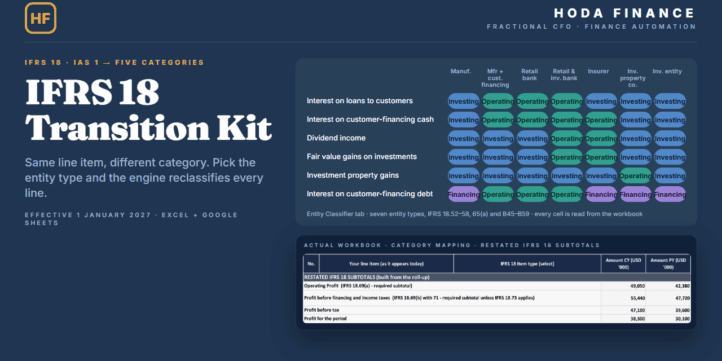
The IFRS 18 Transition Kit is a self-contained working model for technical accountants, controllers and audit teams at IFRS reporters who must restate the income statement for IFRS 18 and evidence every classification judgement. Paste your existing income statement or trial-balance lines into the mapping engine, select an IFRS 18 item type for each and choose your entity archetype, and the workbook classifies every line into the five categories and builds the restated subtotals (the presentation tabs are separate, hand-built statements you complete from the same lines) with both subtotals the standard requires — Operating Profit (IFRS 18.69(a)) and Profit before financing and income taxes (IFRS 18.69(b)). It ships pre-filled with a complete, tied-out worked transition for a manufacturer and a second one for a retail bank.
The differentiator is that classification is computed, not assumed. IFRS 18.49 makes entities with a specified main business activity — investing in assets, or providing financing to customers — classify the same item differently from everyone else, and the kit models this across seven archetypes. In the shipped sample the same eighteen lines give the same profit for the period, 38,300, for every one of the seven archetypes, while Operating Profit reads 49,050 for a manufacturer, 49,940 with customer financing and 52,040 for a bank that also invests in financial assets. Every classification is cited to a paragraph, and the mapping engine reproduces the hand-built income-statement tab independently from the raw lines.
**Model Structure — Excel (12 tabs)**
1. **Start Here** — what IFRS 18 changes, who it applies to, responsibilities, a 7-step quick start, disclaimer
2. **Dashboard** — readiness scorecard: completion %, RAG status, days to 1 January 2027, tasks-by-phase chart
3. **Transition Timeline** — 6-phase plan (18 months in the sample, compressible); 32 tasks with owners, status and target dates
4. **Gap Analysis** — 20 IAS 1 to IFRS 18 requirement points, paragraph-referenced, scored for gap and impact
5. **Entity Classifier** — specified-main-business-activity determination and a 20 × 7 classification matrix (140 cells: 126 classifications and 14 marked not applicable), each row paragraph-cited, with ten footnotes
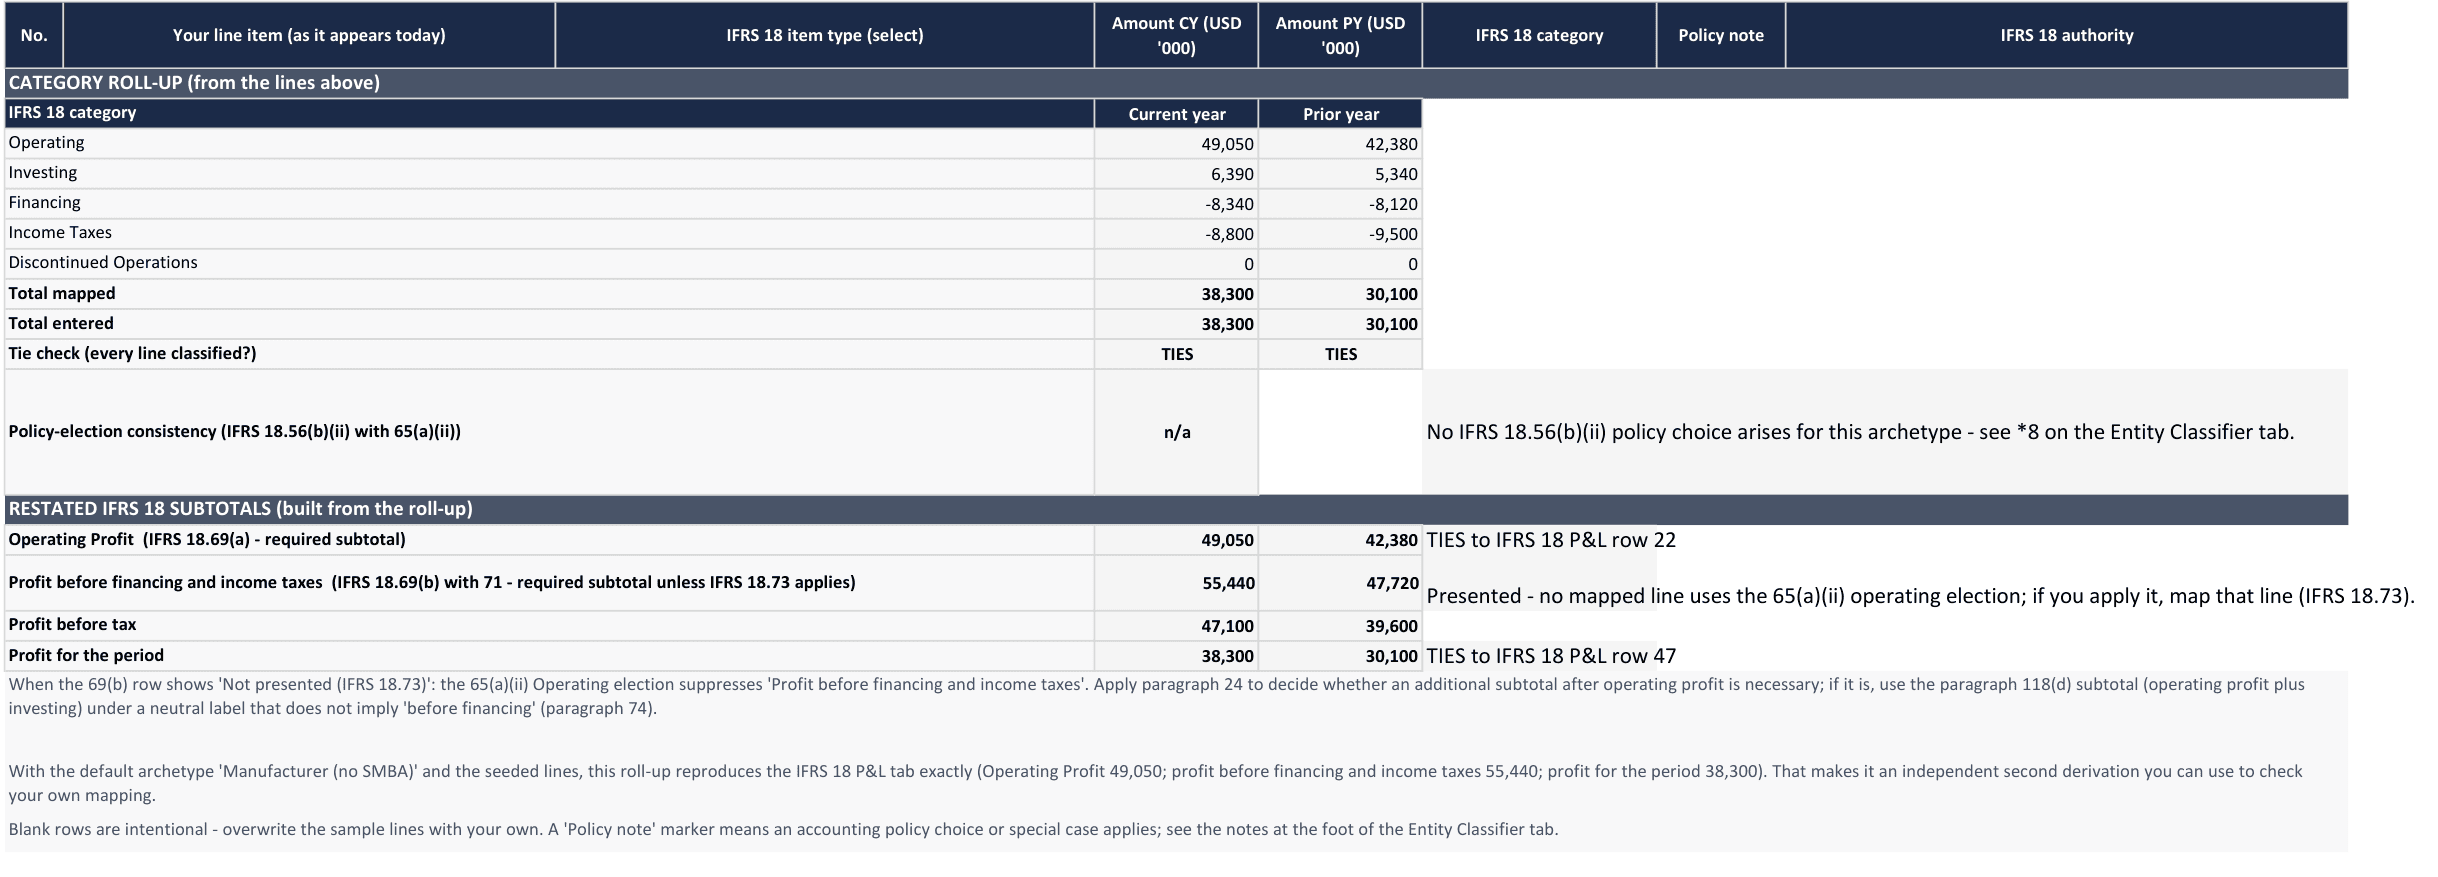
6. **Category Mapping** — the engine: classification lookup, five category roll-ups, restated subtotals, tie check, policy-election check
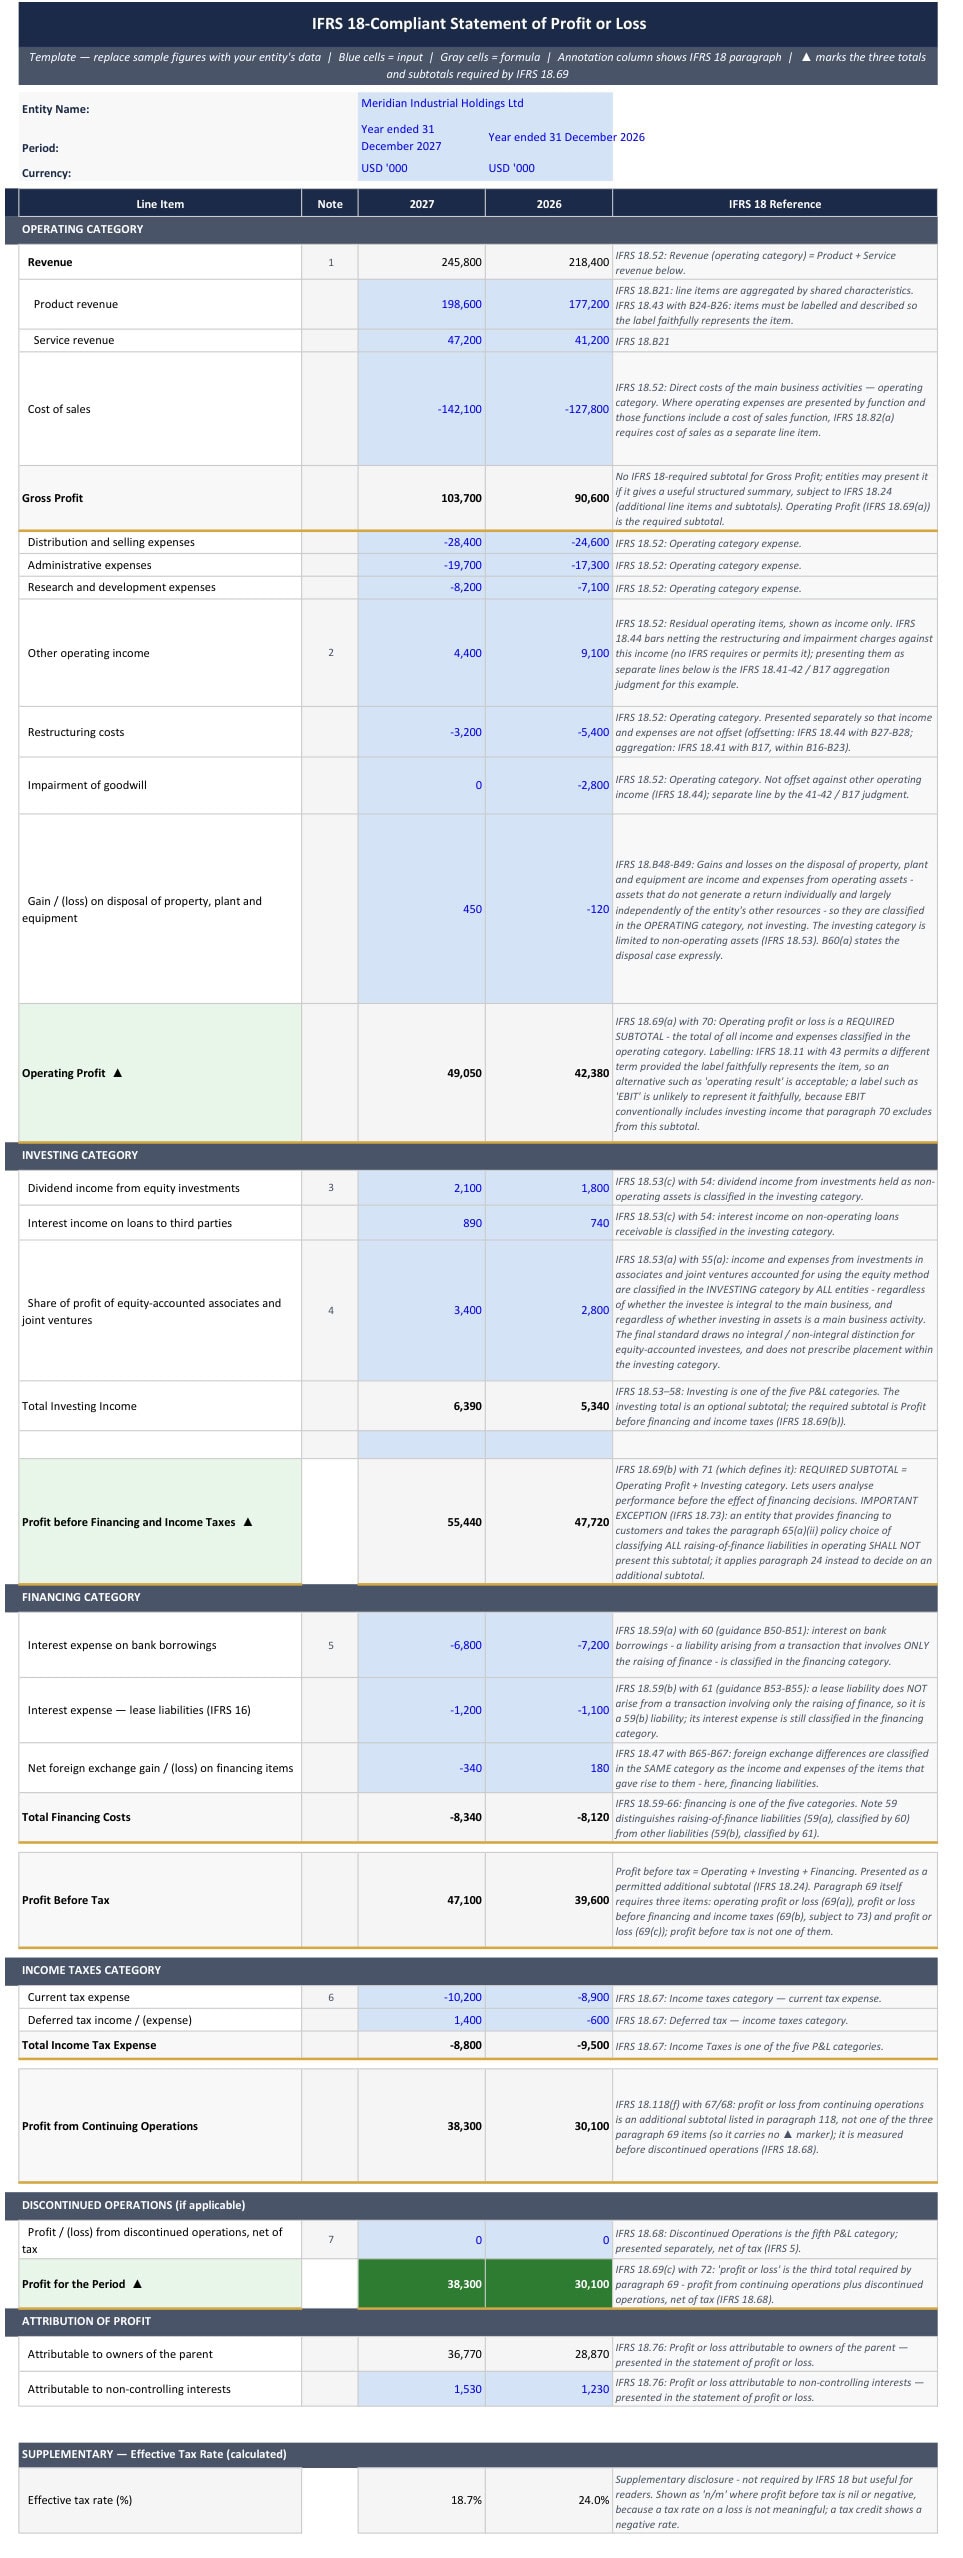
7. **IFRS 18 P&L** — worked manufacturer statement, five categories, both required subtotals, annotated line by line
8. **Bank P&L Example** — parallel statement for an entity with a specified main business activity
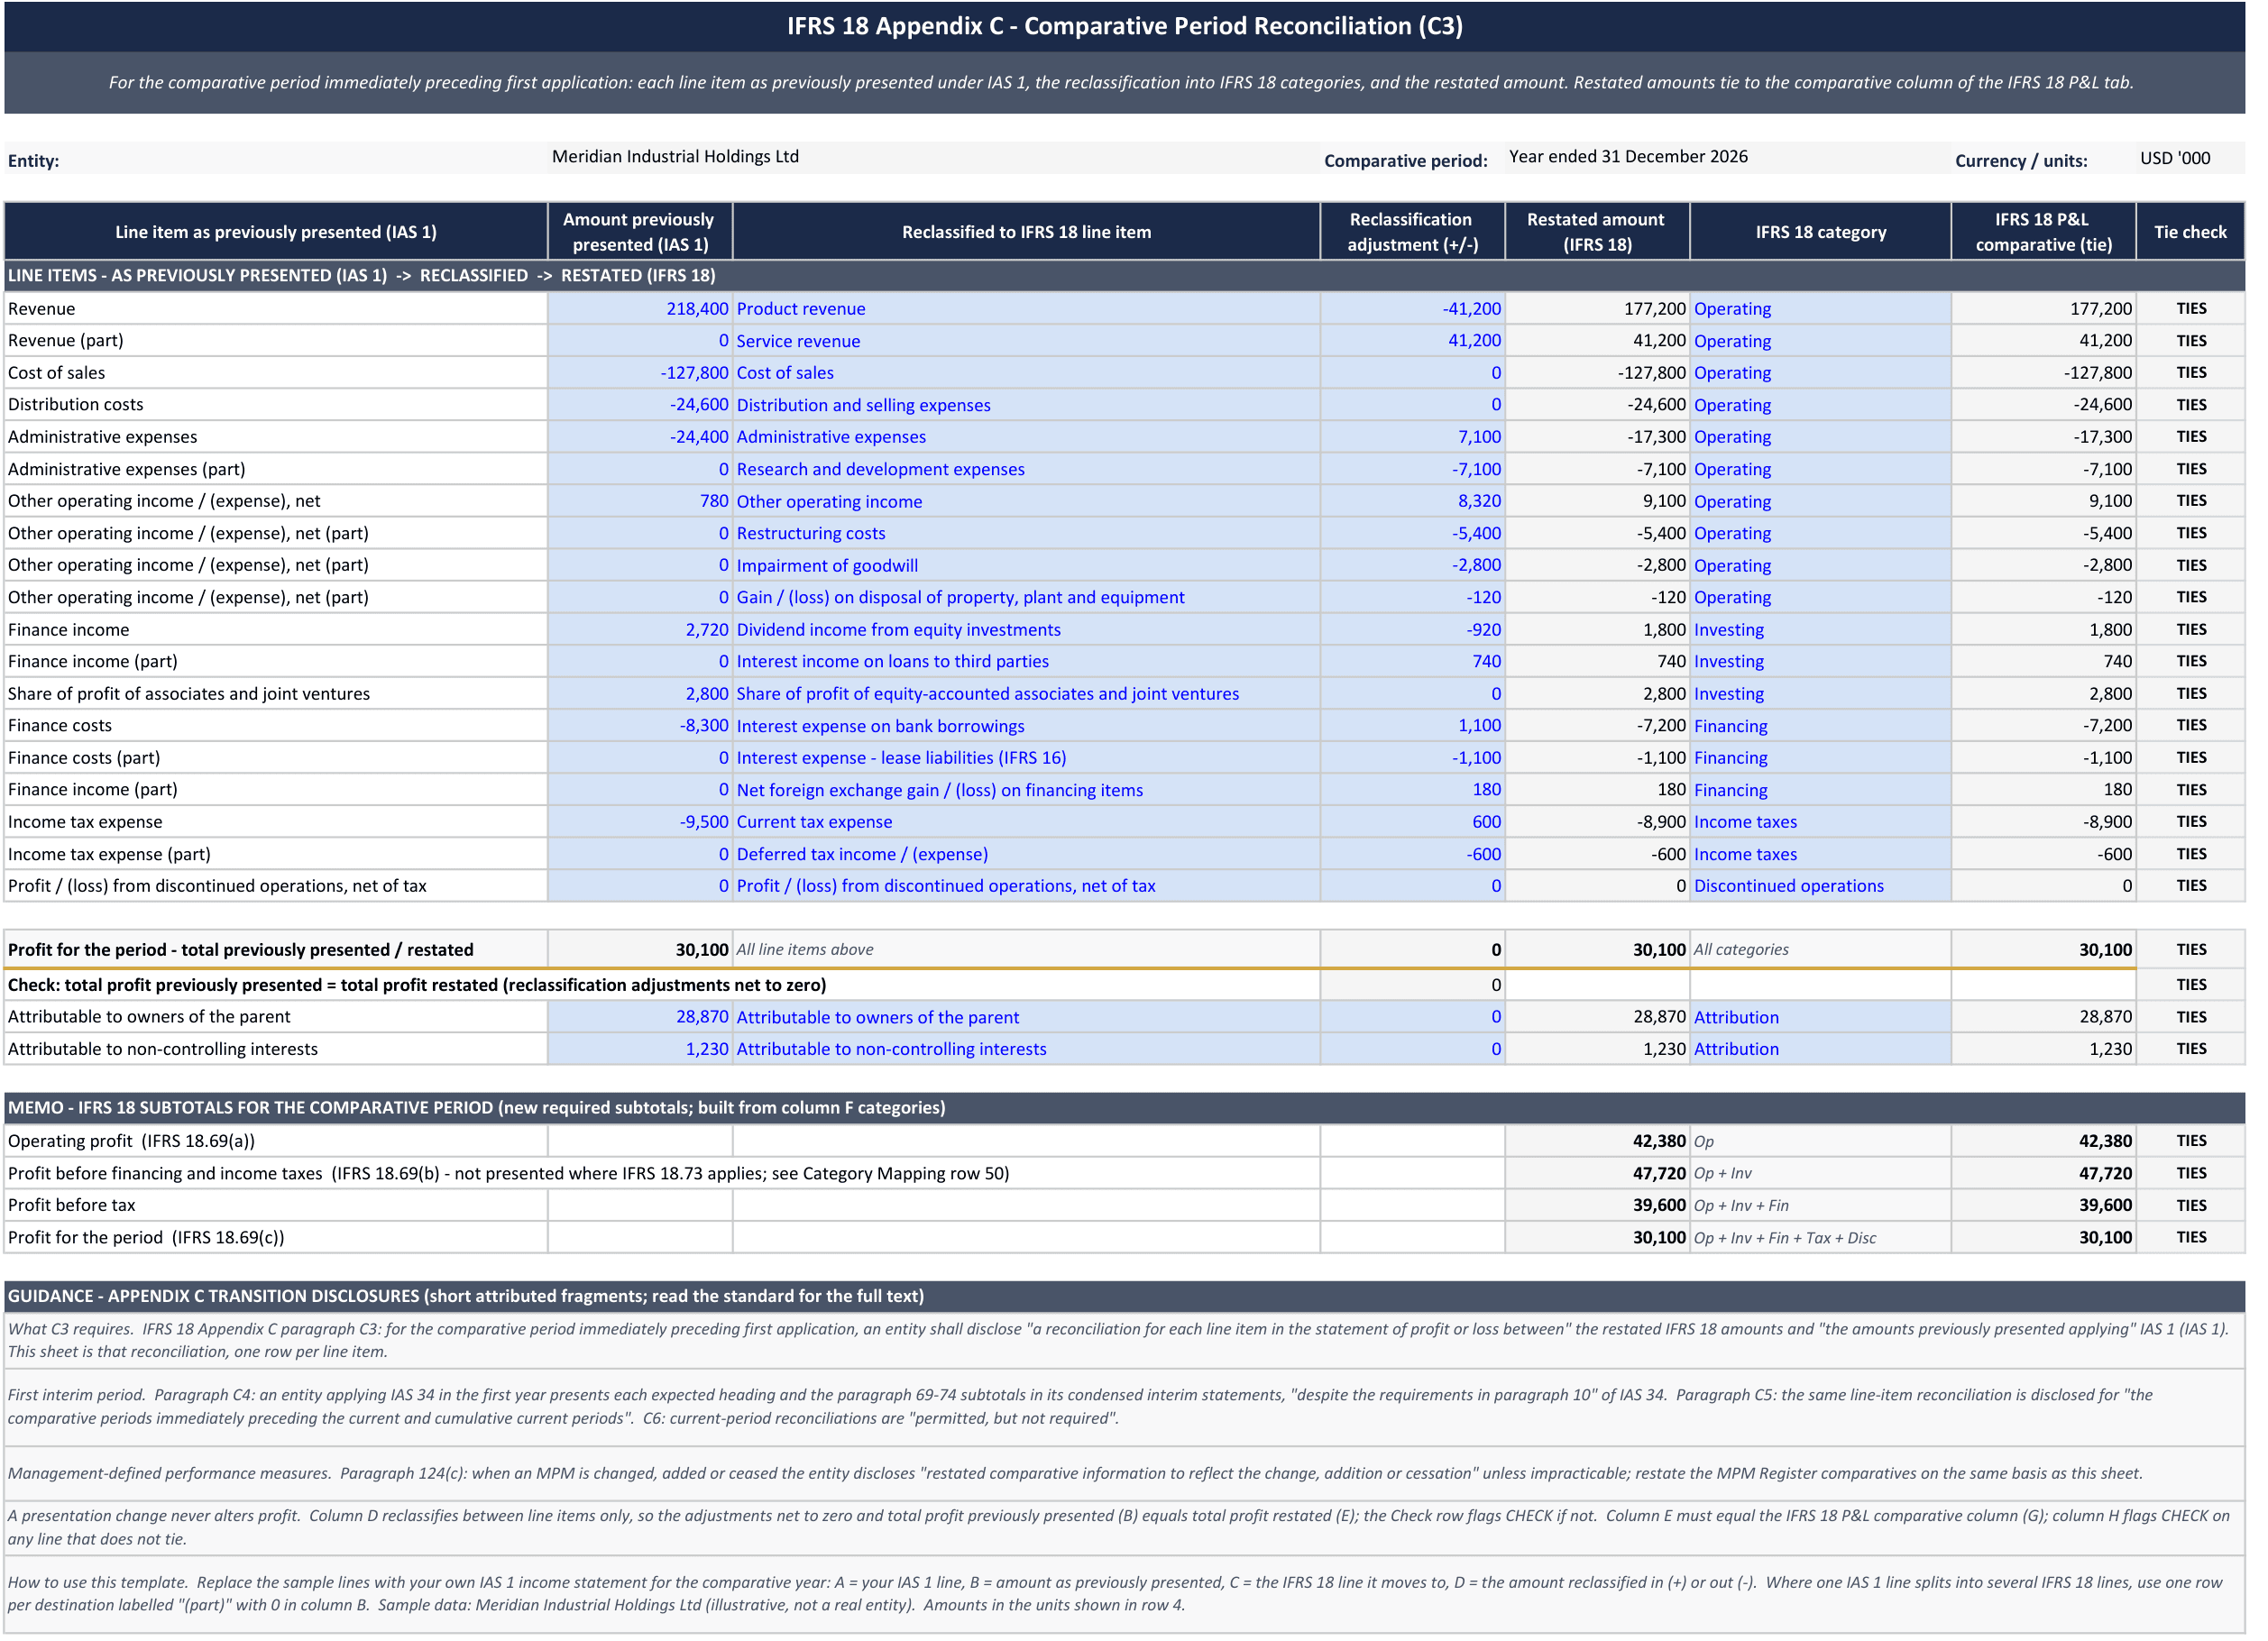
9. **C3 Reconciliation** — comparative-period line-item reconciliation from IAS 1 as previously presented to IFRS 18 restated (Appendix C ¶C3), tying to the IFRS 18 P&L comparative column
10. **MPM Register** — three worked management-defined performance measures with full reconciliations, a per-item income-tax-effect and NCI-effect column for every reconciling item after the paragraph 118 anchor (IFRS 18.123(d), B140(b), B141) and a P&L line-item attribution column (B137(a))
11. **Disclosure Checklist** — 55 points with status roll-up
12. **Board Memo Template** — ready-to-edit briefing for the board or audit committee
**Key Methodological Features**
– Five-category income statement with both IFRS 18 required subtotals, 18.69(a) and 18.69(b)
– Specified main business activity modelled across 7 archetypes under IFRS 18.49, with the 56(b)(ii) and 65(a)(ii) accounting policy elections and the consistency lock between them
– Equity-accounted associates and joint ventures classified to investing for every entity — IFRS 18.53(a) with 55(a)
– Gains and losses on disposal of property, plant and equipment retained in operating — IFRS 18.B48–B49, PPE being an operating asset
– The IFRS 18.73 exception implemented: where the 65(a)(ii) operating election is taken, the 69(b) subtotal must not be presented, and the model suppresses it and directs the user to paragraph 24 with the paragraph 74 labelling constraint
– Management-defined performance measures under 117–124, each reconciled to a subtotal required by IFRS or listed in paragraph 118, with the 123(d) tax and non-controlling-interest effect lines
– Independent second derivation: the mapping engine rebuilds the income statement from raw lines and agrees with the hand-built tab
– Formula-only — no macros, no VBA, no add-ins; runs unchanged in Excel and Google Sheets
**Worked Example**
Pre-loaded with “Meridian Industrial Holdings Ltd” (fictional): revenue 245,800 (all figures USD ‘000, year ended 31 December 2027, prior year 2026) against a prior year of 218,400, gross profit 103,700, Operating Profit 49,050 (42,380) including a 450 gain on disposal of property, plant and equipment, investing 6,390 including the 3,400 share of profit of equity-accounted associates, Profit before financing and income taxes 55,440 (47,720), financing (8,340), income taxes (8,800), profit before tax 47,100 and profit for the period 38,300 (30,100). The MPM Register reconciles Adjusted EBITDA 72,650, Adjusted Operating Profit 53,350 and Adjusted Profit Before Tax 51,400 from those figures. A second worked statement, “Northgate Retail Bank plc” (fictional), gives net interest income 312,600, Operating Profit 125,100, Profit before financing and income taxes 132,900, profit before tax 122,300 and profit for the period 93,000. Replace the inputs with your own figures and every output re-prices.
**Scope**
A presentation and disclosure tool for the income statement and its notes. It does not measure or recognise anything: no IFRS 9 impairment, IFRS 16 lease measurement or IFRS 17 insurance mechanics; no consolidation or currency translation; no statement of financial position, cash flow statement or statement of changes in equity; no XBRL tagging; no filing-ready output.
**Suitable For**
– Technical accountants and financial reporting managers at IFRS reporters
– Financial controllers and CFOs planning and evidencing the transition
– Internal and external audit teams reviewing IFRS 18 readiness
– Entities with specified main business activities — banks, insurers, investment property companies, investment entities
**Technical Specifications**
– Format: .xlsx (Excel edition) + .xlsx (Google Sheets edition) + .pdf (4-page practitioner’s guide)
– Compatibility: Excel 2019, 2021, Microsoft 365 (Windows and Mac) and Google Sheets
– Functions used: COUNTIF, COUNTIFS, SUMIF, SUM, INDEX, MATCH, CHOOSE, IF, IFERROR, ISNA, ISTEXT, AND, OR, MAX, ABS, COUNTA, TODAY — no macros, no VBA, no add-ins, no XLOOKUP, no dynamic arrays
– 12 tabs · 334 formulas · 15 input-validation rules over 483 input cells
– Pre-filled worked transition (manufacturer and bank); replace with your own
– Delivery: instant digital download · single-user license
ABOUT THE AUTHOR
Built by Hoda Elmorshidy — Financial Controller & Fractional CFO, 9+ years in IFRS reporting, FP&A, commodity trading, CFO/board reporting, UAE VAT & Corporate Tax, and finance automation. Practitioner-grade tools, not generic templates.
SCOPE – WHOSE RULES THIS KIT ENCODES
Built for entities that prepare financial statements under IFRS Accounting Standards. IFRS 18 Presentation and Disclosure in Financial Statements was issued by the IASB in April 2024 and applies to annual reporting periods beginning on or after 1 January 2027, with early application permitted.
Adoption is jurisdiction by jurisdiction: an entity in the EU or the UK applies IFRS 18 once local endorsement rules have taken it into their own framework, so confirm the endorsement status that applies to you as at your reporting date. This kit records EU endorsement (Commission Regulation (EU) 2026/338, OJ 16 February 2026) and UK adoption (UK Endorsement Board, December 2025) as verified on 3 November 2026, and does not track any other jurisdiction.
Not for US GAAP filers: IFRS 18 is not part of US GAAP (FASB ASC), so a US GAAP filer does not apply it and nothing here encodes US presentation rules. An entity that reports under IFRS Accounting Standards is in scope wherever it is listed; one reporting under US GAAP is not.
No country’s tax rules are encoded. “Income taxes” here means the IFRS 18 income-taxes category of the income statement, and the income tax effect of each MPM adjustment disclosed under IFRS 18.123(d), computed at whatever rate applies to you: the kit supplies no tax rates, no thresholds, no filing forms and no tax computation for any territory, and contains no sales tax, VAT or GST content. “Non-GAAP measure” is used in its ordinary sense of a measure not defined by IFRS Accounting Standards; it is not a reference to US GAAP.
DISCLAIMER
Not accounting advice. This template is an analytical and educational tool, not professional financial, investment, tax, accounting, or legal advice, and its use creates no professional relationship. All assumptions and figures are illustrative. Verify every IFRS 18 paragraph reference against the current standard text, and confirm your jurisdiction’s endorsement status, as of your reporting date, before relying on any output. The sample entities and all of their figures are fictional. Liability is limited as set out in the licence terms below.
LICENSE & LIABILITY
LICENSE GRANT: Single-user license for your own or your organization’s internal use. No resale, redistribution, sublicensing, or repackaging of the file or its templates.
AS IS: Provided “as is” without warranty of any kind, express or implied, including merchantability or fitness for a particular purpose.
LIMITATION OF LIABILITY: To the maximum extent permitted by law, total liability for any claim arising from this product is limited to the amount you paid for it. Not liable for indirect, incidental, or consequential losses.
NON-WAIVABLE RIGHTS: Nothing here limits rights that cannot be excluded under the consumer-protection law of your jurisdiction.
GOVERNING LAW: This purchase is governed by the terms of the platform you bought it on (e.g. Etsy, Gumroad) and by the consumer-protection law of your own country of residence. Where those permit, the limitations above apply to the maximum extent allowed.
DATA & PRIVACY: This is an offline Excel file. It contains no macros, no data connections, no external links and no telemetry – verified in both editions. Nothing you type into it is transmitted anywhere; your figures stay on your own machine. No AI service is called by the workbook at any point.
Past or sample results are not indicative.
REFUNDS: Digital download — refunds are handled per the refund policy of the platform you purchased on for digital/instant-download items.
TRADEMARKS & NON-AFFILIATION: “IFRS”, “IAS”, “IASB”, “International Financial Reporting Standards” and “International Accounting Standards” are trade marks of the IFRS Foundation. This product is an independent analytical template and is not affiliated with, endorsed by, sponsored by, or approved by the IFRS Foundation or the International Accounting Standards Board. It is not a copy of, or a substitute for, the standard: it quotes only short fragments of IFRS 18, cited by paragraph number. Microsoft Excel and Google Sheets are trademarks of Microsoft Corporation and Google LLC respectively; this product is not affiliated with, endorsed by, or sponsored by either. It is likewise not affiliated with, endorsed by, or sponsored by Etsy, Gumroad, Payhip, eFinancialModels or Eloquens, nor by any benchmark publisher referenced in the workbook. Any other third-party names referenced are the property of their respective owners and are used for descriptive purposes only.
Similar ProductsOther customers were also interested in...


 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more
Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more
Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more
 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.