0 ITEMS
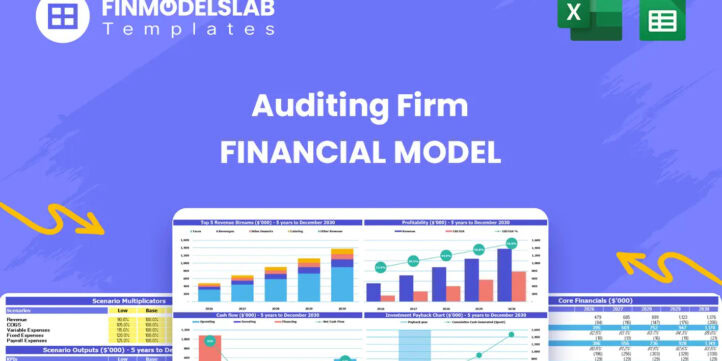
Auditor Financial Model Excel Template
The Auditing Firm Financial Model helps founders, consultants, analysts, and business owners turn an audit practice concept into a structured five-year financial forecast. Instead of starting from a blank spreadsheet, users can work from a ready-to-use financial model template designed around the economics of a modern auditing firm, including billable services, client acquisition, staffing, software costs, overhead, cash flow timing, and profitability. It is built to support business planning, internal budgeting, funding preparation, partner discussions, and lender review. This template helps users organize the assumptions that matter most for an auditing firm, such as service pricing, billable hours, customer acquisition costs, revenue assumptions, payroll requirements, technology investments, startup costs, operating expenses, and direct service delivery costs. By connecting these inputs to revenue forecasts, profit and loss projections, cash flow forecasts, and return metrics, the model makes it easier to understand how the firm may perform under realistic operating conditions. Users can adjust assumptions to reflect a boutique audit practice, a specialized compliance firm, a technology-enabled audit provider, or an established firm planning expansion. The model is useful for decision-making because it shows the relationship between growth, cost structure, staffing capacity, cash flow, and profitability. Entrepreneurs can estimate how much capital is needed before launch, when the business may reach break-even analysis milestones, and which assumptions have the biggest effect on profit. Existing firms can use it to test service mix changes, hiring plans, pricing strategies, or expansion scenarios. Consultants and advisors can use it to prepare financial plans for clients who need a professional, investor-ready forecast. Designed for Microsoft Excel and Google Sheets, the Auditing Firm Financial Model is fully editable and can be adapted to different currencies, markets, service categories, and growth strategies. It includes structured dashboards, scenario planning, revenue modeling, reporting outputs, and performance metrics so users can review the business from multiple angles. Whether you are preparing a business plan, applying for financing, evaluating a new audit service line, or presenting to investors and partners, this template provides a practical framework for building a clear financial story.


Financial Model Overview
The Auditing Firm Financial Model is a ready-to-use financial model template designed to help entrepreneurs, audit firm owners, consultants, analysts, and finance teams forecast the economics of an auditing practice. It brings together the key assumptions needed to plan a professional services business, including client acquisition, billable hours, service pricing, staffing, software costs, overhead, startup investment, cash flow, profitability, and funding needs. For an auditing firm, financial planning must reflect both revenue capacity and delivery capacity, because growth depends on winning clients while also having the qualified team, tools, and processes required to complete audit work efficiently. This template gives users a structured way to model those relationships and convert them into financial statements, dashboards, investor metrics, and planning outputs. It is useful for launching a new firm, expanding an existing practice, preparing a business plan, applying for a loan, raising capital, or testing strategic decisions before committing resources.
All-in-One Dashboard
The all-in-one dashboard gives users a central view of the auditing firm’s core inputs and core outputs in one organized place. It is designed to make the model easier to manage by summarizing the most important assumptions, such as service pricing, client acquisition, billable hour expectations, payroll, overhead, startup investment, and growth rates, alongside the major financial outputs they produce. For an auditing firm, this is especially useful because decision-makers often need to understand how changes in staffing, utilization, marketing spend, or service mix affect revenue, margins, cash flow, and investor returns. The dashboard helps users avoid digging through multiple sheets during planning meetings and provides a practical starting point for reviewing whether the forecast is realistic. It also supports faster decision-making because owners, partners, lenders, and investors can quickly see the financial direction of the firm, compare assumptions against results, and identify areas that require adjustment before moving forward.
Low Base High Scenario Analysis
The low, base, and high scenario analysis section allows users to test the auditing firm under three different operating cases. The base case can represent the most realistic forecast, while the low case can reflect slower client acquisition, lower billable hours, delayed hiring efficiency, or higher customer acquisition costs. The high case can model stronger demand, higher service pricing, better staff utilization, faster adoption of recurring advisory services, or improved retention of audit clients. This component is valuable because an auditing firm’s financial performance can vary significantly depending on deal flow, engagement timing, staff productivity, and market demand for compliance and assurance services. By comparing scenarios, users can see how revenue, EBITDA, cash flow, margins, and capital needs may change if assumptions shift. This makes the template more useful for risk planning, funding discussions, and strategic decision-making, because it helps users prepare contingency plans rather than relying on a single optimistic forecast.
Professional Charts
The professional charts component converts the financial forecast into presentation-ready visuals that can be used in planning sessions, investor meetings, lender discussions, board updates, or internal reviews. Instead of relying only on rows of spreadsheet data, users can view revenue trends, profitability development, expense patterns, cash flow movement, margin performance, and other key financial indicators through charts and graphs. For an auditing firm, visual reporting is useful because stakeholders often want to understand how the business scales over time, whether revenue growth is supported by staffing capacity, and how fixed overhead is absorbed as client volume increases. The charts help make the financial story clearer and easier to communicate, especially when presenting a five-year forecast to people who may not want to review every formula in detail. This section also supports more polished business plans and funding documents by helping users demonstrate growth, operating leverage, and financial discipline in a concise visual format.
ROE Components and DuPont Analysis
The ROE components and DuPont analysis section helps users understand the drivers behind return on equity rather than viewing ROE as a single isolated metric. This component can break down performance into profitability, asset efficiency, and financial leverage, allowing users to see whether the auditing firm’s shareholder returns are coming from strong margins, efficient use of assets, or the capital structure of the business. For an auditing firm, this is especially relevant because the company may not require heavy physical assets compared with other industries, but it may still invest in technology, audit software, proprietary platforms, working capital, and skilled staff. By reviewing DuPont analysis, users can identify whether improvements should come from increasing service pricing, improving staff utilization, controlling expenses, shortening billing cycles, or optimizing the balance between equity and debt. This makes the model more useful for investors, partners, and owners who want to evaluate long-term value creation and the quality of financial returns.
Revenue Inputs
The revenue inputs section is where users define the assumptions that drive the auditing firm’s top-line forecast. It may include the firm’s core service lines, such as financial statement audits, internal control and SOX audits, agreed-upon procedures, advisory services, or data analytics subscriptions, along with assumptions for pricing, billable hours, client volume, marketing spend, customer acquisition cost, retention, and growth rates. This component is important because revenue in an auditing firm is typically built from a combination of client acquisition, recurring engagements, project-based work, hourly billing, and service mix. By entering assumptions in a structured format, users can see how each revenue stream contributes to total sales and how changes in rates, client count, or utilization affect the forecast. This section supports more credible planning because it links revenue to operational drivers instead of relying on broad estimates, making it easier to explain the forecast to partners, lenders, investors, or internal decision-makers.
Bank-Ready Reports
The bank-ready reports section organizes the model’s financial outputs into a format that is easier for lenders, investors, and business partners to review. It can include projected income statements, cash flow statements, balance sheet summaries, profitability metrics, debt service considerations, capital needs, and other lender-friendly financial outputs. For an auditing firm seeking financing, this component is useful because banks and funding partners typically want to see more than revenue projections. They want to understand whether the business can cover payroll, rent, software subscriptions, professional liability costs, marketing expenses, debt payments, and working capital needs while maintaining sufficient liquidity. The reports help users present a complete financial picture and reduce the time required to prepare supporting documents for a loan application or investment review. Because the outputs are connected to the model’s assumptions, users can update inputs and generate revised reports quickly when a lender requests a different case, repayment structure, or funding amount.
Revenue Breakdown
The revenue breakdown section provides a detailed view of how each revenue stream contributes to the auditing firm’s total income. Rather than showing one consolidated sales number, it separates revenue by service category, client type, engagement model, billing method, or recurring versus project-based work. This is useful for auditing firms because different services can have very different economics. A financial statement audit may require a specific number of billable hours and senior review time, while internal control audits, agreed-upon procedures, data analytics subscriptions, or compliance advisory projects may have different pricing, margins, and delivery requirements. By reviewing the revenue breakdown, users can identify which services generate the most income, which are most scalable, and which may require additional staffing or technology investment. This section supports pricing decisions, sales strategy, capacity planning, and profitability analysis by showing the composition of revenue and helping users focus growth efforts on the most attractive service lines.
KPI Dashboard
The KPI dashboard tracks the performance metrics that matter most for an auditing firm and helps users compare projected results against targets or industry benchmarks. It may include metrics such as revenue growth, gross margin, EBITDA margin, revenue per employee, billable utilization, client acquisition cost, payback period, cash balance, return on equity, and other indicators relevant to professional services firms. This component is useful because a financial forecast is more valuable when users can monitor performance drivers, not just final profit figures. For example, if revenue is growing but utilization is falling, the firm may be hiring ahead of demand. If margins are strong but cash flow is tight, billing terms or collections may need improvement. The KPI dashboard gives founders, partners, managers, and investors a concise view of operational and financial health. It supports better decision-making by highlighting whether the firm is scaling efficiently, maintaining profitability, and staying aligned with its planned financial targets.
Startup Costs and Operating Expense Planning
The startup costs and operating expense planning section helps users estimate the capital required to launch and operate the auditing firm before it reaches stable profitability. Startup costs may include technology setup, audit software, servers or workstations, office furniture, licenses, legal formation, insurance, initial marketing, website development, platform development, recruiting, deposits, and working capital reserves. Ongoing expenses may include payroll, rent, software subscriptions, professional liability insurance, compliance tools, marketing, training, outsourced specialists, administrative support, and general overhead. This component is important because professional services firms often look lean from the outside but can require significant upfront investment in talent, systems, credibility, and client acquisition. By separating one-time launch costs from recurring operating expenses, the model helps users understand the amount of funding needed, how much cash runway is required, and which costs should be controlled during the early months. It also supports budgeting discipline and helps reduce the risk of unexpected cash shortfalls.
Break-Even Analysis
The break-even analysis section helps users identify when the auditing firm can cover its fixed and variable costs from operating revenue. It can use assumptions such as average service pricing, billable hours, gross margin, payroll, software costs, marketing spend, overhead, and client acquisition pace to calculate the sales volume or monthly revenue required to reach break-even. For an auditing firm, this is a critical planning tool because the business may carry meaningful fixed costs, including qualified staff, technology, insurance, office expenses, and compliance infrastructure, before a full client base has been built. The break-even analysis helps users understand how many clients, engagements, or recurring revenue streams are needed to support the cost structure. It is also valuable for funding preparation because lenders and investors often want to know how quickly the business can move from cash consumption to self-sustaining operations. By testing different pricing, staffing, and growth assumptions, users can evaluate ways to accelerate profitability and make more informed launch or expansion decisions.
File types:
Excel – Single-User: .xlsx
Excel – Multi-User: .xlsx
Similar ProductsOther customers were also interested in...
 HenrySheykin
Financial Advisors Agency Financial Model Excel Te...
The Financial Advisor Financial Model is a ready-to-use financial model template built for planning,... Read more
Business Brokerage Financial Model Excel Template
The Business Brokerage Financial Model helps entrepreneurs, brokerage owners, consultants, analysts,... Read more
Bookkeeping Agency Financial Model Excel Template
The Accounting Firm Financial Model Template helps founders, practice owners, consultants, analysts,... Read more
 Giorgos
Accounting Firm – 10 Year Financial Model
10-year financial model for an accounting firm providing forecasts, profitability analysis, and insi... Read more
Law Firm Financial Model Excel Template
The Law Firm Financial Model Template helps users turn a legal practice concept into a structured fi... Read more
Legal Services Financial Model Excel Template
The Legal Services Financial Model Financial Model Template helps entrepreneurs, law firm founders, ... Read more
Corporate Trainer Financial Model Excel Template
The Corporate Training Financial Model helps users turn a professional development or corporate lear... Read more
Attorney Employment Agency Financial Model Excel T...
The Recruiting Agency Financial Model helps founders, agency owners, consultants, and analysts build... Read more
Savings Bank Financial Model Excel Template
The Savings Bank Financial Model helps entrepreneurs, bank founders, consultants, analysts, and busi... Read more
Recruitment Agency Financial Model Excel Template
The Recruiting Agency Financial Model helps founders, agency owners, consultants, and analysts build... Read more
You must log in to submit a review.