0 ITEMS
Break-Even Analysis in Excel: Formulas, Charts & Templates
Your break-even point (BEP) is the exact unit count or revenue figure where total costs equal total revenue — zero profit, zero loss. Build it correctly in Excel and you turn a static number into a live decision-making tool.
Key Takeaways
- The core break-even formula is Fixed Costs divided by (Price per Unit minus Variable Cost per Unit), giving you the exact unit count needed to cover all costs.
- Contribution margin — price minus variable cost per unit — is the engine of every break-even model; a SaaS business typically achieves a 70-85% contribution margin, while manufacturing firms average 30-50%.
- A two-variable Excel data table lets you stress-test break-even across 25+ price-and-volume combinations in under 60 seconds, turning a static number into a dynamic planning tool.
- 3 fully worked examples (SaaS, manufacturing, service) show how the same formula produces radically different break-even timelines depending on cost structure.
- According to the U.S. Small Business Administration, roughly 20% of new businesses fail within their first year, and cash-flow shortfalls — often caused by misjudging break-even timing — are a leading driver.
- Common Excel errors (circular references, mixed cost classification, ignoring capacity limits) can overstate profitability by 15-30% if left uncorrected.
- A pre-built break-even template with sensitivity tables and a visual chart cuts model-build time from hours to under 5 minutes.
What Break-Even Point Analysis Reveals About Your Business Model
Break-even analysis answers one question precisely: how many units — or how much revenue — do you need before you stop losing money? Every pricing decision, cost-reduction initiative, and capacity investment changes that number, which is why the analysis must be dynamic, not a one-time calculation.
The BEP sits at the intersection of three forces: your fixed cost base (rent, salaries, software licenses — costs that don’t move with volume), your variable costs (materials, commissions, cloud compute — costs that scale with output), and your selling price. Change any one of those three and the break-even point shifts immediately.
According to the U.S. Small Business Administration, approximately 20% of new businesses fail within the first year.
Inadequate financial planning — including failure to model break-even timing — is consistently cited among the root causes. Building a live Excel model forces founders and managers to confront that timing before it becomes a crisis.
Cost structure determines break-even speed: SaaS firms reach profitability faster per unit due to near-zero variable costs, while manufacturers need far higher volume.
The Break-Even Formula Decoded: Fixed Costs, Variable Costs, and Contribution Margin
The break-even formula has two outputs: units and revenue. Both derive from the contribution margin, which is the amount each unit sale contributes toward covering fixed costs after variable costs are paid.
Contribution margin per unit = Price per Unit (P) minus Variable Cost per Unit (VC)
Break-even units = Fixed Costs (FC) divided by Contribution Margin per Unit
Break-even revenue = Break-even Units multiplied by Price per Unit
Or equivalently:
Break-even revenue = Fixed Costs divided by Contribution Margin Ratio, where Contribution Margin Ratio = (P minus VC) divided by P
In Excel cell notation, if you place Fixed Costs in B2, Variable Cost per Unit in B3, and Price per Unit in B4:
Break-even units: =B2/(B4-B3) in cell B6
Break-even revenue: =B6*B4 in cell B7
Contribution margin per unit: =B4-B3 in cell B5
Contribution margin ratio: =(B4-B3)/B4 in cell B8, formatted as a percentage
These four formulas are the core of every break-even model. Everything else — charts, sensitivity tables, scenario toggles — feeds from them. Excel’s CEILING function supports rounding up to the nearest whole unit.
This is essential when break-even calculations return a decimal — you must always round up because you cannot sell a fraction of a unit.
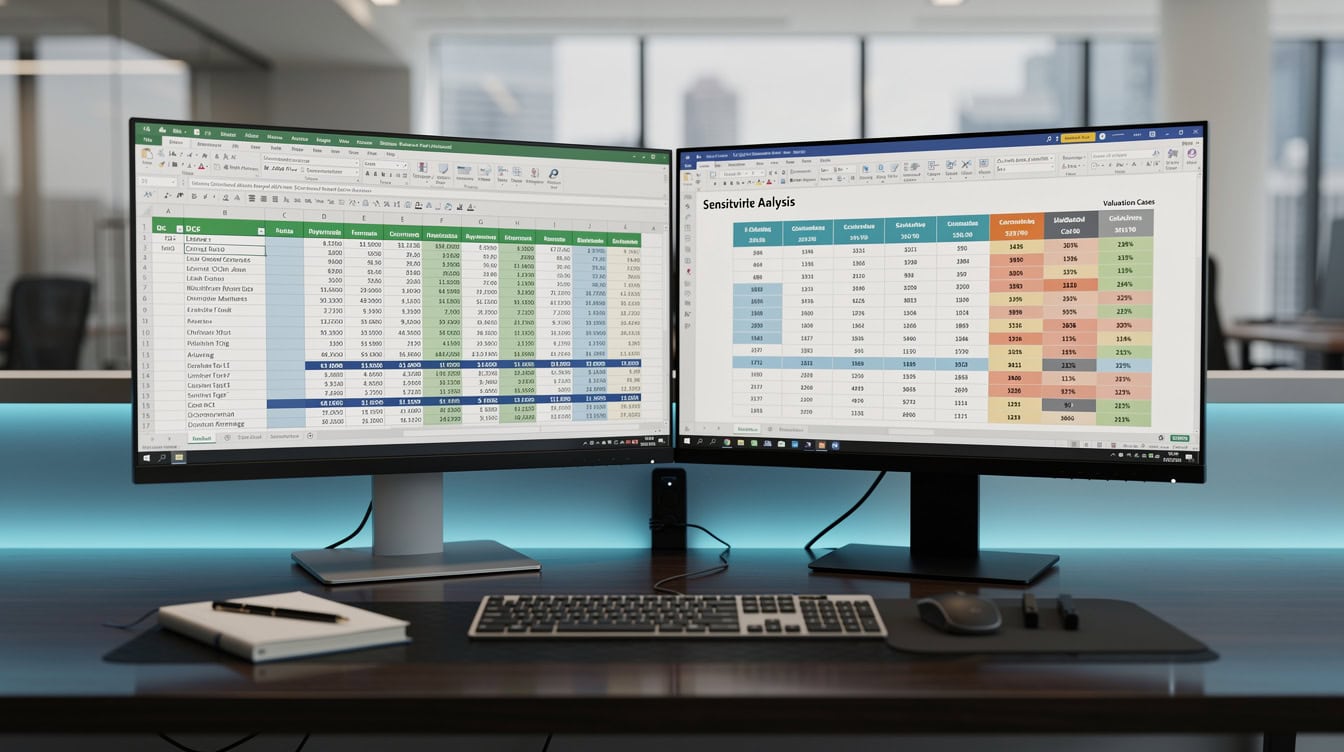
Color-coding input cells yellow and output cells blue is a financial modeling best practice that prevents accidental formula overwrites.
Building Your Interactive Break-Even Calculator in Excel: Step-by-Step
An interactive break-even calculator uses named input cells so that changing one number instantly recalculates every output. Here is how to build one from scratch in under 15 minutes.
Step 1: Set up the input block
In column A, label rows 2 through 4: “Fixed Costs (monthly)”, “Variable Cost per Unit”, “Price per Unit”. In column B, enter your numbers. These are your only manual-entry cells — color them light yellow to signal they are inputs.
Step 2: Build the output block
In column A, label rows 5 through 8: “Contribution Margin per Unit”, “Break-Even Units”, “Break-Even Revenue”, “Contribution Margin Ratio”. In column B, enter the formulas from the previous section. Color these cells light blue to signal they are outputs.
Step 3: Add a profit-at-volume row
In B10, enter an assumed sales volume (e.g., 500 units). In B11, enter the formula =B10*B5-B2 to calculateprofit or loss at that volume. This single row lets you instantly see whether a planned sales target clears break-even.
Step 4: Protect the formula cells
Select all output cells (B5:B8, B11), go to Format Cells, check “Locked”, then use Review > Protect Sheet. This prevents accidental formula deletion — a critical step before sharing the model with non-finance colleagues.
Step 5: Name your input cells
Select B2, go to the Name Box (top-left of Excel), and type “FixedCosts”. Repeat for B3 (“VarCost”) and B4 (“Price”). Named ranges make formulas readable: =FixedCosts/(Price-VarCost) is far easier to audit than =B2/(B4-B3).A single Excel workbook can contain up to 255 sheets.
This gives you ample room to separate your inputs, calculator, chart, and sensitivity tabs without hitting any structural limits.
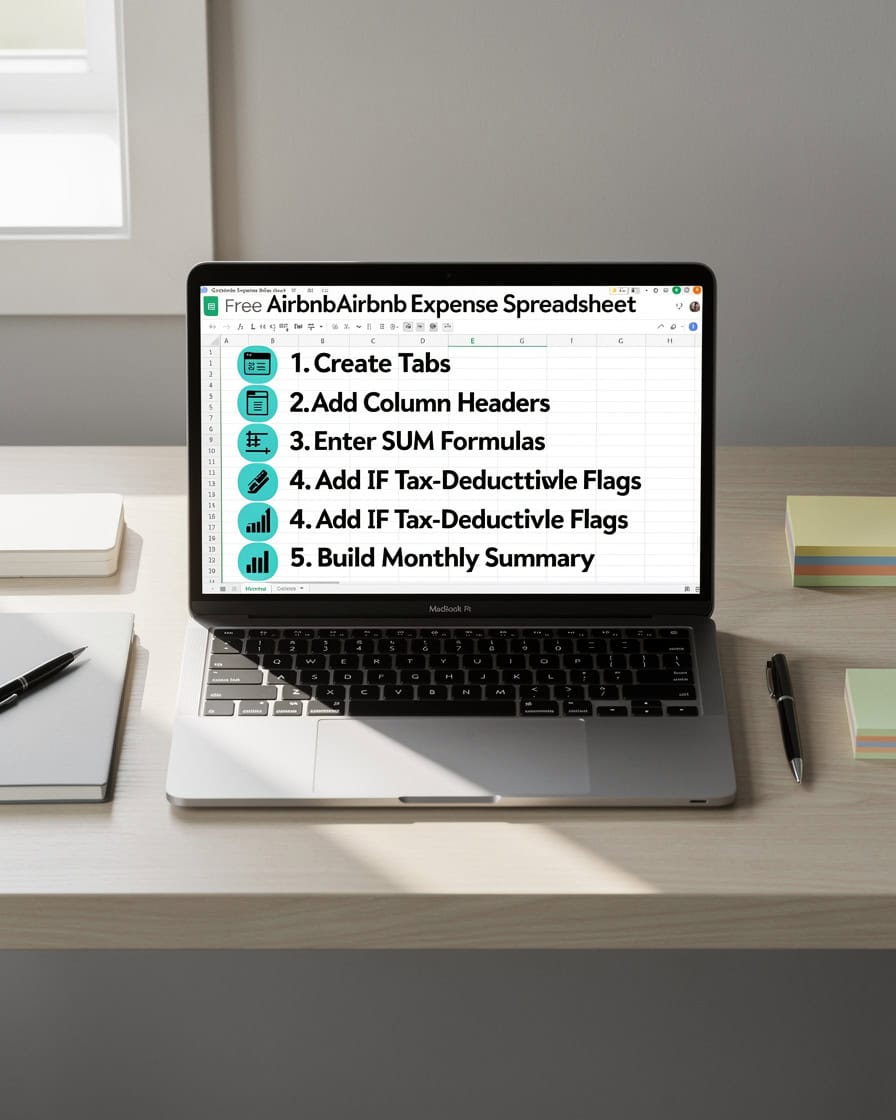
Following these 5 steps in sequence produces a model that any colleague can use without breaking formulas or misinterpreting inputs.
Worked Example 1: SaaS Business Break-Even Model
A SaaS business (software-as-a-service) sells monthly subscriptions and incurs high upfront fixed costs — engineering salaries, hosting infrastructure, and marketing — but very low variable costs per additional subscriber.
Inputs:
- Fixed costs (monthly): $42,000 (engineering team $28,000, hosting $6,000, marketing $8,000)
- Variable cost per subscriber: $4 (payment processing + incremental cloud compute)
- Monthly subscription price: $49
Calculations:
- Contribution margin per unit: $49 minus $4 = $45
- Break-even subscribers: $42,000 divided by $45 = 934 subscribers
- Break-even revenue: 934 multiplied by $49 = $45,766 per month
- Contribution margin ratio: $45 divided by $49 = 91.8%
This 91.8% contribution margin is consistent with industry benchmarks: SaaS businesses typically achieve contribution margins of 70-85% at scale, and early-stage products with minimal support costs can exceed 90%.
In Excel: =42000/(49-4) returns 933.3, which you round up to 934 (always round up — you cannot sell a fraction of a subscription).
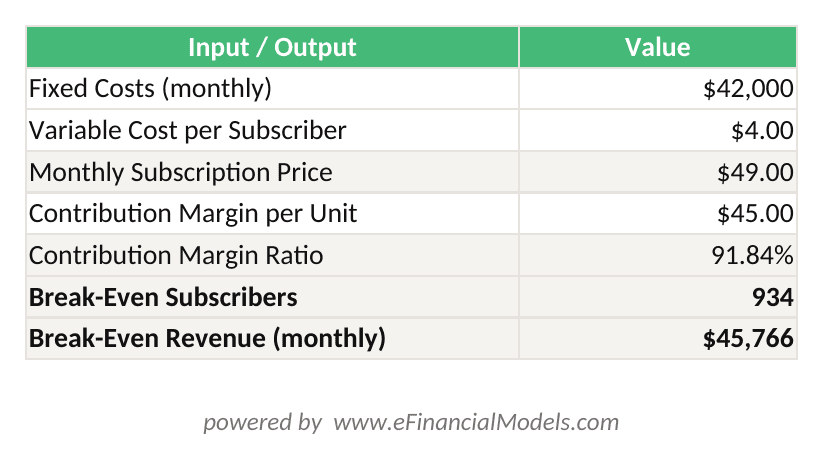
SaaS break-even: $42,000 fixed costs ÷ ($49 price − $4 variable cost) = 934 subscribers. Contribution margin ratio = 91.8%.
Worked Example 2: Manufacturing Firm Break-Even Analysis
A manufacturing firm producing a physical product faces a very different cost structure: materials, direct labor, and packaging all scale with volume, compressing the contribution margin.
Inputs:
- Fixed costs (monthly): $85,000 (factory lease $30,000, equipment depreciation $25,000, salaried staff $30,000)
- Variable cost per unit: $38 (materials $22, direct labor $12, packaging $4)
- Selling price per unit: $65
Calculations:
- Contribution margin per unit: $65 minus $38 = $27
- Break-even units: $85,000 divided by $27 = 3,149 units
- Break-even revenue: 3,149 multiplied by $65 = $204,685 per month
- Contribution margin ratio: $27 divided by $65 = 41.5%
This 41.5% contribution margin sits squarely within the 30-50% range typical for discrete manufacturing. The key insight: this firm needs to produce and sell 3,149 units every month before it earns a single dollar of profit — roughly 105 units per working day assuming a 30-day month.
In Excel: =85000/(65-38) returns 3148.1, rounded up to 3,149. To automate the rounding, use =CEILING(85000/(65-38),1), which always rounds up to the next whole integer.
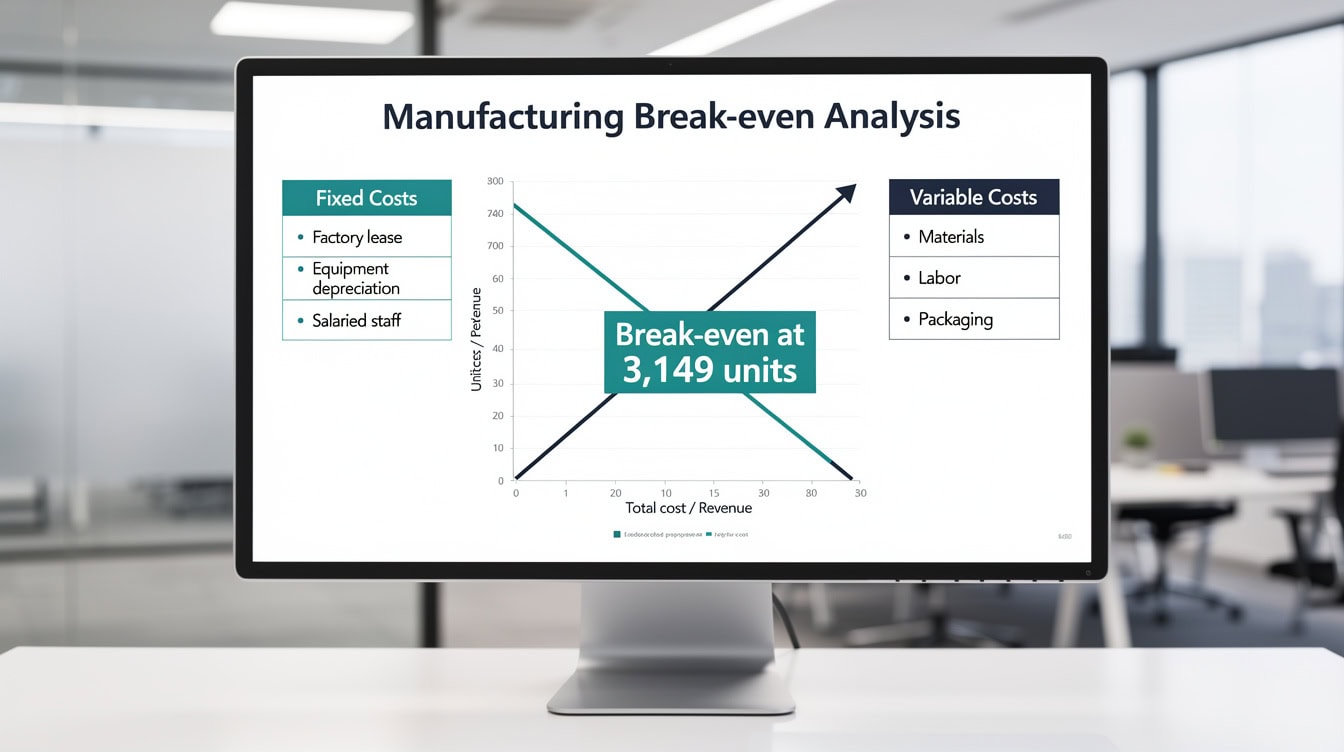
At 3,149 units per month, this manufacturing firm needs to ship roughly 105 units every working day before earning any profit.
Worked Example 3: Service Business Break-Even Calculation
A consulting firm bills clients by the project or by the hour. Variable costs are low (travel, software tools), but the firm must cover consultant salaries as a fixed cost if staff are salaried rather than contract.
Inputs:
- Fixed costs (monthly): $28,000 (3 salaried consultants at $8,000 each, plus $4,000 office and software)
- Variable cost per billable hour: $12 (travel, tools, admin support allocation)
- Billing rate per hour: $175
Calculations:
- Contribution margin per hour: $175 minus $12 = $163
- Break-even billable hours: $28,000 divided by $163 = 172 hours per month
- Break-even revenue: 172 multiplied by $175 = $30,100 per month
- Contribution margin ratio: $163 divided by $175 = 93.1%
With 3 consultants, 172 hours represents about 57 billable hours per consultant per month — well within a realistic utilization target of 60-70% of available working hours. This model shows the firm reaches break-even with significant capacity headroom, meaning incremental projects are almost pure profit.
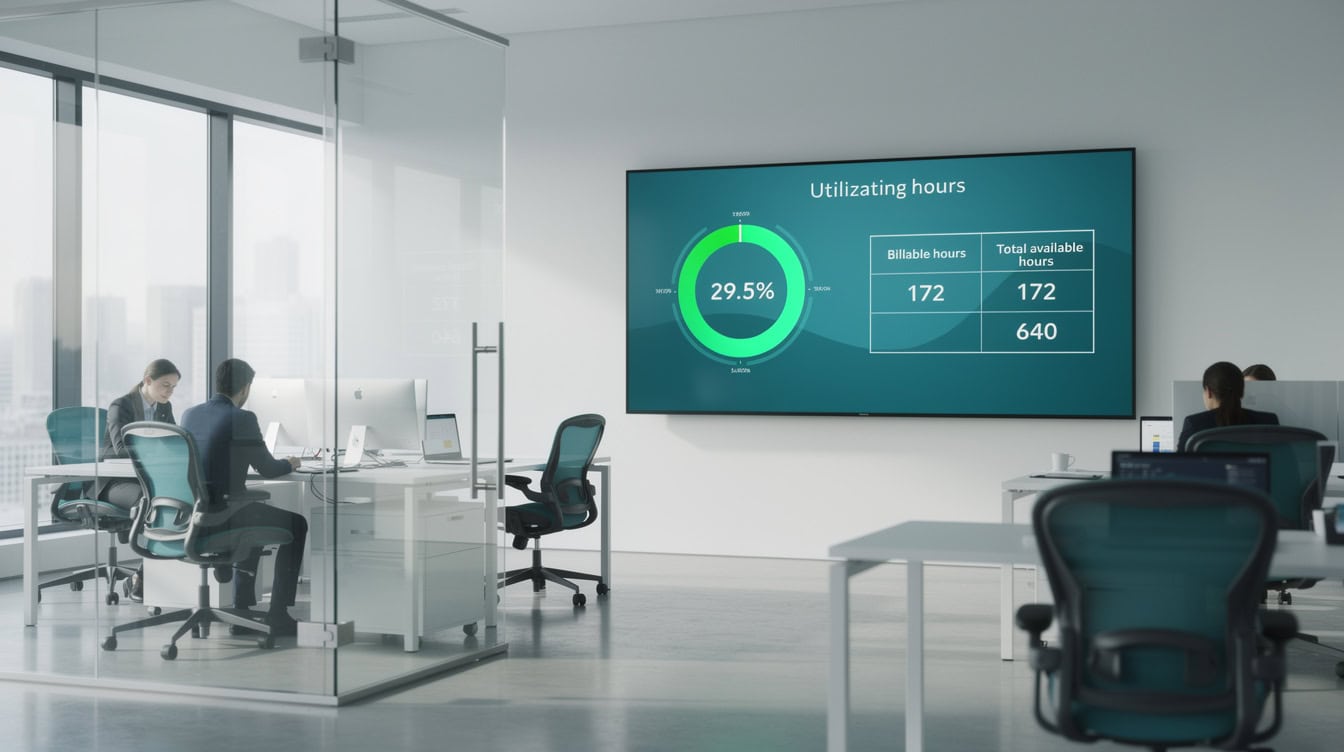
A 29.5% utilization rate to break even gives this consulting firm substantial headroom — every hour billed above 189 per month is nearly pure profit.
Creating a Visual Break-Even Chart in Excel
A break-even chart plots three lines against unit volume on the x-axis: fixed costs (a flat horizontal line), total costs (a rising line starting at the fixed cost intercept), and total revenue (a rising line starting at zero). The point where total costs and total revenue intersect is the break-even point.
Step-by-step chart construction:
- Create a data table with units in column A (e.g., 0, 200, 400, 600, 800, 1,000, 1,200). In column B, calculate Fixed Costs (constant value, e.g., =$B$2). In column C, calculate Total Costs (=$B$2+$B$3A2). In column D, calculate Total Revenue (=$B$4A2).
- Select columns A through D, go to Insert > Charts > Line Chart. Excel plots all three series automatically.
- Right-click the Fixed Costs series and select “Format Data Series” — change the line to dashed to distinguish it visually.
- Add axis titles: x-axis = “Units Sold”, y-axis = “Dollars ($)”. Add a chart title: “Break-Even Analysis”.
- Add a text box annotation at the intersection point labeling it “Break-Even Point: [X] units / $[Y] revenue”.
- Shade the area to the left of the intersection red (loss zone) and to the right green (profit zone) using Excel’s “Fill” options on a secondary area series.
The resulting chart gives any stakeholder — investor, board member, or operations manager — an instant visual read on how far the business is from profitability at any given volume.
The break-even chart makes the profit zone immediately visible to any stakeholder — no financial background required to read the key message.
Advanced Sensitivity Analysis: Excel Data Tables for What-If Scenarios
A single break-even number is useful. A sensitivity table showing how that number changes across 25 combinations of price and volume is far more powerful for decision-making.
Excel’s Data Table feature (a type of what-if analysis tool built into the Data tab) automates this. Here is how to build a two-variable sensitivity table for break-even units:
Step 1: In a new area of your sheet, create a grid. Put your break-even formula (=B2/(B4-B3)) in the top-left corner of the grid (e.g., cell G2).
Step 2: Along the top row of the grid (H2:L2), enter price scenarios: $45, $50, $55, $60, $65.
Step 3: Along the left column (G3:G7), enter variable cost scenarios: $30, $33, $36, $39, $42.
Step 4: Select the entire grid (G2:L7), go to Data > What-If Analysis > Data Table. Set “Row input cell” to B4 (Price) and “Column input cell” to B3 (Variable Cost). Click OK.
Excel fills all 25 cells instantly. Each cell shows the break-even unit count for that specific price-and-cost combination. You can layer in conditional formatting — red for break-even above your capacity limit, green for achievable targets — to make the risk zones immediately visible. A single Data Table can reference up to 32 input cells when used in advanced configurations.
For scenario analysis beyond two variables, Excel’s Scenario Manager (also under Data > What-If Analysis) lets you save named scenarios (“Base Case”, “Price War”, “Cost Reduction”) and switch between them with one click.
A 5×5 data table built with Excel’s What-If Analysis tool shows 25 break-even scenarios simultaneously — red cells flag combinations that exceed production capacity.
Common Break-Even Modeling Errors in Excel and How to Avoid Them
Break-even models fail in predictable ways. Here are the 5 most common errors and their fixes.
Error 1: Circular references in the BEP formula
This happens when a formula references its own output cell, causing Excel to loop indefinitely. Fix: ensure your break-even formula in B6 references only input cells (B2, B3, B4) and never references B6 itself or any cell that traces back to B6.
Error 2: Mixing fixed and variable costs in a single line
Salesperson salaries are often partly fixed (base pay) and partly variable (commission). Lumping them into one category distorts both the contribution margin and the break-even point. Fix: split every cost line into its fixed and variable components before building the model.
Error 3: Ignoring capacity constraints
A model might calculate a break-even of 5,000 units, but if your factory can only produce 3,500 units per month, that break-even is physically unreachable at current capacity. Fix: add a “Maximum Capacity” input cell and a conditional formula that flags when break-even exceeds capacity: =IF(B6>MaxCapacity,”EXCEEDS CAPACITY”,”Achievable”).
Error 4: Using average variable cost instead of marginal variable cost
As volume increases, bulk purchasing often reduces per-unit material costs. Using a single average overstates variable costs at high volumes and understates them at low volumes. Fix: build a stepped variable cost table that adjusts per-unit cost at defined volume thresholds.
Error 5: Treating break-even as a profitability guarantee
Break-even analysis assumes linear cost and revenue relationships and ignores market demand curves. A business can reach its break-even unit count and still fail if it cannot sell those units at the modeled price. Pair your break-even model with a cash flow analysis to capture timing differences between when costs are incurred and when revenue is collected.
Circular references and mixed cost classification are the two errors most likely to overstate profitability — both are invisible without formula auditing.
Download Your Break-Even Analysis Excel Template
A pre-built template eliminates setup time and ensures formula integrity from the start. The EFM Break-Even Analysis template includes the following structure:
| Tab | Contents | Key Outputs |
|---|---|---|
| Inputs | Fixed costs, variable costs, price | Editable yellow cells only |
| Calculator | BEP formulas, contribution margin | Units, revenue, CM ratio |
| Chart | Auto-updating break-even chart | Visual profit/loss zones |
| Sensitivity | 2-variable data table | 25-cell price/cost grid |
| Scenarios | 3 named scenarios | Base, optimistic, pessimistic |
The template uses named ranges throughout, so every formula reads in plain English. Input validation rules prevent negative prices and zero variable costs — two entries that would produce nonsensical results. The chart tab auto-updates whenever any input cell changes, making it suitable for live presentations.
For businesses with more complex cost structures, industry-specific variants for SaaS, retail, and manufacturing are available, each pre-loaded with realistic cost benchmarks.
If you need to extend the model into multi-period revenue projections, the template includes a monthly timeline tab that tracks cumulative profit from month 1 onward, showing exactly when the business crosses into sustained profitability.
The five-tab template structure separates inputs from outputs and charts from calculations, making the model auditable and presentation-ready.
Frequently Asked Questions
What is the exact Excel formula for break-even units?
The formula is =FixedCosts/(Price-VarCost), where FixedCosts, Price, and VarCost are named input cells. Using cell references directly, it reads =B2/(B4-B3) if fixed costs are in B2, variable cost per unit in B3, and price per unit in B4. Always round the result up using =CEILING(B2/(B4-B3),1) because you cannot sell a fractional unit. For example, if fixed costs are $50,000, variable cost is $20 per unit, and price is $45 per unit, the formula returns =50000/(45-20) = 2,000 units exactly. If the result were 2,000.3, you would round up to 2,001 to ensure full cost coverage.
How do I build a break-even sensitivity table in Excel?
Use Excel’s built-in Data Table feature under Data > What-If Analysis > Data Table. Set up a grid with price scenarios across the top row and variable cost scenarios down the left column. Place your break-even formula in the top-left corner of the grid. Select the entire grid, open Data Table, assign the row input cell to your price cell and the column input cell to your variable cost cell, then click OK. Excel populates all cells instantly. A 5×5 grid covering prices from $45 to $65 and variable costs from $20 to $40 gives you 25 break-even scenarios in seconds, far faster than recalculating manually. Apply conditional formatting to highlight cells where break-even exceeds your production capacity.
What is contribution margin and why does it matter for break-even?
Contribution margin (CM) is the amount each unit sale contributes toward covering fixed costs after variable costs are subtracted. The formula is: CM per unit = Price minus Variable Cost per Unit. The higher the contribution margin, the fewer units you need to sell to break even. For example, a SaaS product priced at $99 with $5 in variable costs has a CM of $94 per unit. With $47,000 in monthly fixed costs, break-even is just 500 subscribers. If variable costs rise to $25 (perhaps due to higher payment processing fees), CM drops to $74 and break-even rises to 635 subscribers — a 27% increase in required volume from a $20 cost increase. This is why tracking contribution margin separately from gross margin is essential for pricing decisions.
How do I create a break-even chart in Excel that shows profit and loss zones?
Build a data table with units in column A (from 0 to 150% of your expected break-even), fixed costs in column B (constant value), total costs in column C (fixed costs plus variable cost per unit multiplied by units), and total revenue in column D (price multiplied by units). Select all four columns and insert a Line Chart. Format the fixed cost line as dashed. Add axis labels: x-axis as “Units Sold” and y-axis as “Dollars”. The intersection of the total cost and total revenue lines is your break-even point. Add a data label at that intersection showing the unit count and revenue figure. To shade profit and loss zones, add a secondary area series or use a text box with a colored background placed in each zone. Excel 2016 and later versions support all these formatting options natively without add-ins.
Can break-even analysis work for a service business with no physical units?
Yes. For service businesses, replace “units” with billable hours, projects, or clients. The formula structure is identical: Fixed Costs divided by (Billing Rate minus Variable Cost per Hour). For a consulting firm with $35,000 in monthly fixed costs, a $200 per hour billing rate, and $15 in variable costs per hour (travel, tools), break-even is=35000/(200-15) = 189 billable hours per month. If the firm has 4 consultants each available for 160 hours per month (640 total hours), 189 hours represents a 29.5% utilization rate — a very achievable target. This framing makes break-even immediately actionable for service business owners who think in terms of utilization and capacity rather than unit production.
What are the biggest limitations of break-even analysis I should disclose to investors?
Break-even analysis assumes linear cost and revenue relationships, meaning it treats variable cost per unit as constant regardless of volume. In reality, bulk purchasing reduces material costs at high volumes, and price discounts reduce revenue per unit as you push into new customer segments. The model also ignores the time value of money — a business that breaks even in month 18 has consumed 18 months of cash runway to get there, which a static break-even number does not capture. Pair your break-even model with a cash flow analysis to show investors both the profitability threshold and the cash required to reach it. According to research from the Federal Reserve’s Small Business Credit Survey, 43% of small businesses applied for financing specifically to cover operating expenses while scaling toward profitability, underscoring that break-even timing and cash timing are two distinct problems.
How often should I update my break-even model?
Update your break-even model whenever any of three inputs change: fixed costs, variable costs per unit, or selling price. In practice, this means reviewing the model monthly for early-stage businesses (where costs shift frequently) and quarterly for established businesses. Set a calendar reminder to reconcile your model inputs against your actual income statement each month. If your actual variable cost per unit is running 10% above the modeled figure, your real break-even point is higher than your model shows — and you need to know that before your next pricing or hiring decision. The EFM template includes a “Variance” tab that compares modeled inputs against actuals, flagging discrepancies automatically using conditional formatting.
Conclusion
Break-even analysis in Excel is not a one-time calculation — it is a living model that should update every time your cost structure or pricing changes. The formula is simple: Fixed Costs divided by (Price minus Variable Cost per Unit). The power comes from building that formula into an interactive calculator with a visual chart and a sensitivity table that shows 25 scenarios at once.
The three worked examples here — SaaS at 934 subscribers, manufacturing at 3,149 units, and consulting at 172 billable hours — demonstrate how the same formula produces radically different strategic implications depending on your business model. Understanding those implications before you set prices or hire staff is what separates businesses that plan from businesses that react.
I recommend downloading the EFM Break-Even Analysis Excel Template to get a pre-built calculator with sensitivity tables, a visual chart, and scenario toggles — ready to customize with your own numbers in under 5 minutes.