
0 ITEMS

Renewable Development Pipeline Acquisition | Risk-Adjusted MW & Safe Harbor Underwriting
Converts a seller’s nameplate megawatts into risk-adjusted delivered megawatts through four steps that sum exactly, prices the 4 July 2026 safe-harbor split project by project (separating solar from storage inside the same hybrid), sizes the real cash cost of nine interconnection markets, and values milestone consideration at the odds of reaching each milestone. Validated against LBNL’s published completion rates on its own sheet. 15 sheets, Excel + Google Sheets.
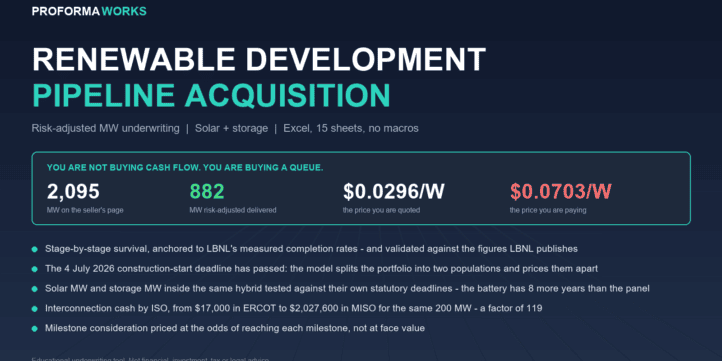


You are not buying cash flow. You are buying a queue.
Every renewable template on the market forecasts one project for the developer who is building it. This one underwrites the purchase of a PIPELINE: a portfolio of solar and storage projects at different stages, in different markets, with different tax positions, and different odds of ever being built.
A seller hands you a page with a megawatt number and a price per watt. Both are true. Neither is the number to underwrite on, because between the megawatts on the page and the megawatts you will own sit four filters, and every one of them has been measured. Of interconnection requests filed in the United States between 2000 and 2020, about 19% of projects and 13% of capacity had reached commercial operation by the end of 2025. For solar alone, 10.9% of capacity. Signing the interconnection agreement does not end that risk, it halves it: 41% of the capacity that signed agreements between 2000 and 2022 had withdrawn by the end of 2025. And the median clock from request to operation is 61 months, against 22 in 2008. (Lawrence Berkeley National Laboratory, Queued Up: 2026 Edition.)
THE SIGNATURE OUTPUT IS A BRIDGE, AND IT IS AN IDENTITY RATHER THAN AN ESTIMATE
Nominal megawatts, less queue attrition, less site and local risk, less capacity slipping past your horizon, equals risk-adjusted megawatts delivered. The four steps sum to the nominal exactly, and it is checked project by project rather than in aggregate, because an aggregate identity can hide two errors cancelling each other. Set the risks to zero and the price per delivered watt collapses onto the price per nominal watt, which proves the gap is those four steps and nothing else.
THE TAX DEADLINE HAS ALREADY PASSED, AND IT SPLITS THE PORTFOLIO IN TWO
Under 26 U.S.C. 45Y(d)(4)(A) as amended by Public Law 119-21, a wind or solar facility loses the clean electricity credits if placed in service after 31 December 2027, unless construction began on or before 4 July 2026. That date is behind us. The model prices the two populations apart, project by project, and separates SOLAR megawatts from STORAGE megawatts inside the same hybrid, because storage is not an “applicable facility” and has no 2027 cliff at all: the battery has roughly eight more years of tax runway than the panel beside it.
THE QUEUE IS NINE MARKETS, NOT ONE
Cash required at the interconnection request runs from $17,000 in ERCOT to $2,027,600 in MISO for the same 200 MW project, a factor of 119, reproduced in the model from each tariff’s fixed and per-megawatt schedule. Conditional completion runs from 36.6% in ERCOT to 13.5% in CAISO. Commercial readiness deposits are cumulative, not additive, and adding them overstates the cash requirement by about 1.75 times. And the network upgrade cost is not a number but a distribution that is explicitly not normal: in PJM, 30% of completed projects came in under $5/kW, 95% under $200/kW, and one came in at $3,728/kW.
THE BUYER DOES NOT PAY A PRICE, IT PAYS A FUNCTION OF THE OUTCOME
Signing, closing, permits, interconnection agreement, full notice to proceed, commercial operation: each tranche priced at the probability of reaching it, plus an earnout per delivered megawatt. In real contracts filed with the SEC, cash at signing has been 0%, 3.9% and 4.86% of total consideration.
VALIDATION YOU CAN CHECK RATHER THAN TRUST
A cross-check against our own re-implementation cannot see a shared conceptual error. A published example can. So the survival arithmetic is run, on a dedicated sheet, against Lawrence Berkeley National Laboratory’s own published figures, and reproduces the percentages the laboratory prints, from the laboratory’s inputs. Seventeen logic proofs compute live from your inputs. Sixteen must pass. One is designed to fail, and its failure is the lesson: the published median durations from request to agreement (45 months) and agreement to operation (31 months) sum to 76, against a directly measured median of 61. Three different samples. A model that adds them is wrong by fifteen months.
WHAT IT REFUSES TO TELL YOU
- A standard probability of success by development stage. No standard exists, and the most cited source on pipeline diligence says so itself. Only two of the six stage probabilities are anchored to a measurement; the other four are conventions, labelled as conventions in the cell.
- A market price per watt for pipeline. The market says of itself that there is not a value mark. The reference points are cited one by one with the caveat that belongs to each, including that in one bankruptcy auction built megawatts fetched $0.292-0.590/W while a shovel-ready project fetched $0.069/W.
- Whether a project validly began construction. That is a tax position resting on guidance a federal court vacated in June 2026, with no appeal, stay or replacement we could confirm. You get a three-state switch and the answer under each state.
- A development hurdle rate. None is published. What is published measures unlevered PROJECT returns on built assets, which is a different thing.
A DEFAULT DEAL THAT IS DELIBERATELY MARGINAL
It lands somewhere instructive: the margin per delivered watt is POSITIVE and the internal rate of return is BELOW the hurdle. The deal makes money and is still not worth doing, because a pipeline pays out years after it is bought. That is the most common way a pipeline acquisition goes wrong on a spreadsheet containing no errors at all.
Fifteen sheets, 828 formulas. Excel and Google Sheets, no macros, no external links, no iterative calculation. Includes a 10-page user guide with every source named in full. A free PDF demo is available above.
Educational underwriting tool. Not financial, investment, tax or legal advice. It does not predict interconnection outcomes, permitting outcomes, tax positions or market prices, and it does not tell you what a development pipeline is worth.
Similar ProductsOther customers were also interested in...



 eFinancialModels
Electric Vehicle (EV) Charging Station Financial M...
With this comprehensive 5- or 10-year monthly tool, investors can assess the viability of setting up... Read more

Financial Model for Mobile App | Mobile App Busine...
The Mobile App Financial Plan Template in Excel allows you to develop financial projections when lau... Read more

 HenrySheykin
Food Truck Financial Model Excel Template
The Food Truck Financial Model helps entrepreneurs, founders, business owners, consultants, and anal... Read more

Green Hydrogen Production from Wind Energy Financi...
The Green Hydrogen from Wind Financial Model aims to comprehensively forecast a horizon of 40 years ... Read more

Simple Mutual Non-Disclosure Agreement Template
Protect your business secrets with ease using our Simple Mutual Non-Disclosure Agreement Template. S... Read more

Solar Energy Financial Model
The Solar Energy Financial Model Spreadsheet Template in Excel assists you in preparing a sophistica... Read more

 Peter Graf
The Customer-Centric Financial Model for Restauran...
Starting a restaurant without a financial plan is like driving a car blindfolded. You wouldn´t do i... Read more
You must log in to submit a review.