
0 ITEMS

Supermarket Financial Model Excel Template
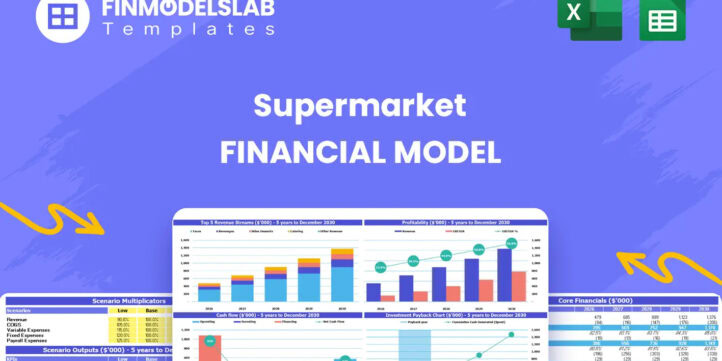
The Supermarket Financial Model helps entrepreneurs, grocery store owners, consultants, analysts, and business planners turn a supermarket concept into a structured financial forecast. Instead of starting from a blank spreadsheet, users can work from a ready-to-use financial model template designed around the economics of a retail grocery business. It helps organize the core assumptions behind sales volume, customer traffic, conversion rates, product categories, operating expenses, payroll, startup costs, cash flow, profitability, and funding requirements, giving users a clearer view of what it may take to launch, operate, or expand a supermarket. This template is built for practical financial planning and decision-making. Users can estimate revenue assumptions across supermarket product categories such as fresh produce, packaged goods, dairy, meat, seafood, prepared foods, bakery items, household essentials, and general merchandise. The model connects these revenue drivers with cost of goods sold, staffing needs, rent, utilities, marketing, technology, inventory, and other operating expenses, helping users understand whether the business can support its cost structure and reach sustainable profitability over time. The Supermarket Financial Model is also useful for preparing business plans, investor presentations, bank loan applications, internal budgets, and expansion reviews. It includes structured outputs such as a dashboard, scenario analysis, professional charts, financial reports, revenue breakdowns, KPI tracking, return metrics, and break-even analysis. These sections help users evaluate multiple outcomes, compare assumptions, identify funding gaps, and present their numbers in a format that is easier for lenders, investors, partners, and stakeholders to review. Because the template is fully editable, users can customize the assumptions to match a specific store size, local market, pricing strategy, product mix, supplier structure, staffing plan, and growth timeline. Whether you are opening a new supermarket, improving an existing grocery store forecast, testing a funding requirement, or building a financial plan for a retail food business, this model provides a time-saving framework for understanding revenue potential, cash flow pressure, profitability milestones, and the financial decisions that matter most.


Financial Model Overview
The Supermarket Financial Model is a ready-to-use financial model template built to help users plan, evaluate, and present the financial performance of a supermarket or grocery store business. A supermarket is a high-volume, inventory-driven operation with many moving parts, including customer traffic, product category sales, supplier costs, staffing, rent, utilities, equipment, shrinkage, working capital, and ongoing cash requirements. This template brings those elements into one structured model so entrepreneurs, business owners, consultants, analysts, founders, and people preparing business plans or funding documents can replace guesswork with a more organized forecasting process. Users can customize the assumptions, review five-year financial projections, evaluate profitability, estimate funding needs, and prepare cleaner outputs for decision-making, lender discussions, investor presentations, or internal planning.
All-in-One Dashboard
The all-in-one dashboard gives users a central view of the supermarket’s core inputs and core outputs. It is designed to make the model easier to navigate by bringing key assumptions and financial results into one practical summary area. Users can review major drivers such as customer traffic, conversion rate, average order behavior, revenue growth, gross margin, operating costs, cash flow, EBITDA, net profit, and payback indicators without having to search across multiple tabs. For a supermarket business, this is especially useful because small changes in store visitors, basket size, product pricing, or cost of goods sold can materially affect financial performance. The dashboard helps users quickly understand how assumptions flow into the forecast, making it easier to communicate the business case to partners, lenders, investors, or internal stakeholders. It also supports faster decision-making by showing whether the current plan is trending toward profitability, whether cash pressure is building, and which assumptions may need adjustment before launch or expansion.
Low, Base, and High Scenario Analysis
The low, base, and high scenario analysis section helps users test different possible outcomes for the supermarket business. Instead of relying on only one forecast, users can compare how the model performs under conservative, expected, and optimistic assumptions. Inputs may include daily store visitors, visitor-to-buyer conversion rates, average units per order, average price per unit, gross margin, operating expenses, payroll levels, and customer adoption speed. The outputs help show how revenue, EBITDA, net income, cash flow, funding needs, and payback timing change under each scenario. This is valuable because supermarket performance can vary significantly depending on location, local competition, pricing strategy, supplier terms, marketing effectiveness, and customer loyalty. A low scenario can highlight downside risk and working capital pressure, while a high scenario can show the upside potential if customer demand grows faster or margins improve. For business planning and funding conversations, scenario analysis makes the forecast more credible by showing that the user has considered uncertainty rather than presenting a single fixed projection.
Professional Charts and Visual Reports
The professional charts and visual reports section converts complex financial outputs into easy-to-read visuals that can be used for presentations, internal reviews, business plans, and stakeholder updates. A supermarket model can contain many detailed calculations, but decision-makers often need a clear visual summary of revenue growth, gross profit, operating expenses, EBITDA, net income, cash flow, and key performance trends. This component helps users communicate the story behind the numbers more effectively. Inputs are drawn from the model’s assumptions and financial statements, while outputs may include line charts, bar charts, margin trends, cash balance movement, revenue mix charts, and profitability visuals. These reports are useful when preparing investor or lender materials because they make it easier to explain where the business starts, how it grows, when losses narrow, and when profitability begins. For owners and managers, the charts also support practical decision-making by highlighting trends that may not be obvious in raw spreadsheet rows, such as rising expense pressure, margin improvement, or seasonal cash flow strain.
ROE Components and DuPont Analysis
The ROE components and DuPont analysis section helps users understand the drivers behind return on equity rather than only looking at a single return percentage. For a capital-intensive supermarket business, return on equity can be influenced by profit margins, asset turnover, and financial leverage. This component breaks ROE into its underlying parts so users can see whether returns are being driven by stronger profitability, more efficient use of assets, or financing structure. Inputs may include net income, total revenue, total assets, equity, debt, and balance sheet assumptions. The outputs help show how margin performance, operating efficiency, and capital structure interact over the forecast period. This is particularly useful for investors, lenders, and owners who want to evaluate whether the supermarket is creating attractive returns relative to the amount of capital required. It also gives management a more diagnostic view of performance. If ROE is weak, the model can help identify whether the issue is low net margin, slow sales relative to asset investment, high startup costs, or an equity structure that does not support the expected growth plan.
Revenue Inputs
The revenue inputs section is where users define the commercial assumptions that drive supermarket sales. A grocery business depends on a combination of store traffic, buyer conversion, repeat customer behavior, average units per order, and pricing across multiple product categories. This section may include assumptions for daily visitors, conversion rate, order volume, repeat purchase behavior, product mix, average price per unit, and category-level sales assumptions for fresh produce, pantry staples, packaged goods, dairy, meat, seafood, prepared foods, bakery items, household necessities, and general merchandise. These inputs feed directly into the revenue forecast and help users build a sales plan that reflects the way a supermarket actually generates income. The section is useful because it connects operational assumptions with financial outcomes. Rather than entering a single revenue number without support, users can model the specific drivers behind sales growth and test how changes in foot traffic, pricing, basket size, and product mix affect total revenue, gross profit, and cash flow.
Bank-Ready Financial Reports
The bank-ready financial reports section gives users structured financial outputs that can support loan applications, funding discussions, and formal business planning. Lenders typically want to review a clear income statement, cash flow forecast, balance sheet, profitability metrics, repayment capacity, and assumptions behind the forecast. This component organizes those outputs in a professional format so users can present the supermarket’s expected financial performance in a more credible way. Inputs come from the revenue assumptions, cost of goods sold, payroll plan, operating expenses, startup investment, financing assumptions, and working capital needs. Outputs may include projected profit and loss statements, cash flow statements, balance sheets, EBITDA, net income, cash balance, and debt-related metrics. For a supermarket, this is especially important because initial capital needs can be substantial due to refrigeration, shelving, store build-out, POS systems, inventory, deposits, and working capital. The bank-ready reports help show whether the business can cover operating costs, manage cash flow, and support financing obligations over time.
Revenue Breakdown
The revenue breakdown section gives users a more detailed view of how total supermarket revenue is built across different sales streams and product categories. Instead of treating revenue as one broad figure, the model can separate income from fresh produce, pantry staples, packaged goods, dairy, meat, seafood, prepared foods, bakery items, household essentials, and general merchandise. This structure helps users understand which categories contribute the most to sales, which may carry higher margins, and where strategic focus may be needed. Inputs may include category pricing, sales volume, units per order, product mix percentages, and category growth assumptions. Outputs can show revenue by stream, share of total sales, growth by category, and the effect of product mix on overall performance. This is useful for planning inventory, supplier relationships, promotions, store layout, and margin strategy. For example, prepared foods may offer higher margins but require labor and equipment, while staple goods may generate frequent traffic but lower margins. A detailed revenue breakdown gives decision-makers a clearer picture of how the supermarket can grow sales while managing profitability.
KPI Dashboard and Benchmark Metrics
The KPI dashboard and benchmark metrics section helps users monitor the supermarket’s performance through practical indicators that go beyond basic revenue and profit. Key performance indicators may include gross margin, EBITDA margin, net profit margin, average order value, daily visitors, conversion rate, repeat customer behavior, cash balance, burn rate, payback period, return on equity, and revenue per customer. Benchmark-style metrics help users compare projected performance against industry expectations or internal targets, making the forecast easier to evaluate. Inputs are drawn from the model’s sales, cost, staffing, balance sheet, and cash flow assumptions, while outputs provide a concise view of operational and financial health. This component is useful for both startup planning and ongoing management because supermarket owners need to track whether traffic is converting into purchases, whether product margins are strong enough, whether operating expenses are controlled, and whether cash flow is sustainable. It also helps users prepare more persuasive funding materials by showing lenders and investors that the business plan is supported by measurable performance indicators.
Startup Costs and Launch Investment
The startup costs and launch investment section helps users estimate the upfront capital required to open or prepare the supermarket for operations. Supermarkets often require significant investment before revenue begins, including refrigeration and display cases, shelving, store fixtures, flooring, interior design, lighting, HVAC upgrades, POS systems, security equipment, permits, legal fees, initial marketing, deposits, opening inventory, and working capital reserves. This component allows users to itemize these costs, adjust them based on store size and location, and calculate the total funding required before launch. Outputs may include a startup cost summary, capital expenditure schedule, pre-opening expense estimate, initial inventory requirement, and total cash need. This section is useful because underestimating startup costs is one of the most common risks in retail planning. By organizing launch expenses in one place, the model helps users prepare more realistic funding requests, avoid early cash shortages, and understand the financial commitment needed before the supermarket can begin generating sales.
Break-Even Analysis
The break-even analysis section helps users identify when the supermarket may reach the point where revenue is sufficient to cover its costs. This component considers the relationship between sales volume, gross margin, fixed costs, payroll, operating expenses, and profitability. Inputs may include projected revenue, cost of goods sold, labor costs, rent, utilities, marketing, insurance, administrative expenses, and other recurring costs. Outputs can show the break-even month, required revenue level, cumulative profit position, and how changes in assumptions affect the timing of profitability. For a supermarket business, break-even timing is important because the early years may require heavy investment in customer acquisition, inventory, staffing, and operating capacity before the store reaches stable sales volume. This section helps users understand how much revenue must be generated to cover the cost structure and what operational levers can accelerate profitability. It is also valuable for funding discussions because lenders and investors often want to know when the business is expected to stop relying on external capital and begin supporting itself through operating cash flow.
File types:
Excel – Single-User: .xlsx
Excel – Multi-User: .xlsx
Similar ProductsOther customers were also interested in...

 HenrySheykin
Grocery Store Financial Model Excel Template
The Grocery Store Financial Model helps entrepreneurs, founders, consultants, analysts, and retail b... Read more
Coffee Shop Financial Model Excel Template
The Coffee Shop Financial Model helps entrepreneurs, founders, business owners, consultants, and ana... Read more
Online Clothing Store Financial Model Excel Templa...
The Online Clothing Store Financial Model helps founders, entrepreneurs, business owners, consultant... Read more
Spa Financial Model Excel Template
The Spa Financial Model helps entrepreneurs, spa owners, consultants, analysts, and business planner... Read more
Bar Financial Model Excel Template
The Bar Financial Model Financial Model Template helps entrepreneurs, bar owners, consultants, analy... Read more
Bakery Financial Model Excel Template
The Bakery Financial Model helps entrepreneurs, bakery owners, consultants, analysts, and business p... Read more
Pizzeria Financial Model Excel Template
The Pizza Restaurant Financial Model Template helps entrepreneurs, restaurant owners, consultants, a... Read more
Clothing Store Financial Model Excel Template
The Clothing Store Financial Model helps turn a retail apparel concept into a structured financial f... Read more
Bike Shop Financial Model Excel Template
The Bicycle Shop Financial Model helps entrepreneurs, business owners, consultants, analysts, and fo... Read more
Car Wash Service Financial Model Excel Template
The Car Wash Financial Model is a ready-to-use financial model template designed to help entrepreneu... Read more
You must log in to submit a review.