
0 ITEMS

France Luxury Hotels: 33 Palaces, €9.6B Invested in 2025
France is Europe’s most valuable luxury-lodging market, and the numbers from 2025 make the investment case hard to ignore.
Key Takeaways
- France attracted €9.6 billion of the roughly €14.7 billion invested in European hotels in 2025, roughly two-thirds of the continent’s total.
- Paris delivered record RevPAR in 2025, with first-half RevPAR up 7.7% on a 4.4% ADR gain and a 2.2-point occupancy increase.
- The Atout France Palace distinction grew from 16 certified hotels in 2015 to 33 for 2026, yet genuine ultra-luxury room supply remains tightly constrained.
- Branded residences command a 33% price premium over unbranded stock globally, rising to 39% in resort markets such as the Côte d’Azur.
- Prime Paris hotel yields stabilized at 4.75% to 5.25% in H2 2025; trophy assets trade below 4.75% as family offices accept compressed yields for irreplaceable assets.
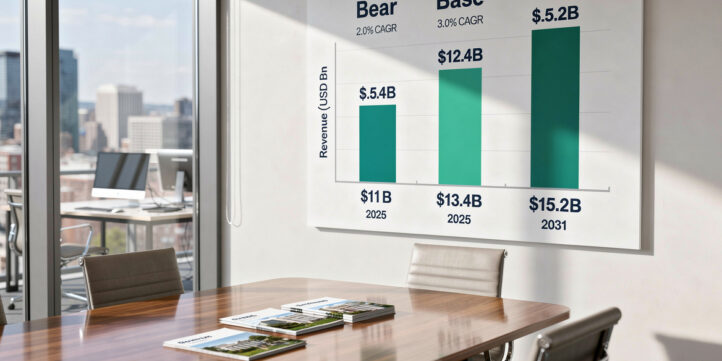
- The Base Case (50% probability) projects luxury RevPAR CAGR of 3.2% through 2031; the Bull Case (25%) projects 5.5% on sustained ultra-wealthy demand and a weak euro.
- The Loi Le Meur (Law 2024-1039, in force late 2024) tightens short-term-rental rules, channeling demand toward professionally managed, brand-grade product.
Why France Leads European Luxury Hospitality
France is the world’s most-visited country, and its luxury segment captures a disproportionate share of global high-net-worth travel spend. France recorded 102 million international visitors and €77.5 billion in tourism receipts in 2025, up about 9% year over year (DGE / France Tourism, 2025), with a stated national ambition to reach €100 billion in receipts by 2030 through higher-value rather than higher-volume tourism.
The demand is concentrated at the top: international ultra-high-net-worth (UHNW) travelers, meaning individuals with investable assets above $30 million, gravitate overwhelmingly to Paris and the Côte d’Azur. These two markets operate differently and should be modeled separately. Paris is a year-round, rate-led city market driven by business, leisure, cultural, and event travel. The Côte d’Azur is an intensely seasonal resort market whose annual financial result is made in roughly 100 summer days, anchored by the Cannes Film Festival, the Monaco Grand Prix, and the yachting season.
The structural story in both markets is scarcity. The best addresses are already occupied, heritage and planning rules constrain new build and conversion, and the capital cost of creating or restoring a palace runs to seven figures per key. That scarcity is the primary reason average rate, not occupancy, drives the cycle.
Paris: The Rate Engine
Paris is where the pricing power of French luxury is most visible. The city closed December 2025 with citywide occupancy of 76.7%, an ADR of €371.87, and RevPAR of €285.13, according to CoStar/STR data cited in the France Luxury Hospitality Market Study 2026–2031. The palace tier, meaning the 33 hotels holding the Atout France Palace distinction (a state certification above five-star, awarded for a three-year term), prints multiples of those citywide numbers. New Year’s Eve citywide ADR exceeded €580, and palace peak rates run well into four figures.
The 2026 Palace reassessment renewed 27 hotels, added 6, and removed 3, a reminder that the distinction is earned and revocable. For investors, the Palace distinction is a financeable scarcity signal: it supports ADR, branded-residence pricing, and exit liquidity. Losing it is a tail risk that belongs in every underwriting model.
The pipeline adds a small number of high-conviction projects. The Banke Opéra is scheduled to reopen under the Radisson Collection label in Q3 2026, and the Maybourne Saint-Germain is expected to bring super-luxury hospitality to the Left Bank in 2027. Each addition is a discrete, financeable event that can move the competitive set in a single arrondissement.
Côte d’Azur: The Scarcity Engine
The Riviera underwrites differently from Paris. Luxury hotels on the Côte d’Azur averaged about 72% occupancy in 2025, with RevPAR up roughly 5.4%, but peak-season occupancy at the great palaces approaches 85% to 93% and July–August ADRs run several times the shoulder-season rate (eFinancialModels Research, based on regional tourism data). The annual result is made in a handful of months, which means a soft summer cannot be recovered later in the year. That concentration is the central demand risk for Riviera resort assets.
The same scarcity drives the residential market. Cap Ferrat is the second most expensive coastal market in the world after Monaco, with prime villa values ranging from €25,000 to over €50,000 per square meter (Côte d’Azur Sotheby’s International Realty, Ultra-Prime Real Estate Report 2026). On that base, a 39% branded-residence premium produces some of the largest absolute euro-per-square-meter uplifts anywhere in the world.
US arrivals on the Riviera grew more than 10% in 2025, with Americans accounting for over 15% of international overnight stays, the single largest foreign market. Gulf, Japanese, Chinese, and Turkish demand all grew at double-digit or higher rates. A weak euro amplifies all of this: for a dollar- or dirham-denominated guest, French luxury is effectively discounted, supporting both ADR and the willingness of foreign buyers to acquire branded residences.
Branded Residences: The Second Value Engine
Branded residences are for-sale homes that carry a hotel or lifestyle brand, either attached to a hotel and serviced by it, or standalone. They have matured from a hotel add-on into a primary value-creation engine. The global scheme count grew from 169 in 2011 to about 611 in 2025, with a forecast of more than 1,000 by 2030 and a contracted pipeline of over 800 projects through 2032 (Savills, Branded Residences Report 2025/26). Standalone residences, with no attached hotel, now account for about a third of that global pipeline.
For developers, the residence is often the better-understood, faster-cash, lower-operating-risk half of a mixed hotel-and-residences scheme. The brand is paid through some combination of up-front key money (a one-time payment in a brand or management deal), a license fee on sales (typically 3% to 6% of net sales), and a recurring annual service fee from residents. Pre-sales of the residences de-risk the hotel development, which is why the mixed scheme is the strongest risk-adjusted play in the French market.
Branded Residence Structures Compared
| Structure | Description | Brand Payment | Investor Note |
|---|---|---|---|
| Hotel-attached | Homes beside a palace, sharing service | Key money + license % + service fee | Hotel underwrites premium; pre-sales de-risk build |
| Standalone branded | Residential-only under a hotel/lifestyle brand | License fee on sales + service fee | ~1/3 of global pipeline; no hotel operating drag |
| Heritage conversion | Landmark building converted to branded homes | License + premium on scarcity | Planning-intensive; highest scarcity value |
| Mixed-use scheme | Hotel + residences + retail in one asset | Blended fee + developer premium | Model as linked but separate cash-flow engines |
Hotel Yields and the Investment Market
France absorbed about €9.6 billion of the roughly €14.7 billion invested in European hotels in 2025, about two-thirds of the continent’s total, with Greater Paris alone trading some €1.9 billion across 75 assets and private capital accounting for about two-thirds of volume (Cushman & Wakefield, European Hotel Investment 2025). Prime Paris hotel yields settled at roughly 4.75% to 5.25% in H2 2025, having widened from sub-4.5% lows during the 2022–2024 rate shock before stabilizing as the bond market found a level. Paris luxury occupancy reached approximately 76.7% (STR/CoStar) in December 2025, underscoring how close the market is to its physical ceiling and why rate, not occupancy, is the primary return lever.
Genuine trophy assets price below 4.75% because high-net-worth individuals and family offices accept lower yields to secure properties that almost never trade. The implication for underwriting is direct: entry yields on the best French assets are structurally low and unlikely to compress much further. Returns therefore depend on rate growth, brand-led repositioning, and the residential premium, not on yield arbitrage.
| Asset Type | Indicative Net Yield | Liquidity | Modeling Note |
|---|---|---|---|
| Paris trophy palace | < 4.75% | Very thin; rarely trades | Rate growth, not yield, drives return |
| Paris prime luxury hotel | ~4.75–5.25% | Moderate; private buyers | Stabilized core underwriting |
| Riviera luxury / seasonal | Scarce trades; trophy priced | Very thin | Seasonality drives NOI volatility |
| Upper-upscale (non-palace) | ~5.5–6.5% | Deeper; more repeatable | More yield, less scarcity premium |
| Branded residence (for sale) | n/a — sold, not yielded | Pre-sales driven | Value via premium + fees, not cap rate |
Worked Example: Branded-Residence Premium Calculation
Here’s the math for a hypothetical Côte d’Azur branded-residence scheme, using the Base Case assumptions from the study.
Assume a developer acquires a site in Cap Ferrat where the unbranded prime residential price is €30,000 per square meter. The scheme comprises 20 units averaging 200 square meters each, for a total of 4,000 square meters of sellable area.
Step 1: Gross Development Value (GDV) without branding
4,000 m² × €30,000 = €120,000,000
Step 2: Apply the resort branded-residence premium (39% Base Case)
€120,000,000 × 1.39 = €166,800,000
Step 3: Deduct brand license fee (4% of net sales, mid-point of 3–6% range)
€166,800,000 × 0.04 = €6,672,000
Step 4: Net GDV to developer
€166,800,000 − €6,672,000 = €160,128,000
Step 5: Premium uplift to developer vs. unbranded
€160,128,000 − €120,000,000 = €40,128,000, or a 33.4% net uplift on the unbranded base.
With a 2-year Base Case sell-out and a 20% developer margin hurdle, the scheme clears the hurdle comfortably in the Base Case. In the Bear Case (28% premium), the net GDV falls to roughly €147.8 million after fees, compressing the margin toward or below the hurdle. That sensitivity is why pre-sales discipline and location scarcity are not optional: they are the margin of safety.
Three Scenarios to 2031
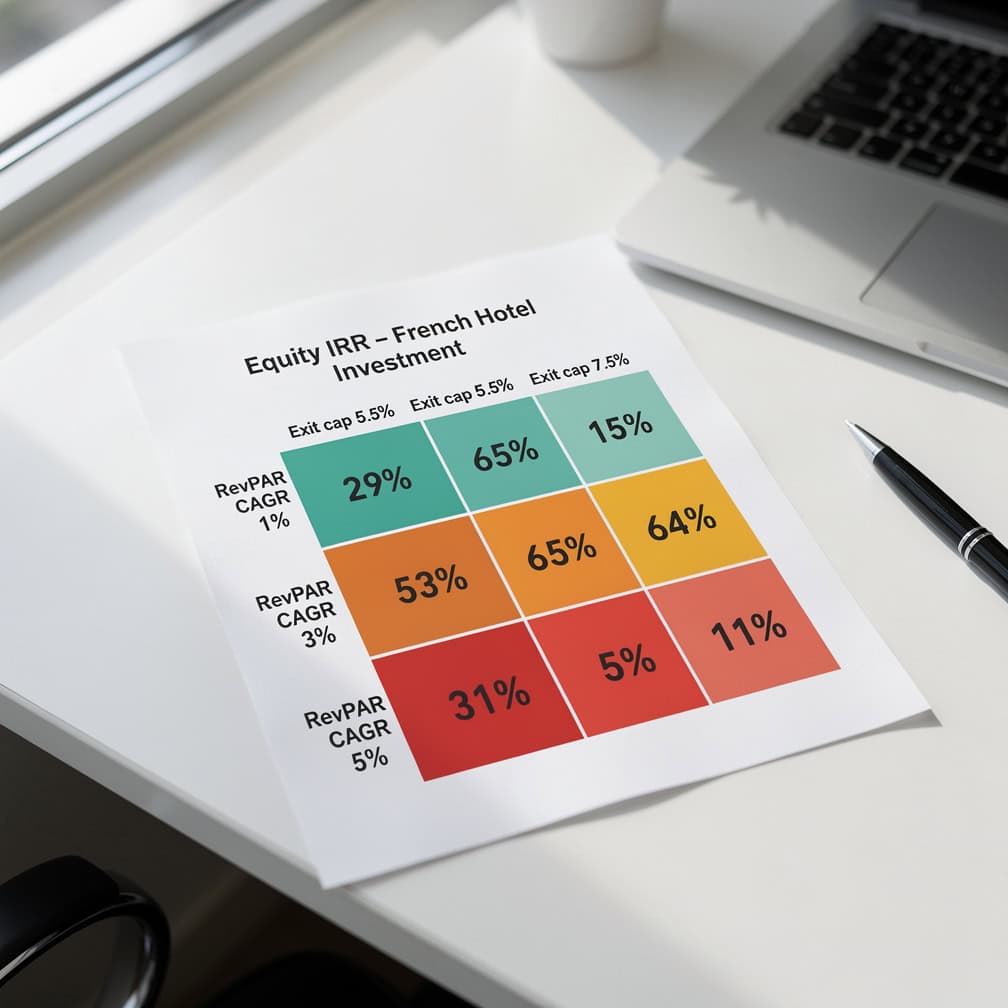
The study presents three scenarios, each with an assigned probability, covering luxury RevPAR growth, Paris occupancy, prime hotel yields, and the branded-residence premium at 2031.
| Variable at 2031 | Bear (25%) | Base (50%) | Bull (25%) |
|---|---|---|---|
| Luxury RevPAR CAGR 2026–31 | ~1.0%/yr | ~3.2%/yr | ~5.5%/yr |
| Paris luxury occupancy | ~71% | ~73% | ~75% |
| Paris prime hotel yield | ~5.5% | ~4.8% | ~4.3% |
| Branded-residence premium | ~28% | ~34% | ~42% |
| Developer margin | Below–at hurdle | Above hurdle | Well above hurdle |
The Bear Case is driven by a global wealth-and-travel slowdown, a stronger euro that erodes dollar and Gulf buyer discounts, tighter short-term-rental and planning rules, and softer cross-border capital flows. The Bull Case rests on sustained UHNW demand, a weak euro that flatters dollar- and dirham-denominated buyers, and a supply shortfall in genuine palace and branded product.
The key modeling insight: stress the rate and premium assumptions, not occupancy. Paris luxury occupancy is already near its ceiling, and the Riviera’s peak-season occupancy is near its physical limit. A downturn shows up in ADR and branded premiums first.
Regulation as a Supply Constraint and Competitive Moat
Regulation is now a first-order operating and supply variable, and it mostly favors luxury incumbents. The Loi Le Meur (Law 2024-1039 of 19 November 2024) tightens short-term-rental rules, including mandatory registration, lower annual day caps, energy-rating bans on poorly rated properties, and reduced tax allowances (Service-Public / Légifrance, 2024). This constrains the unbranded Airbnb substitute and channels demand toward professionally managed, brand-grade product. France’s short-term rental stock had grown to an estimated 800,000 listings before the law took effect (Légifrance, Loi n° 2024-1039), making the regulatory tightening one of the most consequential supply-side interventions in the European luxury hospitality market in recent years.
Urban-planning and change-of-use controls in Paris and on the Riviera limit new luxury hotel supply, pushing growth toward conversions, renovations, and residences within mixed-use schemes. Energy-performance requirements (the DPE retrofit regime) impose real capital expenditure on heritage assets, but they create a competitive advantage for well-capitalized brands that can fund deep renovations and a risk for those that cannot.
For the financial modeler, the practical implication is to treat the regulatory regime as a market- and asset-specific input: it lowers new supply risk for in-place owners, raises capital-expenditure assumptions on older assets, and constrains the unbranded competitive set. Regulation is an opportunity as much as a risk.
Common Modeling Mistakes to Avoid
Five specific errors appear repeatedly in financial models for French luxury hospitality.
1. Blending Paris and the Côte d’Azur into one pro forma. The two markets have different demand drivers, seasonality profiles, and yield benchmarks. Blending them hides the dynamics that drive returns. Build separate hotel pro formas for each market.
2. Modeling yield compression as the primary return driver. Entry yields on the best French assets are already structurally low. Returns come from rate growth, brand-led repositioning, and the residential premium. A model that underwrites a 100-basis-point yield compression on a Paris trophy asset is almost certainly wrong.
3. Treating the Palace distinction as permanent. The 2026 reassessment removed 3 hotels. The distinction is a three-year term, earned and revocable. Model the ADR and premium uplift it supports, and include a downgrade scenario that removes that uplift.
4. Modeling the hotel and residences as one cash-flow engine. The hotel and the branded residences have different revenue timing, risk profiles, and fee structures. Model them as linked but separate engines. The residence is often the faster-cash, lower-operating-risk half.
5. Stressing occupancy rather than rate in downside scenarios. Occupancy in Paris luxury is already near its ceiling. A wealth slowdown or currency reversal shows up in ADR and branded premiums, not in rooms sold. Stress the rate and premium assumptions.
Frequently Asked Questions
What is the Atout France Palace distinction, and why does it matter financially?
The Atout France Palace distinction is a state certification awarded above the five-star level, requiring a five-star prerequisite and renewed every three years. As of 2026, France has 33 Palace-distinguished hotels, up from 16 in 2015. Financially, the distinction matters because it is a certified scarcity signal that supports ADR, branded-residence pricing, and exit liquidity. A Palace hotel can justify higher room rates than an equivalent five-star without the distinction, and buyers of branded residences attached to a Palace pay a premium for the brand assurance it provides. The 2026 reassessment added 6 hotels and removed 3, confirming that the distinction is revocable and should be modeled with a downgrade tail risk.
How does the branded-residence premium work in practice?
The branded-residence premium is the percentage uplift in price per square meter that a for-sale home commands by carrying a hotel or lifestyle brand, compared with equivalent unbranded prime stock in the same locality. Globally, the premium averages about 33% across all markets and about 39% in resort markets (Savills, Branded Residences Report 2025/26). In France, the premium stacks on an already-extreme prime base: Paris prime runs €15,000 to €20,000-plus per square meter, and Cap Ferrat prime runs €25,000 to over €50,000 per square meter. A 39% premium on a €30,000 per square meter base produces a €11,700 per square meter uplift, among the largest absolute uplifts anywhere in the world. The developer pays the brand a license fee of roughly 3% to 6% of net sales plus key money and recurring service fees.
What is RevPAR and how is it calculated?
RevPAR stands for Revenue Per Available Room. It equals ADR (average daily rate, meaning average room revenue per occupied room) multiplied by occupancy (rooms sold divided by rooms available, expressed as a percentage). For example, Paris citywide in December 2025: ADR of €371.87 × occupancy of 76.7% = RevPAR of €285.13. RevPAR is the standard metric for comparing hotel operating performance because it captures both pricing power and how efficiently a hotel fills its rooms. For luxury assets where occupancy is already near its ceiling, ADR growth is the primary lever for RevPAR improvement, which is why the study focuses on rate rather than occupancy as the growth driver through 2031.
Why did France attract two-thirds of European hotel investment in 2025?
France absorbed about €9.6 billion of the roughly €14.7 billion invested in European hotels in 2025, approximately two-thirds of the continent’s total (Cushman & Wakefield, European Hotel Investment 2025). Several factors converged: Paris trophy assets offer irreplaceable locations and deep private-capital liquidity; a weak euro made French assets effectively discounted for dollar-, dirham-, and yen-denominated buyers; yields had stabilized after the 2022–2024 rate shock, reducing uncertainty; and the branded-residence model offered developers a faster-cash, lower-risk return profile alongside the hotel. Gulf, US, and Asian capital competed for scarce best-in-class stock, compressing trophy yields below 4.75% and confirming France as the preferred European destination for cross-border luxury-hotel capital.
How should I model the Côte d’Azur differently from Paris?
The Côte d’Azur is an intensely seasonal resort market whose annual financial result is concentrated in roughly 100 summer days, anchored by the Cannes Film Festival in May, the Monaco Grand Prix, and the July–August yachting season. Peak-season occupancy approaches 85% to 93% at the great palaces, and July–August ADRs run several times the shoulder-season rate. Paris, by contrast, is a year-round market with diversified demand across business, leisure, cultural, and event travel. In practice, this means the Riviera model must flex operating costs aggressively in the shoulder season, stress the annual result against a soft summer (which cannot be recovered later), and size event-driven and group demand as a distinct revenue line. A blended France model hides both the upside and the risk.
What does the Loi Le Meur mean for luxury hotel operators?
The Loi Le Meur (Law 2024-1039 of 19 November 2024) tightens short-term-rental rules across France, including mandatory registration for all furnished tourist rentals, lower annual day caps, bans on renting properties with poor energy ratings, and reduced tax allowances for rental income (Service-Public / Légifrance, 2024). For luxury hotel operators, the law is broadly positive: it constrains the unbranded Airbnb substitute that competes for the same high-value guests and channels demand toward professionally managed, brand-grade product. It also raises the cost and complexity of operating unbranded short-term rentals in prime Paris and Riviera locations, reinforcing the scarcity that underpins the luxury thesis. Modelers should treat it as a supply-side input that lowers the effective competitive set for branded operators.
What are the biggest risks to the French luxury hospitality thesis through 2031?
The dominant downside is a global wealth-and-travel slowdown amplified by a euro strengthening against the dollar, dirham, and Asian currencies. Because the French luxury market is increasingly underwritten by international UHNW demand, a sharp slowdown in global wealth or a meaningful currency reversal would hit guest demand, branded-residence buyer appetite, and cross-border capital flows simultaneously. The study assigns this risk a High severity rating. The second key risk is regulatory and energy friction: the DPE retrofit regime raises capital expenditure on heritage assets, which well-capitalized brands can absorb but which can erode returns on under-invested properties. A third risk is Riviera seasonality concentration: the annual result is made in roughly 100 days, and a soft summer cannot be recovered. The mitigant across all three is the scarcity floor: the best French assets are so supply-constrained that they hold value through cycles.
Conclusion
France’s luxury hospitality market enters the 2026–2031 window with three structural advantages that compound each other: the world’s most-visited destination status, a state-certified scarcity mechanism in the Palace distinction, and a branded-residence model that lets operators monetize their brand equity twice. The investment case rests on rate growth and residential premiums, not yield compression, which means the modeler’s job is to underwrite ADR, premium, and absorption with discipline, stress them against a wealth slowdown and a currency reversal, and treat Paris and the Côte d’Azur as the distinct markets they are.
I recommend pairing this analysis with the France Luxury Hospitality Market Study 2026–2031, which provides the full scenario envelope, Base Case pricing assumptions, and the quick-reference action checklist you need to build a credible hotel or branded-residence financial model for either market. For broader hospitality modeling resources, the EFM Hospitality Financial Model Bundle offers ready-to-use templates that pair directly with the study’s assumptions.























































